Thursday, 6 September 2012

Wealth Expo 2012


During the Expo, there were approx 4000 attendees for the event. Everything was fine until one 'friend' decides to drag me into his ugly commentary of the Expo. He was overexpecting for the event, in the end, it turns out to be not what he expected, shitted on me decides to write a lotsa negative comments on the event. By the way... he was expecting tonnes of very valuable information to be shared during a public event... How realistic is that??

Speakers do sell their products. Like it or not, everyone in the market sells their product(courses). Normally these speakers will give a short introduction to their courses, giving some free information so as to entice people from joining their course. 

There are speakers who are really good at what they are doing, some are just exploiting this business. Of cause i will not be mentioning names over here but it is very important to research your 'teachers' before you even sign up for their class because they tell you it's easy and you can be a millionaire. Be realistic and think critically. 


I'm very very fortunate to have Conrad Alvin Lim(http://www.conradalvinlim.com/) to be my mentor and honestly I have learnt a lot from that man. Conrad, if you have not attended his preview,he does not hype his students up and tell them 'you can be a millionaire'. We're always told... The trading journey is a very long and tough journey. Preserve your capital so when you are ready to trade, you still have capital to make your losses back. 

Hardwork, patience, discipline are often emphasized during the class.. We do not sell dreams.. And guess what... these are the things that everyone hates. 

Trading based on macroeconomics and market sentiments make this man's course very special. 

To be honest, his course is not expensive, it's in the region of $5k. You shall find out the exact price during the preview. And if you have been into previews and stuff... Options alone will cost you more than that. During the course, currency trading, futures trading, equity trading has been covered. 

We're trained as traders who're versatile enough to follow the flow of money from different sectors to different instruments. 

Some reviews are saying that his course is expensive and stuff... and i'll beg to differ.... 

If you are paying $100k for a Honda, you might be saying it's expensive... however, if someone offers you a $100k for a ferrari, you'll screaming it's dead cheap.

Look at the value, not the price tag. 

If you are interested increasing your financial knowledge or you're a total newbie, feel free to look at Conrad's blog for more information.   

I have been a Triple Science Student since secondary school till Junior college. All that in my head was Sciences. For someone like me to become financial literate enough to be the research director of the investment club in Singapore Institute of Management, I must have been trained really well. That what makes me to that level of financial proficiency, is through the course called... The Wealth Academy Trader. (http://www.conradalvinlim.com/wat-24-november-schedule/)


Took a picture with Chris Gardner at the backstage due to some special privileges. This man is a legend and i'm really honored to meet this legend. 

In case you didn't know about Chris, Will Smith was starring in back in 2006 in the movie, Pursuit of Happyness.

5 Sep 2012 AMC

5 September 2012
Market Summary


This is definitely a very choppy day in the market... Awaiting for major data coming out from Europe and US this week... Luckily I took my profits off the table before the crazy gyration starts...

Market Internals


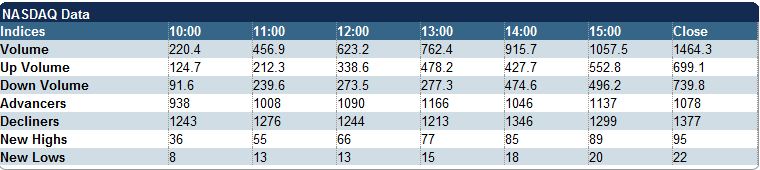
It was really some fierce fight between the bulls and bears yesterday... but judging by the economic calendar, i presume that people are taking their long/short positions off or starting to hedge again their positions that created such gyration

Leaders and laggards


As you can see... it's flat...

Technical Updates


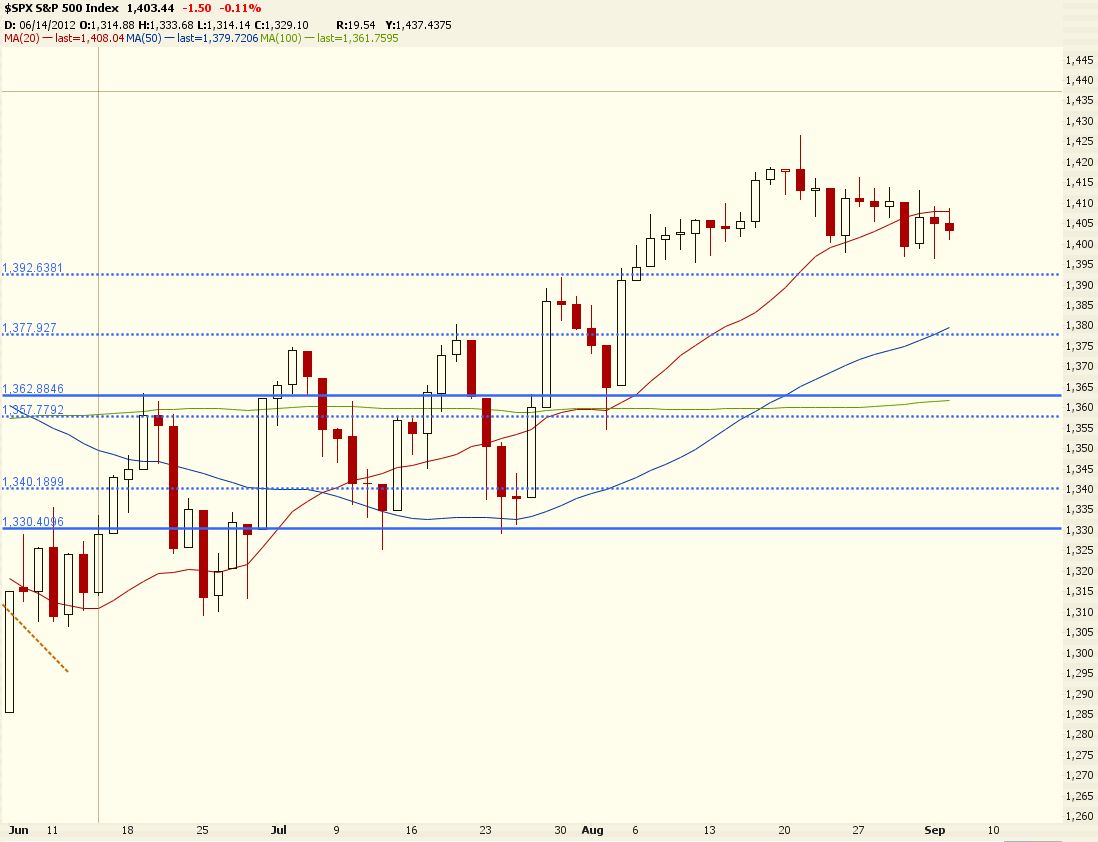
On the technicals, the major indices found support at 1400 and 13000. A major catalyst is need to make or break this trend. And we'll know it tomorrow. 
 
 
Commentaries


Stock Market Update
16:15 ET Dow +11.54 at 13052.66, Nasdaq -5.79 at 3069.27, S&P -1.50 at 1403.44 :[BRIEFING.COM] Equities spent the majority of the session chopping around the unchanged line. The early morning volatility coincided with a Bloomberg TV report which indicated the European Central Bank bond purchase program is said to pledge unlimited, sterilized buying of bonds. However, the exuberance was short-lived as European Central Bank officials declined to comment, and reports out of Germany suggested Chancellor Angela Merkel would only support the program in the near-term. Afternoon trade was mostly quiet as the S&P 500 remained in a narrow range before closing lower by 0.1%. 

The telecom sector got off to a strong start and maintained its gains throughout the day.Sprint (S 4.95, +0.15) advanced 3.1% as it outperformed other holdings within theiShares Dow Jones US Telecom ETF (IYZ 24.39, +0.13). 

The Dow Jones Transportation Average continued its recent streak of underperformance; however, individual components within the group showed significant divergence. Shares of major airlines saw a relatively strong bid as United Continental Holdings (UAL 19.07, +0.97) led the major carriers with a 5.4% gain. Delta Air Lines (DAL 8.89, +0.33) added 3.9% after announcing August consolidated passenger unit revenue increased by 4.0% on a year-over-year basis. Meanwhile, companies specializing in logistics slipped afterFedEx (FDX 85.80, -1.74) lowered its first quarter guidance, citing weaker global demand. FedEx shed 2.0% while UPS (UPS 71.94, -1.76) slid 2.4% and Con-way (CNW 29.97, -1.21) ended lower by 3.9%. 

Financial stocks have traded mostly in-line with the broader market. However, several names diverged from the rest of the group. Goldman Sachs (GS 109.94, +3.53) was the best performer as it ended higher by 3.3%. On the downside, American Express (AXP 57.19, -1.42) dipped 2.2% as it trailed the other majors. Elsewhere, European financials were mostly higher with UBS (UBS 11.38, +0.29) and Credit Suisse (CS 19.24, +0.34) posting gains of 2.6% and 1.8%, respectively. 

Restaurant operator Bloomin' Brands (BLMN 13.86, +0.41) advanced 3.1% after delivering its first earnings report as a publically traded company. The quarterly report showed second quarter earnings growth of 23.0% compared to the same period last year. Meanwhile, two names which began trading within the past twelve months also finished on a positive note. Facebook (FB 18.58, +0.85) closed higher by 4.8% after announcing Chief Executive Officer, Mark Zuckerberg, has no intention to sell any shares for at least twelve months. Meanwhile, Jefferies initiated coverage of the stock with a ‘buy' rating and a $30.00 price target. Zynga (ZNGA 2.92, +0.09) rose by 3.2% as it benefited from the strength in Facebook. 

Nokia (NOK 2.38, -0.45) slumped 15.9% after the company unveiled its new Lumia 920 phone which features an improved camera and wireless charging capabilities. The phone is based on the Windows operating system, developed by Microsoft (MSFT 30.39, +0.01). 

Productivity data for the second quarter showed an increase of 2.2%, which was an improvement over the 1.6% increase that had been reported in the preliminary reading. It is also better than the 1.8% increase that had been broadly expected. Unit labor costs for the first quarter were revised lower to reflect a 1.5% increase after they had reportedly increased by 1.7% in the preliminary reading. Economists polled by Briefing.com had expected that unit labor costs would tick down in the revised reading to reflect an increase of 1.4%. 

A handful of economic data points will be released tomorrow. Challenger job cuts will be reported at 7:30 ET. ADP Employment Change is scheduled for an 8:15 ET release, while initial and continuing claims will hit the wires at 8:30 ET. The ISM Services report will top off the day's data at 10 ET. 

Also of note, the European Central Bank will announce its interest rate decision at 7:45 ET which will be followed by Mario Draghi's press conference at 8:30 ET. In addition, the Bank of England will opine tomorrow morning at 7:00 ET. The central bank is expected to keep both its benchmark interest rate and its asset purchase program steady at 0.50% and GBP375 billion. ..NYSE Adv/Dec 1407/1553. ..NASDAQ Adv/Dec 1078/1381.


After Hours
17:20 ET MIND +5.5%, GIS +0.9%, PAY -10.7% following earnings/guidance :
Equities spent the majority of the session chopping around the unchanged line. The early morning volatility coincided with a Bloomberg TV report which indicated the European Central Bank bond purchase program is said to pledge unlimited, sterilized buying of bonds. However, the exuberance was short-lived as European Central Bank officials declined to comment, and reports out of Germany suggested Chancellor Angela Merkel would only support the program in the near-term. Afternoon trade was mostly quiet as the S&P 500 remained in a narrow range before closing lower by 0.1%.
Today after the close the following companies reported earnings: ABM, AVAV, FCEL, HRB, HWD, KFY, MTRX, MW, MIND, SEAC, SIGM, STEI, PAY, VRNT
Futures are higher after hours: S&P 500 futures are +1.93 from fair value of 1402.27 and Nasdaq100 futures are +2.26 from fair value of 2765.99.
Tomorrow morning before the open three economic reports are scheduled to be released: 1) Challenger Job Cuts, 2) ADP Employment Change (Consensus 143k), and 3) Initial Claims (Consensus 373k) and Continuing Claims (Consensus 3300k).
Tomorrow before the open look for the following companies to report: HOV, LAYN, MPR, NAV, UTIW


Commodities


Crude oil inventory report somehow got delayed till 6 Sep for release... I wonder is the person handling it was on MC or what...

Treasuries 


As i said... not much changes to the treasuries on such a flat day..


Not going to make any market calls in view of Draghi's speech and the non-farm payrolls...


Saturday, 1 September 2012

31 August 2012 AMC + Weekly Outlook


31 August 2012

Market Summary


What a crazy gyration during the Jackson Hole Symposium... Right at the start of Ben Bernanke's speech, market was up 100 points on the DOW. The moment Bernanke start talking, the DOW wiped out its gains for the day until his last sentence, sent the DOW back up to about 100 points. 

Here's Bernanke's last line for his speech... 


By the last sentence of his speech,

 as the line says ' the Federal Reserve will provide additional policy accommodation as needed to promote a stronger economic recovery and sustained improvement...' hints the readiness of Ben to start another QE and his defence of the past QEs versus the benefits/costs.

This is really a bullish day..... 

 Check the internals out... 
Bears were totally out of the picture until the last hour where people started to profit take in view of Draghi's speech on Monday. 

Prepare for some crazy gyration for the coming weeks! 


Market Internals


Leaders and laggards


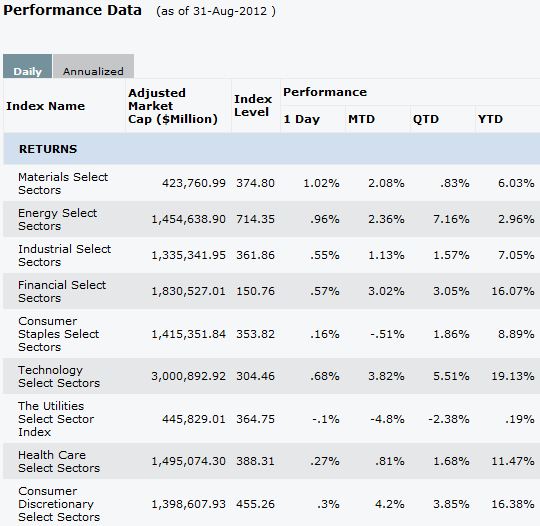
I was pretty surprised that the financial did not lead the day but except Materials and Energy... 


Technical Updates


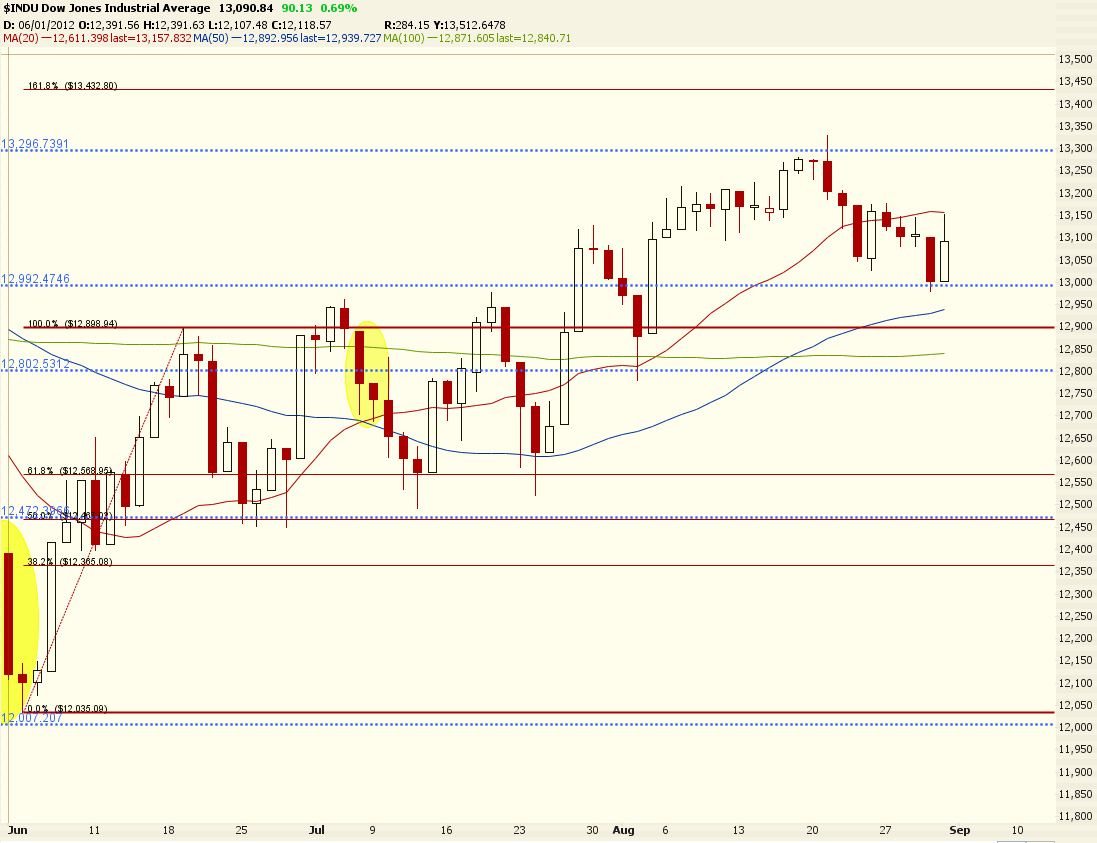
A chopstick bottom on the DOW and a Bullish Harami on the SPX. Seems that it's heading upwards... but if Draghi comes out with something lesser than the market's expectation.... the pattern gonna fail!


Commentaries


Stock Market Update
16:10 ET Dow +90.13 at 13096.02, Nasdaq +18.25 at 3066.96, S&P +7.10 at 1406.58 :[BRIEFING.COM] Stocks got off to a strong start before stumbling slightly when Federal Reserve Chairman Ben Bernanke did not hint at additional easing, but instead reaffirmed his commitment to act if economic conditions worsen. Mr. Bernanke commented on the stagnation of the labor market, calling it a "grave concern" which bears monitoring. While Bernanke wasn't expected to roll out a new round of quantitative easing at this venue, the discussion of the costs of nontraditional policies may temper expectations for additional easing in the absence of greater economic deterioration. As a result, the S&P 500 finished higher by 0.5%. 

Shares of major financials were broadly higher early in the session. However, most names slipped off their highs after it became clear that additional quantitative easing is not imminent. Goldman Sachs (GS 105.72, +1.00) and American Express (AXP 58.30, +1.13) ended higher by 1.0% and 2.0%, respectively. Meanwhile, European financials saw even bigger advances as plans to create a Spanish "bad bank" surfaced. Banco Bilbao Vizcaya Argentaria (BBVA 7.53, +0.36) gained 5.0%, while Deutsche Bank(DB 35.45, +1.59) and Credit Suisse (CS 19.25, +0.68) advanced 4.7% and 3.7%, respectively. 

Energy stocks outperformed the broader market with the S&P energy sector firmer by 0.9% as the fear of hurricane-related disruptions dissipates. Anadarko Petroleum (APC 69.27, +1.01), and EOG Resources (EOG 108.30, 2.41) added roughly 1.7%. Elsewhere in the sector, China Ming Yang Wind Power Group (MY 1.21, +0.06) jumped 5.2% after forming a joint venture to develop additional wind and solar power technology with Huaneng Renewables. On the downside, Arch Coal (ACI 6.11, -0.07) slipped 1.1% after announcing the company's Senior Vice President of Marketing, David Warnecke, will retire in May 2014. 

Utility stocks underperformed the broader market as most names in the SPDR Utilities Select Sector ETF (XLU 36.35, -0.04) traded lower. PG&E (PCG 43.41, -0.15), Exelon(EXC 36.47, -0.12), and Southern Company (SO 45.33, -0.05) were all down near 0.3%. Meanwhile, U.S. listings of Brazilian utility companies were under heavy pressure asCentrais (EBR 6.50, -0.45), Companhia Paranaense de Energia (ELP 17.79, -0.71), and Cia Energetica de Minas Gerais (CIG 17.00, -0.84) slumping between 4.5% and 6.5%. 

Facebook (FB 18.06, -1.03) fell 5.4% after Stifel Nicolaus said that despite attractive valuation, it may still be too early to invest in the company as insider selling continues. Today's selling has pushed the stock down to $18.06, which is the lowest price since the initial public offering in May. Zynga (ZNGA 2.80, -0.09) and Groupon (GRPN 4.15, -0.04), two companies which have recently held their initial public offerings, slid 3.1% and 1.0%, respectively. Zynga traded $0.15 above its all-time low, while Groupon marked fresh lows. 

The volatility index, or VIX, shed 1.5%, to 17.56. Two weeks ago, the volatility measure marked a 5-year low at 13.45, and has been on a steady rise since. This week alone, the VIX has risen by 8.5%. 

Today's economic data was mixed. The August Chicago PMI of 53.0 surprised to the downside as economists had generally expected a reading of 53.8 to follow the prior month's 53.7. Elsewhere, the University of Michigan's final Consumer Sentiment Survey for August rose to 74.3 from the 73.6 that was posted in the preliminary Survey. Separately, July Factory Orders showed an increase of 2.8%, which was better than the Briefing.com consensus of a 2.0% increase. 

On Tuesday, the August ISM Index and July construction spending will be reported at 10:00 ET. In addition, August auto and truck sales will be released at 14:00 ET. 

Week in Review: Markets Quiet Ahead of Jackson Hole 
Monday's session began on a positive note before stocks retreated to the unchanged line. As the European markets closed for the day, U.S. stocks lifted to session highs, but the gains did not hold into the close. As a result, the S&P 500 finished flat on low volume while the Dow shed 0.3%. Apple (AAPL 665.24, +1.37) advanced 1.9% after winning its patent battle against Samsung. 

On Tuesday, Equities spent the majority of the session within points of the unchanged line. The August consumer confidence report printed at 60.6, which was the lowest level in nine months. Following the report, stocks briefly turned lower before snapping back to the unchanged line where they held for the remainder of the session. Luxury goods makerMovado (MOV 35.16, +0.19) soared 17.4% after beating earnings expectations by $0.14 a share. 

Wednesday's lackluster session saw equities hover within points of the flat line for the majority of the day. Economic data was mostly positive, but did little to inspire investor confidence. As a result the S&P 500 ended higher by 0.1% on light volume. Yelp (YELP 22.00, +0.31) surged 22.5% despite the share lock-up expiry. 

On Thursday, equities hit session lows during the first hour of trade before spending the rest of the day climbing off those levels. Headlines out of Europe indicated the International Monetary Fund sees a "major challenge" in implementing measures for Greece. Another comment which rattled the markets came from Slovak Prime Minister, Robert Fico, who suggested there is a 50% chance of a euro area breakup. The news resulted in a sharp sell-off in risk assets as crude oil, gold, silver, and the euro all fell to session lows. Stocks were able to recover some of their losses before succumbing to late-day selling pressure which resulted in the S&P 500 closing lower by 0.8%. Costco Wholesale (COST 97.87, -0.72) advanced 1.5% after August same store sales increased by 6.0%. ..NYSE Adv/Dec 2065/870. ..NASDAQ Adv/Dec 1548/920.


Commodities


Treasuries 


The treasuries sold off when helicopter ben spoke.... Man... this man's mouth is powerful....

Week 35


Technical Updates


Commentaries


Weekly Wrap 
Dow +90.13 at 13096.02, Nasdaq +18.25 at 3066.96, S&P +7.10 at 1406.58

Stocks got off to a strong start before stumbling slightly when Federal Reserve Chairman Ben Bernanke did not hint at additional easing, but instead reaffirmed his commitment to act if economic conditions worsen. Mr. Bernanke commented on the stagnation of the labor market, calling it a "grave concern" which bears monitoring. While Bernanke wasn't expected to roll out a new round of quantitative easing at this venue, the discussion of the costs of nontraditional policies may temper expectations for additional easing in the absence of greater economic deterioration. As a result, the S&P 500 finished higher by 0.5%. 

Shares of major financials were broadly higher early in the session. However, most names slipped off their highs after it became clear that additional quantitative easing is not imminent. Goldman Sachs (GS 105.72, +1.00) and American Express (AXP 58.30, +1.13) ended higher by 1.0% and 2.0%, respectively. Meanwhile, European financials saw even bigger advances as plans to create a Spanish "bad bank" surfaced. Banco Bilbao Vizcaya Argentaria (BBVA 7.53, +0.36) gained 5.0%, while Deutsche Bank (DB 35.45, +1.59) and Credit Suisse (CS 19.25, +0.68) advanced 4.7% and 3.7%, respectively. 
Energy stocks outperformed the broader market with the S&P energy sector firmer by 0.9% as the fear of hurricane-related disruptions dissipates. Anadarko Petroleum (APC 69.27, +1.01), and EOG Resources (EOG 108.30, 2.41) added roughly 1.7%. Elsewhere in the sector, China Ming Yang Wind Power Group (MY 1.21, +0.06) jumped 5.2% after forming a joint venture to develop additional wind and solar power technology with Huaneng Renewables. On the downside, Arch Coal (ACI 6.11, -0.07) slipped 1.1% after announcing the company's Senior Vice President of Marketing, David Warnecke, will retire in May 2014. 
Utility stocks underperformed the broader market as most names in the SPDR Utilities Select Sector ETF (XLU 36.35, -0.04) traded lower. PG&E (PCG 43.41, -0.15), Exelon (EXC 36.47, -0.12), and Southern Company (SO 45.33, -0.05) were all down near 0.3%. Meanwhile, U.S. listings of Brazilian utility companies were under heavy pressure as Centrais (EBR 6.50, -0.45), Companhia Paranaense de Energia (ELP 17.79, -0.71), and Cia Energetica de Minas Gerais (CIG 17.00, -0.84) slumping between 4.5% and 6.5%. 
Facebook (FB 18.06, -1.03) fell 5.4% after Stifel Nicolaus said that despite attractive valuation, it may still be too early to invest in the company as insider selling continues. Today's selling has pushed the stock down to $18.06, which is the lowest price since the initial public offering in May. Zynga (ZNGA 2.80, -0.09) and Groupon (GRPN 4.15, -0.04), two companies which have recently held their initial public offerings, slid 3.1% and 1.0%, respectively. Zynga traded $0.15 above its all-time low, while Groupon marked fresh lows. 
The volatility index, or VIX, shed 1.5%, to 17.56. Two weeks ago, the volatility measure marked a 5-year low at 13.45, and has been on a steady rise since. This week alone, the VIX has risen by 8.5%. 
Today's economic data was mixed. The August Chicago PMI of 53.0 surprised to the downside as economists had generally expected a reading of 53.8 to follow the prior month's 53.7. Elsewhere, the University of Michigan's final Consumer Sentiment Survey for August rose to 74.3 from the 73.6 that was posted in the preliminary Survey. Separately, July Factory Orders showed an increase of 2.8%, which was better than the Briefing.com consensus of a 2.0% increase. 
On Tuesday, the August ISM Index and July construction spending will be reported at 10:00 ET. In addition, August auto and truck sales will be released at 14:00 ET. 
Week in Review: Markets Quiet Ahead of Jackson Hole 
Monday's session began on a positive note before stocks retreated to the unchanged line. As the European markets closed for the day, U.S. stocks lifted to session highs, but the gains did not hold into the close. As a result, the S&P 500 finished flat on low volume while the Dow shed 0.3%. Apple (AAPL 665.24, +1.37) advanced 1.9% after winning its patent battle against Samsung. 
On Tuesday, Equities spent the majority of the session within points of the unchanged line. The August consumer confidence report printed at 60.6, which was the lowest level in nine months. Following the report, stocks briefly turned lower before snapping back to the unchanged line where they held for the remainder of the session. Luxury goods maker Movado (MOV 35.16, +0.19) soared 17.4% after beating earnings expectations by $0.14 a share. 
Wednesday's lackluster session saw equities hover within points of the flat line for the majority of the day. Economic data was mostly positive, but did little to inspire investor confidence. As a result the S&P 500 ended higher by 0.1% on light volume. Yelp (YELP 22.00, +0.31) surged 22.5% despite the share lock-up expiry. 
On Thursday, equities hit session lows during the first hour of trade before spending the rest of the day climbing off those levels. Headlines out of Europe indicated the International Monetary Fund sees a "major challenge" in implementing measures for Greece. Another comment which rattled the markets came from Slovak Prime Minister, Robert Fico, who suggested there is a 50% chance of a euro area breakup. The news resulted in a sharp sell-off in risk assets as crude oil, gold, silver, and the euro all fell to session lows. Stocks were able to recover some of their losses before succumbing to late-day selling pressure which resulted in the S&P 500 closing lower by 0.8%. Costco Wholesale (COST 97.87, -0.72) advanced 1.5% after August same store sales increased by 6.0%.


Next Week in View


Market Call: 1 Sept
Date: NO CALL!!! DRAGHI IS SPEAKING!


Market Call(Weekly): NO CALL!!! DRAGHI IS SPEAKING!AND NON FARM PAYROLLS! 

Date: Week 36