Tuesday, 16 October 2012

15 Oct 2012 AMC

15 Oct 2012
Market Summary 


Moving the Market

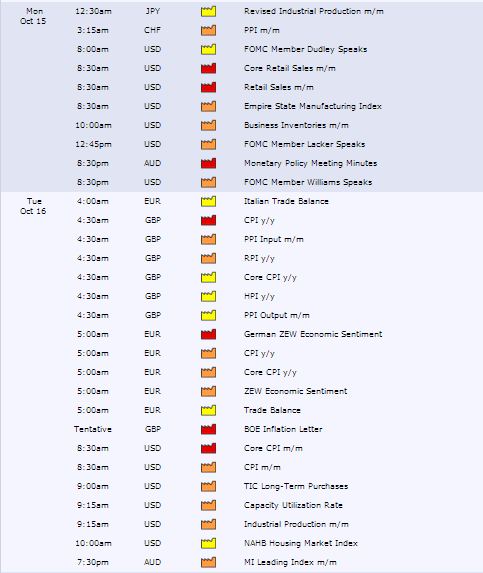
September retail sales: +1.1% actual versus +0.7% expected. Prior revised up to +1.2%.
Retail sales ex-auto: +1.1% actual versus +0.6% expected.
October Empire State Manufacturing Survey: -6.2 actual versus -2.8 expected, -10.4 prior.

CPI (8:30): Briefing 0.5%, consensus 0.5%, prior 0.6%
Core CPI (8:30): Briefing 0.1%, consensus 0.2%, prior 0.1%
Net Long-Term TIC Flows (9): Prior $67.0B
Industrial Production (9:15): Briefing 0.0%, consensus 0.3%, prior -1.2%
Capacity Utilization (9:15): Briefing 78.2%, consensus 78.3%, prior 78.2%
NAHB Housing Market Index (42, consensus 42, prior 40)

 DOW +95.38(+0.72%)
NASDAQ +20.07(+0.66%)
SPX +11.54(+0.81%)

The market yesterday rallied yesterday as the retail sales is well better than expectation. However, the Empire State Manufacturing Survey fall below expectation. Well, kinda fall in line with my expectation of upside...
Market Internals


it was clearly a up day... The volume was decent yesterday...


Leaders and Laggards


The leaders yesterday were the Healthcare, Financials and the Discretionary sector. Kinda good run up to the presidential election...


Technical Updates


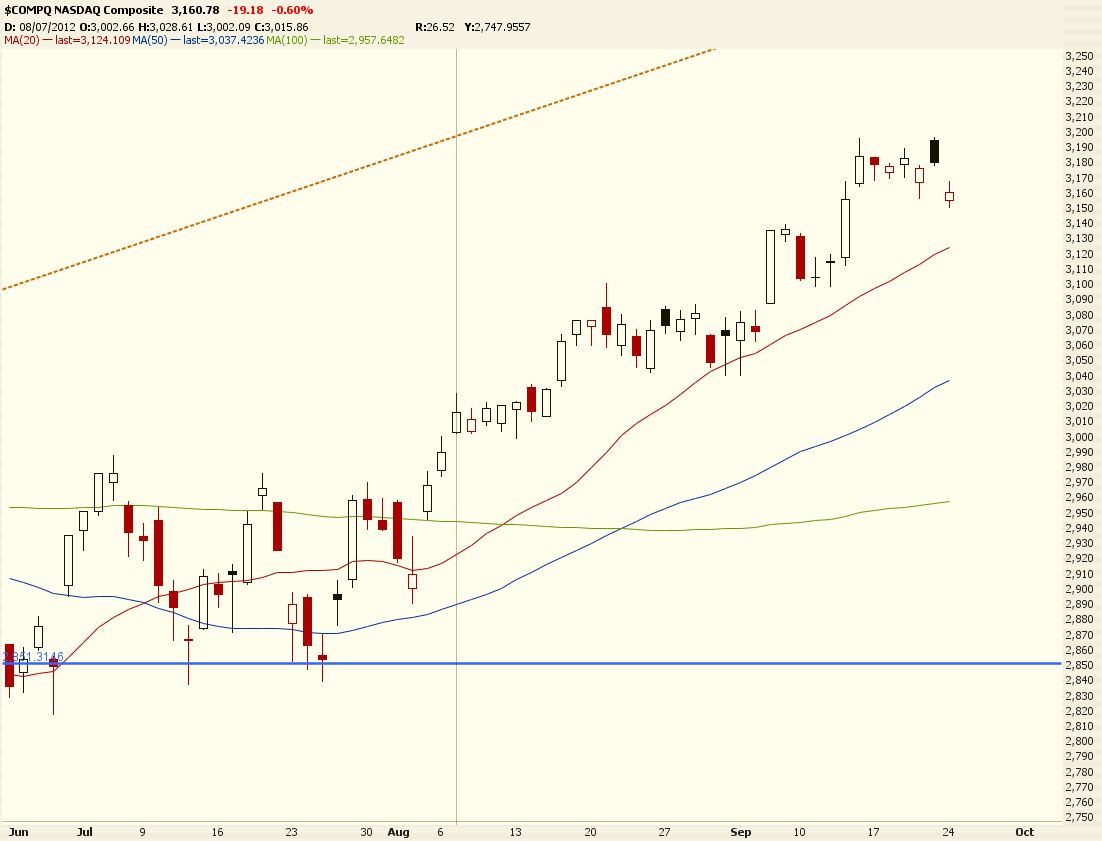
Oh well... seems that the support worked well! and this is definitely a bullish candlestick pattern.. This week is likely to be a very volatile week ahead! Tough fight between the bulls and the bears..


Commentaries 


Stock Market Update
16:15 ET Dow +95.38 at 13424.23, Nasdaq +20.07 at 3064.18, S&P +11.54 at 1440.13 : [BRIEFING.COM] Equities got off to a slow start as the major averages spent the first 90 minutes near their respective unchanged levels. Today's economic data was mixed, and did little to move the markets. After early indecision, the three indices rose to their session highs, and maintained those levels into the afternoon. The S&P 500 saw brief afternoon weakness before late-day buying lifted the index to a gain of 0.8%. 

Financial stocks showed strength after Citigroup (C 36.66, +1.91) beat its earnings expectations by $0.07 and reported revenue of $19.4 billion. The shares of the financial giant settled higher by 5.5%, and outperformed the remaining majors. Bank of America(BAC 9.44, +0.32), Goldman Sachs (GS 124.50, +4.30), and Morgan Stanley (MS 17.75, +0.44) also outperformed the sector. The three financials added between 2.5% and 3.6%. Note that Goldman Sachs will report its third quarter earnings before tomorrow's opening bell. 

Meanwhile, American Express (AXP 57.59, -0.30) and Wells Fargo (WFC 33.90, -0.35) missed out on the rally, and registered respective losses of 0.5% and 1.0%. 

Health care stocks led the broader market. Within the space, drug manufacturers saw the most notable gains. Eli Lilly (LLY 52.53, +2.08) added 4.1% after Leerink Swann upgraded the stock to ‘outperform' from ‘market perform.' 

Abbott Labs (ABT 72.05, +2.77) advanced 4.0% after the company released encouraging results from the Phase 2b study of its interferon-free investigational regimen for the treatment of hepatitis C. 

Meanwhile, Bristol-Myers Squibb (BMY 33.93, +0.84) gained 2.5%. 

On the downside, Amedisys (AMED 12.08, -1.25) sank 9.4% after announcing a new health services agreement with insurer Humana (HUM 74.73, -0.09). Per the updated agreement, Amedisys will generate revenue levels of approximately half of the prior amount earned from Humana. 

Telecom stocks were the biggest laggard of the session. The sector underperformance stemmed from weakness demonstrated by an industry leader. AT&T (T 35.21, -0.42) slid 1.2% after SoftBank confirmed its plans to invest $20.1 billion in Sprint Nextel (S 5.69, -0.04). The investment is expected to create tougher competition for both AT&T andVerizon (VZ 44.50, -0.12). In addition Sprint is expected to acquire Clearwire (CLWR 2.69, +0.37). 

The Dow Jones Transportation Average trailed the broader market, and settled higher by 0.4%. Within the bellwether group, railroads were mixed. Kansas City Southern (KSU 74.70, -0.45) and Union Pacific (UNP 120.93, -0.12) shed between 0.1% and 0.6% Meanwhile, CSX (CSX 21.45, +0.14) added 0.7% despite being downgraded to ‘peer perform' from ‘outperform' by Wolfe Trahan. Note that CSX will report its third quarter earnings after tomorrow's market close. 

September retail sales rose by 1.1%, which was better than the 0.7% increase that had been broadly expected. The prior month's reading was revised up to show an increase of 1.2%. Excluding autos, retail sales rose by 1.1%, which was ahead of the Briefing.com consensus call for a rise of 0.6%. 

Separately, the Empire Manufacturing Survey for October registered a reading of -6.2, which was up from the prior month's reading of -10.4. Economists polled by Briefing.com had expected, on average, that the Survey would rise to -2.8. 

Lastly, during August, inventories rose by 0.6% which was slightly above the 0.5% that had been expected. This follows prior month's reading of 0.8%. 

Tomorrow, September CPI and core CPI will be reported at 8:30 ET. August net long-term TIC flows will be released at 9:00 ET, while September industrial production and capacity utilization will be announced at 9:15 ET. Lastly, the October NAHB Housing Market Index will hit the wires at 10:00 ET. ..NYSE Adv/Dec 2016/999. ..NASDAQ Adv/Dec 1562/895.


After Hours
17:28 ET JOEZ +5.2%, RATE -25.9%, WDFC -9.2% following earnings/guidance :
Equities got off to a slow start as the major averages spent the first 90 minutes near their respective unchanged levels. Today's economic data was mixed, and did little to move the markets. After early indecision, the three indices rose to their session highs, and maintained those levels into the afternoon. The S&P 500 saw brief afternoon weakness before late-day buying lifted the index to a gain of 0.8%.
Today after the close the following companies are scheduled to report earnings: BRO, ICUI, PKG, WDFC, CPSS, JOEZ
Futures are mixed after hours: S&P 500 futures are +0.51 from fair value of 1435.09 and Nasdaq100 futures are -1.97 from fair value of 2733.72.
Tomorrow morning before the open four economic reports are scheduled to be released: 1) CPI (Consensus 0.5%) and Core CPI (Consensus 0.2%), 2) Net Long-Term TIC Flows, 3) Industrial Production (Consensus 0.3%) and 4) Capacity Utilization (Consensus 78.3%).
Tomorrow before the open the following companies are scheduled to report earnings: KO, CBSH, DPZ, FRX, GS, IRWD, JNJ, MAT, OMC, PNC, STT, UNH, GWW, WWW


Commodities


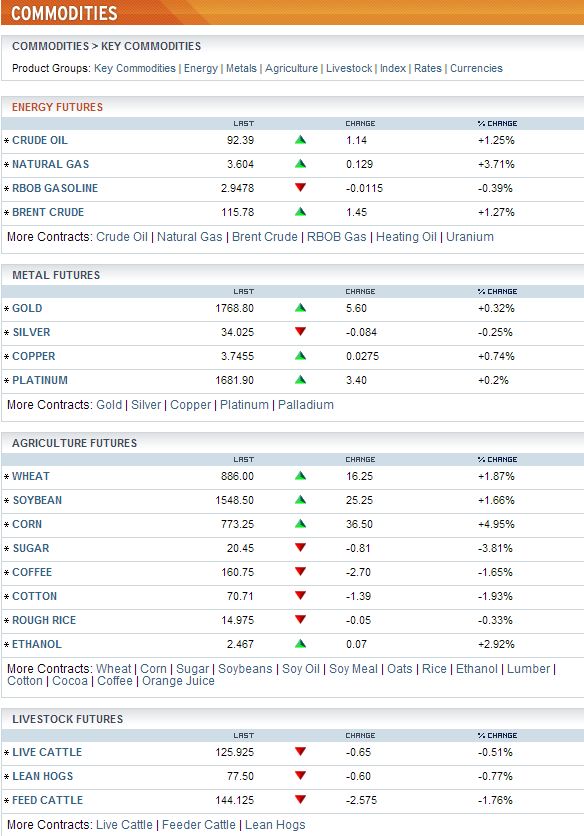
The market is awaiting the USDA report today for the agricultural futures... It's gonna be flat for now and then gonna be volatile like hell...


Treasuries


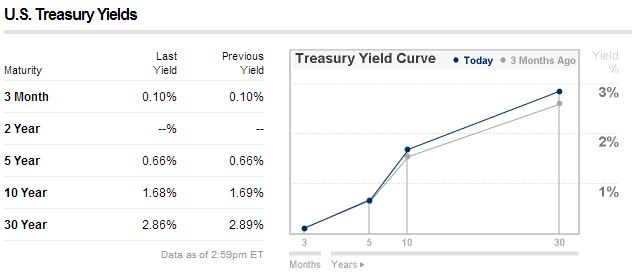
Not much movements in the treasuries yesterday... There will be the CPI report coming out in the US today, alongside with the EUR and GBP side. Not gonna be a major movement today...


Market Call: FLAT(to upside)
Date: 16 Oct 2012

Sunday, 14 October 2012

12 Oct 2012 AMC


12 Oct 2012 AMC

Market Summary 


Time for the market analysis!! Was busy during the weekend but finally got the time to write my analysis..

Last friday, the 3 of the major DOW components held DOW up for the day, but the majority of the DOW components were down.. SPX and NASDAQ was down... so it's quite apparent it's a down day...


Market Internals


Looking at the internals... the DVOL immediately gave away that it was a down day except it ended flat... I won't be surprised if tomorrow is going to be a down monday as well...


Leaders and Laggards


Looking at the main sectors... the telco lead the decliners again... this time round... financials joined in the fun.. the financials were dragged down by the 2 biggest name in the financials, namely JP morgan and Wells Fargo.


Technical Updates


Now all the indices are holding still at the neckline...

Commentaries 


Stock Market Update
16:20 ET Dow +2.46 at 13328.85, Nasdaq -5.30 at 3044.11, S&P -4.25 at 1428.59 :[BRIEFING.COM] Today's session got off to a quiet start. The major averages held near their opening levels until the preliminary October University of Michigan Consumer Sentiment Survey registered a reading of 83.1. The survey's best level since September 2007 lifted the major averages to their session highs. However, the exuberance was short-lived as the key indices promptly fell through the unchanged line, to their session lows. The afternoon was generally quiet as the S&P 500 hovered within points of the 1,428 level before settling at 1,428.59, with a loss of 0.3%. Note that today's session punctuated a down week, during which the S&P 500 lost 2.2%.

The financial sector was the biggest laggard of the day. Despite record earnings from two major names, the SPDR Financial Select Sector ETF (XLF 15.81, -0.22) shed 1.4%. JPMorgan Chase (JPM 41.62, -0.48) reported earnings of $1.40 per share against expectations of $1.21. Meanwhile, its revenues were reported at $25.15 billion which was ahead of the expected $24.27 billion. The stock traded higher in initial response to the earnings report, but it settled lower by 1.1%.

Wells Fargo (WFC 34.25, -0.93) slid 2.6% after reporting mixed earnings. WFC exceeded earnings expectations by one cent, while its revenues fell $200 million short of analyst estimates.

Other major financials also showed weakness. Bank of America (BAC 9.12, -0.22) and Morgan Stanley (MS 17.31, -0.55) slipped 2.4% and 3.1%, respectively.

Consumer staple stocks were the top performers of the session. Within the space,Dean Foods (DF 14.94, +0.29) added 2.0% after Stifel Nicolaus upgraded the stock to ‘buy' from ‘hold' with an $18 price target.

Cigarette stocks also showing strength among defensive staple stocks. Philip Morris(PM 91.70, +0.86) and Altria (MO 33.12, +0.41) saw respective gains of 1.0% and 1.3%.

Elsewhere in the space, Monster Beverage (MNST 57.08, +2.64) advanced 4.9% in a rebound from recent weakness.

The Dow Jones Transportation Average outperformed the broader market and settled higher by 0.9%. JB Hunt (JBHT 58.37, +3.58) is the top performer within the space. The freight carrier settled higher by 6.5% after its mixed earnings report showed a top line beat and a slight bottom line miss. Meanwhile, peer CH Robinson (CHRW 59.94, +1.04) added 1.8%. With most transportation stocks on the rise, Overseas Shipholding Group (OSG 5.08, -0.80) was a notable laggard as the shipping stock tumbled 13.6%.

AMD (AMD 2.74, -0.46) slumped 14.4% after the company lowered its third quarter revenue guidance below consensus. Peer Intel (INTC 21.48, -0.20) settled lower by 0.9% while the Market Vectors Semiconductor ETF (SMH 30.50, -0.10) slipped 0.3%.

Overall producer prices rose during September by 1.1%, which was hotter than the 0.8% increase that had been widely forecast. Core producer prices were unchanged which was lower than the Briefing.com consensus call of a 0.2% increase.

The September Treasury Budget showed a $75 billion surplus, which was in-line with expectations.

Next week, the earnings season enters full force as more than 230 companies are scheduled to report their third quarter results.

On Monday, September retail sales, retail sales ex-auto, and the October Empire Manufacturing Index will all be reported at 8:30 ET. In addition, August business inventories will be released at 10:00 ET.

Weekly Review: Markets Cautious Ahead of Third Quarter Earnings

On Monday, equities began the day on a negative note after the World Bank cut its growth projections for the Asian region. Lacking an additional catalyst, the key indices spent the majority of the session trading near their opening levels. A late-day buying surge briefly lifted the S&P 500 and Dow to their session highs, but the bulk of the move was promptly retraced. As a result, the S&P 500 shed 0.3% and the Nasdaq ended with a loss of 0.8%. Marathon Petroleum (MPC 54.30, -0.36) advanced 5.4% after announcing the purchase of BP's Texas City Refinery, related logistics, and marketing assets.

Tuesday's session began on a mixed note before a broad sell-off sent the major averages to their session lows. The weakness started in the technology sector where a slew of companies lowered their third quarter guidance. After reaching their worst levels of the day, the key indices traded sideways until late-day selling coincided with reports the U.S. Attorney in Manhattan filed a civil mortgage fraud lawsuit againstWells Fargo (WFC 34.25, -0.93). The company has since come out and denied any wrongdoing. As a result, the S&P 500 fell 1.0% while the Nasdaq underperformed with a loss of 1.5%.

Wednesday's session got off to a mixed start as the key indices chopped around their respective unchanged lines during the first hour. Sellers took control after traders digested the wholesale inventories data, pushing the major averages to their worst levels. Afternoon trade was mostly quiet as the three averages hovered near session lows. As a result, the S&P 500 finished lower by 0.6%. Alcoa (AA 8.69, -0.08) dipped 4.6% after beating on earnings and revenues. However, the company's third quarter revenue of $5.833 billion represents a 9.1% year-over-year decrease.

On Thursday, equities began the session on a positive note after the weekly initial claims were reported at their lowest level since January 2008. However, the reading of 339,000 may not be entirely comparable to the prior period as one unidentified large state was not included in the total. The early bullish sentiment failed to hold as the major averages reversed during the first hour, and headed for the flat line. As a result, the S&P 500 ended flat. Alpha Natural Resources (ANR 7.88, -0.67) and Arch Coal(ACI 7.62, -0.32) both surged near 16.0%. ..NYSE Adv/Dec 1075/1894. ..NASDAQ Adv/Dec 826/1616.


Commodities


Copper, Silver and Platinum shed more than 1% for the precious metals... While the agriculture commodities were down a lot... with Wheat down 3%, soybean down 1.65% etc... that doesn't look good... There will be a agriculture and wheat report coming out on Monday, so I suppose the market is pricing in for these agriculture commodities...

Treasuries

Treasuries went up!


Weekly Analysis
Week 38


Technical Updates


On a weekly view, both DOW and SPX is holding at their support while NASDAQ is making some moves down...


Commentaries

Weekly Wrap 
Dow +2.46 at 13328.85, Nasdaq -5.30 at 3044.11, S&P -4.25 at 1428.59
Today's session got off to a quiet start. The major averages held near their opening levels until the preliminary October University of Michigan Consumer Sentiment Survey registered a reading of 83.1. The survey's best level since September 2007 lifted the major averages to their session highs. However, the exuberance was short-lived as the key indices promptly fell through the unchanged line, to their session lows. The afternoon was generally quiet as the S&P 500 hovered within points of the 1,428 level before settling at 1,428.59, with a loss of 0.3%. Note that today's session punctuated a down week, during which the S&P 500 lost 2.2%. 
The financial sector was the biggest laggard of the day. Despite record earnings from two major names, the SPDR Financial Select Sector ETF (XLF 15.81, -0.22) shed 1.4%. JPMorgan Chase (JPM 41.62, -0.48) reported earnings of $1.40 per share against expectations of $1.21. Meanwhile, its revenues were reported at $25.15 billion which was ahead of the expected $24.27 billion. The stock traded higher in initial response to the earnings report, but it settled lower by 1.1%.
Wells Fargo (WFC 34.25, -0.93) slid 2.6% after reporting mixed earnings. WFC exceeded earnings expectations by one cent, while its revenues fell $200 million short of analyst estimates. 
Other major financials also showed weakness. Bank of America (BAC 9.12, -0.22) and Morgan Stanley (MS 17.31, -0.55) slipped 2.4% and 3.1%, respectively. 
Consumer staple stocks were the top performers of the session. Within the space, Dean Foods (DF 14.94, +0.29) added 2.0% after Stifel Nicolaus upgraded the stock to ‘buy' from ‘hold' with an $18 price target.
Cigarette stocks also showing strength among defensive staple stocks. Philip Morris (PM 91.70, +0.86) and Altria (MO 33.12, +0.41) saw respective gains of 1.0% and 1.3%.
Elsewhere in the space, Monster Beverage (MNST 57.08, +2.64) advanced 4.9% in a rebound from recent weakness.
The Dow Jones Transportation Average outperformed the broader market and settled higher by 0.9%. JB Hunt (JBHT 58.37, +3.58) is the top performer within the space. The freight carrier settled higher by 6.5% after its mixed earnings report showed a top line beat and a slight bottom line miss. Meanwhile, peer CH Robinson (CHRW 59.94, +1.04) added 1.8%. With most transportation stocks on the rise, Overseas Shipholding Group (OSG 5.08, -0.80) was a notable laggard as the shipping stock tumbled 13.6%.
AMD (AMD 2.74, -0.46) slumped 14.4% after the company lowered its third quarter revenue guidance below consensus. Peer Intel (INTC 21.48, -0.20) settled lower by 0.9% while the Market Vectors Semiconductor ETF (SMH 30.50, -0.10) slipped 0.3%.
Overall producer prices rose during September by 1.1%, which was hotter than the 0.8% increase that had been widely forecast. Core producer prices were unchanged which was lower than the Briefing.com consensus call of a 0.2% increase.
The September Treasury Budget showed a $75 billion surplus, which was in-line with expectations. 
Next week, the earnings season enters full force as more than 230 companies are scheduled to report their third quarter results. 
On Monday, September retail sales, retail sales ex-auto, and the October Empire Manufacturing Index will all be reported at 8:30 ET. In addition, August business inventories will be released at 10:00 ET. 
Weekly Review: Markets Cautious Ahead of Third Quarter Earnings 
On Monday, equities began the day on a negative note after the World Bank cut its growth projections for the Asian region. Lacking an additional catalyst, the key indices spent the majority of the session trading near their opening levels. A late-day buying surge briefly lifted the S&P 500 and Dow to their session highs, but the bulk of the move was promptly retraced. As a result, the S&P 500 shed 0.3% and the Nasdaq ended with a loss of 0.8%. Marathon Petroleum (MPC 54.30, -0.36) advanced 5.4% after announcing the purchase of BP's Texas City Refinery, related logistics, and marketing assets. 
Tuesday's session began on a mixed note before a broad sell-off sent the major averages to their session lows. The weakness started in the technology sector where a slew of companies lowered their third quarter guidance. After reaching their worst levels of the day, the key indices traded sideways until late-day selling coincided with reports the U.S. Attorney in Manhattan filed a civil mortgage fraud lawsuit against Wells Fargo (WFC 34.25, -0.93). The company has since come out and denied any wrongdoing. As a result, the S&P 500 fell 1.0% while the Nasdaq underperformed with a loss of 1.5%. 
Wednesday's session got off to a mixed start as the key indices chopped around their respective unchanged lines during the first hour. Sellers took control after traders digested the wholesale inventories data, pushing the major averages to their worst levels. Afternoon trade was mostly quiet as the three averages hovered near session lows. As a result, the S&P 500 finished lower by 0.6%. Alcoa (AA 8.69, -0.08) dipped 4.6% after beating on earnings and revenues. However, the company's third quarter revenue of $5.833 billion represents a 9.1% year-over-year decrease. 
On Thursday, equities began the session on a positive note after the weekly initial claims were reported at their lowest level since January 2008. However, the reading of 339,000 may not be entirely comparable to the prior period as one unidentified large state was not included in the total. The early bullish sentiment failed to hold as the major averages reversed during the first hour, and headed for the flat line. As a result, the S&P 500 ended flat. Alpha Natural Resources (ANR 7.88, -0.67) and Arch Coal (ACI 7.62, -0.32) both surged near 16.0%.


Next Week In View


There will be quite a bit of data coming out next week.. all we need is one bad report to sell the market off... but... it's gonna take a lot of good reports to hold the market above the support... Man... I'm waiting to short the market!

Market Call(Weekly): DOWN

Market Call(15 Oct 2012):Flat to upside
Date: 15 Oct 2012

Thursday, 11 October 2012

11 Oct 2012 AMC


11 Oct 2012
Market Summary 


Moving the Market 

Weekly initial claims: 339K actual versus 370K expected. Prior week revised to 369K
Continuing claims: 3.273 million versus 3.288 million prior
August trade deficit: $44.2 billion versus $43.6 billion expected. Prior revised to $42.5 billion
September export prices ex-agriculture: +0.7% actual versus +0.4% prior
September import prices ex-oil: +0.2% actual versus -0.2% prior

PPI (8:30): Briefing 0.5%, consensus 0.8%, prior 1.7%
Core PPI (8:30): Briefing 0.1%, consenus 0.2%, prior 0.2%
Michigan Sentiment (9:55): 80.0, consensus 78.5, prior 78.3
Treasury Budget (14): Briefing -$75.0B, consensus -$75.0B, prior -$62.8B
Oh well... I sort of got the direction right... but market just washed down after that despite all that gains... Luckily i took my profits at the opening bell... That clearly shows how much confidence the bulls have... I'm getting all ready to short already..


Market Internals


.

Despite the UVOL and TRIN showing you a bullish picture... the day was red in the market... 

Leaders and Laggards


Not much changes in the sectors but telco was the biggest laggard... On the side note, Sprint is talking to a Jap telco about some 'massive' investment, on a possible buyout.


Technical Updates


This is a very powerful dragonfly doji on all 3 indices....... aint looking good...


Commentaries 


Commodities


Natural Gas spiked.. a 3%.... only managed to catch a little of that trend...


Treasuries


On the treasuries, the 10 year and 30 year has been selling off... like i said the money is flowing out... somewhere...

Based on the economic report coming out on Friday, the Consumer Sentiment and PPI is going to be the mover..

However, given the fact that the bulls refuse to come in despite good economic report... This week is going to be a down week..


Market Call: DOWN
Date: 13 Oct 2012

Wednesday, 10 October 2012

10 Oct 2012

10 Oct 2012
Market Summary 


Whoa... the market went down more than I expected... so it seems that i'm kinda right isn't it! HAHA.

I suspect that this headline scares the shit of many people. Btw, there was a G7 meeting yesterday and came out with such headlines... that's not very promising.
IMF Sees ‘Alarmingly High’ Risk of Deeper Global Slump
A few days ago, there was a news paper article stating that Singapore may enter a technical recession. If the strongest economy in the ASEAN is facing such headlines... what do you think the entire region will face? You come up with your own conclusion...

What surprises me was VIX went down when the market went down.... that shows many players in the market... didn't bother hedging... but sold off straight again...


Market Internals


.
 Looking at that volume.... it's not a very high commitment day isn't it... the bulls aren't coming in... only the bears are in the game...

Leaders and Laggards


The main laggards are the materials and the energy sector... 

AA and CXV were the main laggards in the DOW and in their respective sectors. So I would say that the drop was not entirely in the broader market...


Technical Updates


On the DOW and SPX... some very scary is forming... the H & S... if these 2 indices don't hold that neckline.. we're going to see a correction before the presidential election! 

Commentaries 


Stock Market Update
16:15 ET Dow -128.56 at 13344.97, Nasdaq -13.24 at 3051.78, S&P -8.92 at 1432.56 :[BRIEFING.COM] Equities got off to a mixed start as the key indices chopped around their respective unchanged lines during the first hour. Sellers took control after traders digested the wholesale inventories data, pushing the major averages to their worst levels. Afternoon trade was mostly quiet as the three averages hovered near session lows. As a result, the S&P 500 finished lower by 0.6%. 

Earlier, the Federal Reserve released its September Beige Book. In its report, the twelve Federal Reserve Districts reported that economic activity "expanded modestly since the last report." Residential real estate conditions as well as the nonfinancial services sector also showed modest improvement. 

The manufacturing sector was described as mixed but somewhat healthier than what was observed in the last report. Meanwhile, the industrial market was also described as mixed. While the Philadelphia, New York, Cleveland, and Atlanta districts all showed strength, conditions in Richmond deteriorated slightly. The Beige Book also commented on consumer spending by saying it was mostly unchanged since the previous report. 

Financials registered the slimmest losses and the SPDR Financial Select Sector ETF(XLF 15.94, -0.01) shed 0.1%. Among the majors, Citigroup (C 35.14, +0.54) andJPMorgan Chase (JPM 41.77, +0.39) were the top performers. The two names registered respective gains of 1.6% and 0.9% after Bank of America/Merrill Lynch resumed coverage of the two stocks with a ‘buy' rating. Note that JPMorgan Chase will report its third quarter earnings before Friday's open. 

European financials saw mixed performance as Deutsche Bank (DB 41.17, +0.33) added 0.8% while Spanish Banco Bilbao Vizcaya Argentaria (BBVA 7.59, -0.10) slipped 1.3%. 

Energy stocks were the biggest laggard of the session. Chevron (CVX 112.45, -4.91) slid 4.2% after announcing that its third quarter earnings are expected to be substantially lower than results from the previous quarter. Penn Virginia (PVA 5.10, -0.39) andTesoro (TSO 38.70, -2.29) lost 7.1% and 5.6%, respectively. 

The Dow Jones Transportation Average outperformed the broader market with a gain of 0.1%. However, the strength was largely due to FedEx (FDX 89.52, +3.94). The bellwether stock gained 5.2% after announcing a program which targets $1.7 billion in annual profit improvements by the end of fiscal year 2016. In addition, the company reaffirmed its second quarter and full-year 2012 guidance which it had revised down on September 18. 

Elsewhere, Alcoa (AA 8.71, -0.42) dipped 4.6% after beating on earnings and revenues. However, the company's third quarter revenue of $5.833 billion represents a 9.1% year-over-year decrease. In addition, AA lowered its 2012 global aluminum demand growth forecast from 7.0% to 6.0%. 

Engine maker Cummins (CMI 87.79, -3.05) slid 3.4% after lowering its third quarter and full-year 2012 guidance due to weak demand. Caterpillar (CAT 83.16, -1.59) slipped 1.9% in sympathy. 

Ambarella (AMBA 6.06, +0.06) made its public debut today. The producer of video processing semiconductors priced its initial public offering at $6, which was well below the expected price range of $9 to $11. The stock settled higher by 1.0% after shares began trading at $6.66. 

August wholesale inventories increased by 0.5%. This was slightly lower than the increase of 0.6% which had been broadly forecast. 

Weekly initial and continuing jobless claims, August trade balance, September export prices ex-agriculture, and September import prices ex-oil will all be reported at 8:30 ET.

The U.S. Treasury will look to make it three strong auctions for the week with tomorrow's $13 billion, 30-yr reopening. ..NYSE Adv/Dec 1144/1890. ..NASDAQ Adv/Dec 1121/1337


After Hours
17:18 ET MSW +5.7%, RT -7.4%, PVTB -1.8% following earnings/guidance :
Equities got off to a mixed start as the key indices chopped around their respective unchanged lines during the first hour. Sellers took control after traders digested the wholesale inventories data, pushing the major averages to their worst levels. Afternoon trade was mostly quiet as the three averages hovered near session lows. As a result, the S&P 500 finished lower by 0.6%.
Today after the close the following companies are scheduled to report earnings: DRWI, PVTB, RELL, RT, VOXX, SCMR
Futures are lower after hours: S&P 500 futures are -3.74 from fair value of 1427.24 and Nasdaq100 futures are -4.47 from fair value of 2722.47.
Tomorrow morning before the open three economic reports are scheduled to be released: 1) Initial Claims (Consensus 370k) and Continuing Claims (Consensus 3275k), 2) Trade Balance (Consensus -43.8B) and 3) Export Prices ex-ag. and Import Prices ex-oil.
Tomorrow before the open the following companies are scheduled to report earnings: CMN, FAST, SWY, WGO


Commodities


Treasuries


Not much movement in the treasuries...

The only market mover is likely to be the trade balance and the unemployment claims today...


Market Call: FLAT(to upside)
Date: 10 Oct 2012

9 Oct 2012 AMC


9 Oct 2012
Market Summary 


Oh well... I was dead busy yesterday, and missed my DMA for 8 Oct... anyway... Yesterday was a down day... without much catalyst though. As what my mentor, Conrad says... the market do not need any catalyst to go down. 

DJI shed more than 110 points while the SPX shed around 12 points. Which is quite a down day. 


Market Internals


Judging by the internals, the market was bearish on the flatside. Not exactly a down day, just people taking off their profits.

Leaders and Laggards


The main laggards are the Consumer Dis, Tech, Industrials, Telco, then financials. Based on these, you can see that the main sectors are dragging the market down.


Technical Updates


On well... the main indices are correcting down and they are all hitting my trendlines...Each of them are breaking the 20SMA. I reckon there might a short term downtrend.

Commentaries 

Stock Market Update
16:15 ET Dow -110.12 at 13473.53, Nasdaq -47.33 at 3065.02, S&P -14.40 at 1441.48 : [BRIEFING.COM] Equities started the day on a mixed note before a broad sell-off sent the major averages to their session lows. The weakness started in the technology sector where a slew of companies lowered their third quarter guidance. After reaching their worst levels of the day, the key indices traded sideways until late day selling coincided with reports the U.S. Attorney in Manhattan filed a civil mortgage fraud lawsuit against Wells Fargo (WFC 35.12, -0.68). The company has since come out and denied any wrongdoing. As a result, the S&P 500 fell 1.0% while the Nasdaq underperformed with a loss of 1.5%.

The technology sector was the biggest laggard. Early weakness resulted from Apple(AAPL 635.85, -2.32) slipping as much as 2.0% intraday. However, shares of the tech giant proved to be resilient as the stock reversed and closed with a loss of 0.4%. Despite the intraday recovery in Apple, the rest of the technology sector was unable to reclaim its losses.

Technology bellwether Intel (INTC 21.90, -0.61) slipped 2.7% after Bernstein downgraded the stock from ‘market perform' to ‘underperform.' It should be noted that today's selling dropped Intel to its 52-week low.

Netflix (NFLX 65.52, -7.99) slid 10.9% after Bank of America/Merrill Lynch downgraded the stock from ‘buy' to ‘underperform' with a $72 price target. The downgrade resulted from valuation questions following the recent rally as well as concerns over the company's domestic streaming business and its international profitability. Today's selling follows yesterday's 10.0% rally which resulted from a Morgan Stanley upgrade.

VASCO Data (VDSI 7.34, -1.60) adds to the list of technology companies who cut their third quarter outlook. The stock sank 17.9% after the company lowered its third quarter and full-year 2012 guidance below consensus. The company commented on the lowered guidance by saying that "the lower than expected order intake in Q3 requires [the company] to lower [its] estimates of full-year revenue and related operating margins."

The energy sector was the top performer as crude oil advanced 3.3%. Within the complex, Gulfport Energy (GPOR 32.65, +2.22) gained 7.3% after reaffirming its 2012 guidance. The company continues to estimate 2012 production to range from 2.9 million to 3.1 million.

Coal stocks were broadly higher and the Market Vectors Coal ETF (KOL 24.35, +0.38) added 1.6%. Among individual coal producers, Alpha Natural Resources (ANR 7.28, +0.50) advanced 7.4% while CONSOL Energy (CNX 33.11, +1.38) and Peabody Energy (BTU 23.93, +1.29) saw gains between 4.3% and 5.7%.

Meanwhile, Penn Virginia (PVA 5.49, -1.04) fell 15.9% after announcing concurrent public offerings of 12 million shares of common stock and $50 million of depositary shares representing convertible preferred equity.

The Dow Jones Transportation Average slid 1.1% to break its recent streak of outperformance. Airlines were among the weakest components as they erased a portion of their recent gains. Delta Air Lines (DAL 9.89, -0.24) slipped 2.4%, whileAlaska Air (ALK 36.43, -0.52) and United Continental (UAL 20.49, -0.41) fell between 1.4% and 2.0%. Out of the twenty transportation stocks, only Matson (MATX 21.36, +0.38) advanced. Shares of the shipping company settled higher by 1.8%.

Chinese internet stocks were under pressure after Credit Suisse downgradedBaidu.com (BIDU 106.48, -7.80) from ‘neutral' to ‘underperform.' In addition, the price target was lowered from $118 to $83. As a result of the downgrade, Baidu.com slid 6.8%, and traded at levels last seen in early September.

Other Chinese internet names also declined in sympathy. SINA (SINA 60.36, -0.77),Sohu.com (SOHU 39.58, -1.12), and Youku Tudou (YOKU 19.16, -0.36) all registered losses between 1.2% and 2.8%.

Tomorrow, the MBA Mortgage Index will be reported at 7:00 ET. In addition, the September Treasury Budget and Federal Reserve's September Beige Book will be released at 14:00 ET.

The U.S. Treasury will hold a $21 billion, 10-yr reopening. ..NYSE Adv/Dec 694/2348. ..NASDAQ Adv/Dec 542/1935.

After Hours
16:28 ET YUM +3.5%, AA +0.7%, ESE -4.6% following earnings/guidance :
Equities started the day on a mixed note before a broad sell-off sent the major averages to their session lows. The weakness started in the technology sector where a slew of companies lowered their third quarter guidance. After reaching their worst levels of the day, the key indices traded sideways until late day selling coincided with reports the U.S. Attorney in Manhattan filed a civil mortgage fraud lawsuit against Wells Fargo (WFC 35.12, -0.68). The company has since come out and denied any wrongdoing. As a result, the S&P 500 fell 1.0% while the Nasdaq underperformed with a loss of 1.5%.
Today after the close the following companies are scheduled to report earnings: ADTN, AA, MG, YUM
Futures are lower after hours: S&P 500 futures are -0.22 from fair value of 1436.12 and Nasdaq100 futures are -1.65 from fair value of 2735.65.
Tomorrow morning before the open one economic report is scheduled to be released: 1) MBA Mortgage Index.
Tomorrow before the open the following companies are scheduled to report earnings: COST, HELE, HST, PGR


Commodities


Not much movements in commodities.


Treasuries


Whoa.... Another Sell off in bonds again.... Something is happening in the market....Bonds have been selling off recently...


There's not much data coming out for the US today except Beige Book, while Aussie releases the employment change and unemployment rate.

Market Call: FLAT(to the downside
Date: 10 Oct 2012