Friday, 8 February 2013

7 Feb 2013 AMC

7 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
16:20 ET Dow -42.47 at 13944.05, Nasdaq -3.35 at 3165.13, S&P -2.73 at 1509.39 :[BRIEFING.COM] Equities ended the day with slim losses causing the S&P 500 to slip 0.2%. Though stocks saw little change at the outset of the session, sellers were able to take control within the first 30 minutes, and drive the major averages to their respective lows. 

The early broad-based weakness came about as the dollar index spiked to its highs in the 80.20 area. The sharp move took place after European Central Bank President Mario Draghi voiced concerns over the strength of the euro. The common currency weakened immediately following his remarks, falling to its session low near 1.3400 against the greenback. 

The morning dollar strength had a negative impact on commodities and commodity-related stocks. As such, the materials sector was pressured, and ended as the weakest performer today. The SPDR Materials Select Sector ETF (XLB 39.15, -0.21) shed 0.5%.

High-beta sectors underperformed for the duration of the day. Technology stocks lagged despite the outperformance from Apple (AAPL 468.22, +13.52). The largest tech stock saw intraday strength after activist investor, David Einhorn, said the company has a cash problem, thinking it can never have enough of it, and its preferred stock should yield 8.0%. Shares of Apple spiked to fresh highs in afternoon trade after the company responded to Mr. Einhorn's comments by saying it will "thoroughly evaluate" the proposal. 

Elsewhere in technology, microprocessor manufacturers lagged as disappointing earnings from Peregrine Semiconductor (PSMI 9.41, -1.57) weighed. The broader PHLX Semiconductor Index ended lower by 0.6%. 

In notable tech earnings, Akamai Technologies (AKAM 35.26, -6.32) plunged 15.2% after the company missed on the top line and issued cautious revenue guidance. 

Today, retailers reported their same store sales for the month of January. While most names reported results ahead of the Retail Metrics consensus, their stocks received a mixed investor response. The SPDR S&P Retail ETF (XRT 67.47, -0.31) settled lower by 0.5%. 

While retailers and discretionary stocks traded in-line with the broader market, consumer staples outperformed. The sector was the top advancer thanks to relative strength of cigarette producers. The largest industry component, Philip Morris (PM 89.82, +2.13), rose 2.4% after beating on earnings. 

Defensive-minded trade also favored the utilities sector which held slight gains throughout the day. Sector component Exelon (EXC 31.37, +0.39) added 1.3% despite guiding first quarter earnings below consensus. However, the electricity producer expects a better second half with full-year 2013 earnings in-line with analyst expectations. 

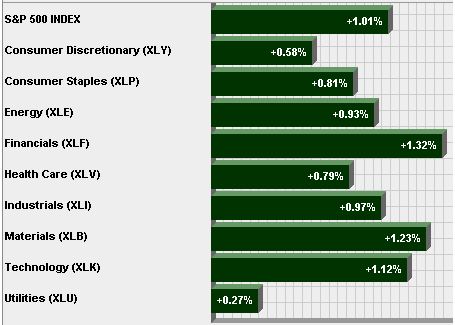
As mentioned earlier, the materials (-0.6%) sector was the weakest, followed by energy (-0.5%), financials (-0.4%), and telecoms (-0.4%). Meanwhile, consumer staples (+0.5%), and utilities (+0.2%) outperformed. 

Volume was below-average with just 664 million shares changing hands on the floor of the New York Stock Exchange. 

The day's economic data did little to influence the trading sentiment. Initial claims were reported at 366,000, which puts the figure right inside of last year's 350,000-400,000 range. 

Meanwhile, the 2.0% drop in fourth quarter productivity was the result of a very small increase in output (0.1%) combined with a solid increase in hours worked (2.2%). 

Lastly, unit labor costs increased 4.5% after declining 2.3% in the third quarter. That was the biggest increase in unit labor costs since increasing 6.4% in Q1 2012. 

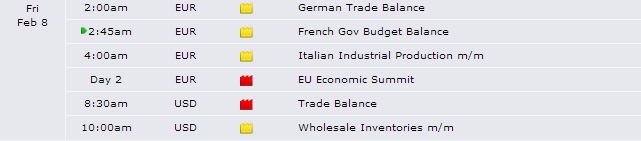
Tomorrow, the December trade balance will be reported at 8:30 ET while December wholesale inventories will be announced at 10:00 ET. Among notable earnings, CBOE Holdings (CBOE 34.30, +0.07) and Louisiana-Pacific (LPX 20.49, +0.25) will report their quarterly results ahead of the opening bell. ..NYSE Adv/Dec 1283/1706. ..NASDAQ Adv/Dec 934/1519.


After Hours
18:07 ET LNKD +10.0%, MOH +7.4%, NUAN -14.6%, RVBD -8.0%, CSTR -7.9% following earnings/guidance :
Equities ended the day with slim losses causing the S&P 500 to slip 0.2%. Though stocks saw little change at the outset of the session, sellers were able to take control within the first 30 minutes, and drive the major averages to their respective lows.
Other notable after hours movers on earnings: LNKD +10.0%, UBNT +8.9%, MOH +7.4%, MCHP +7.0%, FLT +7.0%, SNCR +5.9%, ATVI +5.4%, PAMT +3.7%, PRI +2.9%, AVNR +2.8%, NCR +2.5%, WWWW +2.4%, LCI +2.2%, BGC +2.0%, LFVN -17.0%, MSON -15.1%, NUAN -14.6%, RVBD -8.0%, CSTR -7.9%, SPWR -4.8%, UEPS -3.2%, COLM -2.6%, ECHO -2.6%, IMMU -1.7%, ENH -1.2%, GUID -1.0%, ATHN -1.0%
Today after the close the following companies reported earnings: ATHN, NCR, RVBD, HAS, MOH, AHL, OFG, AAN, ANH, COLM, CSTR, ECHO, IMI, RGC, SSD, WWWW, AGNC, LPS, ENH, G, MRH, AIV, ATR, CALD, CATM, DCT, FFG, GUID, HME, IMPV, KRG, LNKD, NFG, OPEN, PMC, RSG, SPWR, TSRA, ALNY, SLH, SNCR, XL, ATVI, PRI, RENT, EGOV, FLT, KMPR, MCHP, SQI, UBNT, UEPS, ESE, NUAN, ASYS, CENT, AVNR
Futures are lower after hours: S&P 500 futures are -0.62 from fair value of 1505.62 and Nasdaq100 futures are -0.34 from fair value of 2743.34.
Tomorrow morning before the open one economic report is scheduled to be released: 1) Trade Balance (Consensus -45.4B).
Tomorrow before the open the following companies are scheduled to report earnings: LH, SXT, CSL, IVC, OFC, AXL, ETM, MCO, BLC, NBIX, CBOE, FSTR, BPL, YRCW, ETR, AOL, GSM, LPX, APO, DWSN, SIRO, PSEC, BECN


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

Was right on the spot yesterday. The market went bananas after Draghi's speech, the market was down to the extent of more than 100 points, however fought back to close flat to the downside. Unemployment claims were below expectation. The internals were showing divergence all around the place. The market now is definitely confused and need a clear direction. However I am still firm on my stand the Feb will be very volatile towards the downside.


Market Call: DOWN
Date: 1 Jan 2013

Thursday, 7 February 2013

6 Feb 2013 AMC


6 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 

Stock Market Update
16:25 ET Dow +7.22 at 13986.52, Nasdaq -3.10 at 3168.48, S&P +0.83 at 1512.12 :[BRIEFING.COM] Equities ended little changed after spending the vast majority of today's session in the red. The major averages began the day on a cautious note as European indices retreated in anticipation of an update from Monte dei Paschi regarding the size of derivative-related losses suffered by the world's oldest bank. Recent reports have suggested the bank's losses will exceed the original estimate of EUR720 million. This caused selling of the Italian 10-yr as its yield climbed 13 basis points to 4.58%, its worst level since mid-December 2012.

The S&P 500 staged a morning recovery with the help of Apple (AAPL 457.35, -0.49). The largest tech stock spiked off its lows after rumors suggested the company may raise its quarterly dividend. However, with little substance behind the speculation, Apple followed the jump with a steady slide back near its flat line.

While tech shares displayed intraday strength, the discretionary sector hovered in the black throughout the session. Upbeat earnings from Polo Ralph Lauren (RL 174.63, +9.72) as well as Times Warner (TWX 52.01, +2.05) and Walt Disney (DIS 54.52, +0.23) supported the space. In addition, Chipotle Mexican Grill (CMG 322.46, +17.45) added 5.7% after reporting revenue in-line with its January 16 preannouncement.

Elsewhere, the materials sector outperformed the broader market thanks to the relative strength among steel producers. Reliance Steel (RS 70.25, +5.56) surged 5.9% following an agreement to acquire all outstanding shares of Metals USA (MUSA 20.65, +2.35) for $20.65 per share. The purchase price represents a 12.8% premium to Metals USA's Tuesday closing price, and the total transaction value is estimated at $1.2 billion. Meanwhile, the broader MarketVectors Steel ETF (SLX 49.38, +0.74) added 1.5%.

On the downside, the Dow Jones Transportation Average trailed behind the broader market. The bellwether complex shed 0.2% after CH Robinson (CHRW 60.50, -6.51) reported mixed earnings. The freight carrier fell 9.7%, and was the worst performer within the S&P 500.

Relative strength among airlines prevented transportation stocks from registering further losses. Alaska Air (ALK 47.42, +0.56) and United Continental (UAL 25.32, +1.06) saw respective gains of 1.2% and 4.4%. This morning, Alaska Air reported an 11.8% increase in traffic on a 12.2% rise in capacity, as compared to January 2012.

Today's trade was centered mostly around the unchanged line. Technology (-0.2%) and health care (-0.1%) sectors weighed on sentiment. Meanwhile, telecoms (+0.3%), utilities (+0.2%), materials (+0.2%), and consumer discretionary (+0.2%) shares outperformed.

The CBOE Volatility Index (VIX 13.42, -0.30) spent the bulk of the day in the black, but the near-term volatility measure turned lower into the close.

Volume was slightly below average as just over 680 million shares changed hands on the floor of the New York Stock Exchange.

Economic data was limited to the weekly MBA Mortgage Index, which rose 3.4% to follow last week's 8.1% decline.

Tomorrow, weekly initial and continuing claims as well as preliminary fourth quarter productivity and unit labor costs will all be reported at 8:30 ET. Finally, December consumer credit will be announced at 15:00 ET. Among notable earnings, Credit Suisse (CS 29.55, +0.22) and Sony (SNE 15.82, -0.01) are scheduled to report their results ahead of the opening bell. ..NYSE Adv/Dec 1767/1217. ..NASDAQ Adv/Dec 1335/1088.


After Hours
17:55 ET DV +11.8%, LF +5.6%, AKAM -16.4%, ADEP -9.5% following earnings/guidance :
Equities ended little changed after spending the vast majority of today's session in the red. The major averages began the day on a cautious note as European indices retreated in anticipation of an update from Monte dei Paschi regarding the size of derivative-related losses suffered by the world's oldest bank. Recent reports have suggested the bank's losses will exceed the original estimate of EUR720 million. This caused selling of the Italian 10-yr as its yield climbed 13 basis points to 4.58%, its worst level since mid-December 2012.
Other notable after hours movers on earnings: DV +11.8%, LF +5.6%, MPWR +5.5%, ZUMZ +5.2%, TRLG +4.7%, XIDE +4.4%, CBG +3.4%, GEOS +3.4%, EXP +2.7%, WGL +2.7%, AKAM -16.4%, ADEP -9.5%, IRBT -9.3%, PSMI -9.0%, GMCR -8.2%, OSUR -8.4%, TQNT -7.5%, ATML -4.1%, ARAY -3.9%
Today after the close the following companies reported earnings:  CVA, CYS, PTP, IRBT, AIZ, AKAM, ARRS, BDN, EFX, IACI, ORLY, RE, SGMO, SRCL, TQNT, TYL, XXIA, CINF, DV, SPSC, EXP, FMC, RLD, CBG, FEIC, GPRE, QUIK, ALL, CNW, HOS, KEYW, PRE, PSMI, RRTS, SWM, TSO, V, ABCO, ATML, CEB, DRIV, FORM, LNC, MAA, MPWR, MTD, RNR, SWIR, WMS, YELP, AGII, ANDE, CBM, ENS, LF, PAA, PNG, SREV, TRLG, GCOM, NWSA, PL, TWO, VSAT, ARAY, ATO, GHDX, HIMX, OSUR, PRU, UHAL, ARX, MTRX, XIDE, NTES, SPB, WGL, GMCR, GIL, GEOS, ADEP, PDH
Futures are lower after hours: S&P 500 futures are -1.00 from fair value of 1507.90 and Nasdaq100 futures are -1.04 from fair value of 2741.29.
Tomorrow morning before the open three economic reports are scheduled to be released: 1) Initial Claims (Consensus 360k) and Continuing Claims (Consensus 3200k), 2) Productivity-Prel (Consensus -1.2%), and 3) Unit Labor Costs (Consensus 2.4%).
Tomorrow before the open the following companies are scheduled to report earnings:  HLSS, HWAY, SNA, SIAL, BG, CCE, CLI, CS, FLIR, GPK, HOT, INGR, LAZ, MNI, NBL, NYT, ODFL, PACR, PMTI, PTEN, RTIX, S, SQNS, KKR, MPW, ARW, GLT, CI, EXC, GTIV , HPY, ONNN, PBH, SNE, SNI, TDC, TEVA, XYL, ALU, IT, NPO, OZM, ROLL, NNN, BR, IFF, MMYT, MSCI, TW, CTSH, AAP, BDC, MFC, MWW, PMFG, PMT, RSTI, THR, FLO, MMS, SBH, POST, SPH, GBDC


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

Market was within expectation and moved sideways, not much market moving factors yesterday. The market was apparently lacking something to give them a direction. Thursday we're going to have some news coming out from Europe that might gyrate the market quite a bit. As for the internals, we're looking at some bullish internals with volumes trading up to 680m shares in the NYSE. Internals were all pointing at the bullish bias. However, we saw some bond rates going down which is causing some divergence in the market. Especially we're at a flat month, and at the high of the market right now, I rather be cautious and mild bearish in the near term now.


Market Call: FLAT to downside
Date: 6 Jan 2013

Tuesday, 5 February 2013

5 Feb 2013 AMC

5 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
16:15 ET Dow +99.22 at 13979.3, Nasdaq +40.41 at 3171.58, S&P +15.58 at 1511.29 :[BRIEFING.COM] Today's session brought resilience to the markets as the key averages recovered the majority of their losses from Monday. The S&P 500 settled higher by 1.0% after spending the duration of the day in a steady climb. The morning sentiment was aided by upbeat European trade where Italian and Spanish markets recovered from yesterday's plunge. 

Domestically, seven of ten S&P 500 sectors registered gains in the neighborhood of 1.0%. Tech shares led the way after the sector felt the brunt of Monday's selling. The largest tech stock, Apple (AAPL 457.84, +15.53), outperformed the broader market and ended higher by 3.5%. 

The tech sector received some acquisition news today. Dell (DELL 13.42, +0.15) added 1.1% after entering into an agreement to be acquired by Michael Dell-Silver Lake for $13.65 per share. The deal includes a $2 billion loan from Microsoft (MSFT 27.50, +0.05). 

Meanwhile, Virgin Media (VMED 45.61, +6.92) jumped 17.9% after the company confirmed its discussions with Liberty Global (LBTYA 67.88, -1.58) regarding a possible transaction. 

Among notable tech earnings, ARM Holdings (ARMH 43.69, +1.74) gained 4.2% after beating on revenue. Meanwhile, the broader PHLX Semiconductor Index advanced 1.6%. 

In other earnings of note, Archer-Daniel Midlands (ADM 29.38, +0.94) beat on earnings and revenue while Kellogg (K 58.50, +0.40) topped the Capital IQ revenue forecast. The two stocks supported the consumer staples sector, and ended with respective gains of 3.3% and 0.7%. 

While staple stocks saw strength across the board, the discretionary sector experienced some pockets of weakness. Restaurant operator Yum! Brands (YUM 62.08, -1.86) shed 2.9% after its quarterly report included cautious guidance. This comes as the company attempts to overcome the negative publicity received after two poultry suppliers provided KFC with chicken containing unapproved antibiotic levels. 

Publisher McGraw-Hill (MHP 44.92, -5.38) was another notable laggard in the discretionary space. Shares of the publishing company plunged after the Department of Justice announced plans to file a civil lawsuit against Standard & Poor's, a unit of McGraw-Hill. The Department of Justice is alleging S&P knowingly defrauded investors with its ratings on collateralized debt obligations and mortgage backed securities. McGraw-Hill is down over 20.0% since the charges were announced. 

The CBOE Volatility Index (VIX 13.73, -0.94) declined over the course of the session and shed over 7.0%. The near-term volatility measure ended the session at its 20-day average. 

Floor volume at the New York Stock Exchange was slightly below average as 702 million shares changed hands over the course of the day. 

Today's economic data had little trading impact as the January ISM Services Index was reported at 55.2, which fell short of the 55.6 forecast by the Briefing.com consensus. 

Tomorrow, the weekly MBA Mortgage Index will be reported at 7:00 ET. In notable earnings, CVS Caremark (CVS 51.72, +0.72) and Kraft Foods (KRFT 47.02, +0.62) will report their quarterly results ahead of the opening bell. ..NYSE Adv/Dec 2199/810. ..NASDAQ Adv/Dec 1809/683.


After Hours
18:15 ET SFLY +14.0%, CSGS +12.6%, PIKE +10.3%, VTSS -5.2%, USNA -5.0% following earnings/guidance :
Today's session brought resilience to the markets as the key averages recovered the majority of their losses from Monday. The S&P 500 settled higher by 1.0% after spending the duration of the day in a steady climb. The morning sentiment was aided by upbeat European trade where Italian and Spanish markets recovered from yesterday's plunge.

Other notable after hours movers on earnings: SFLY +14.0%, CSGS +12.6%, PIKE +10.3%, TTWO +7.0%, ZNGA +5.8%, SIMG +5.9%, CERN +5.7%, EXPE +4.5%, PNRA +3.9%, DIS +2.7%, MYGN +1.3%, PACB +1.3%, UUV +0.6%, VTSS -5.2%, USNA -5.0%, GLUU -4.7%, HAIN -4.1%, TTMI -3.9%, CME -3.7%, NOA -2.4%, JIVE -1.7%, GNW -1.6%, CHRW -1.6%, MWA -1.5%, AFL -1.5%, HMN -1.2%, INFN -1.2%, CSCD -1.1%, ULTI -0.8%

Today after the close the following companies reported earnings: STLY, HNI, CMG, VASC, AFL, CHRW, CPTS, HBI, PNRA, USNA, ENTR, EQR, HMN, INFN, ZNGA, CALX, CERN, CME, EXPE, KFN, PACB, MXL, CSGS, FISV, GNW, KFRC, KIM, MWA, SIMG, ULTI, JKHY, NOA, TMH, TTWO, UNM, WNC, BMR, GLUU, HAIN, SFLY, SU, THOR, TRMB, JIVE, MYGN, NSR, PIKE, CBL, MEAS, DIS, POWL

Futures are mixed after hours: S&P 500 futures are -0.50 from fair value of 1506.9 and Nasdaq100 futures are +1.47 from fair value of 2749.78.
Tomorrow morning before the open three economic reports are scheduled to be released: 1) Initial Claims (Consensus 360k) and Continuing Claims (Consensus 3200k), 2) Productivity-Prel (Consensus -1.2%), and 3) Unit Labor Costs (Consensus 2.4%).

Tomorrow before the open the following companies are scheduled to report earnings: USG, VMED, PLD, ATMI, DFT, ELN, TBI, CFX, CVH, CMP, IVR, MT, ASCA, CMI, GTS, LPLA, MAC, NUS, RTI, STE, WXS, ABMD, GAS, SBGI, MSG, PAG, RL, ICE, CVS, MRO, CGX, CSTE, MPEL, TWX, VICL, AINV, ARX, SMG, MGI


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

Didn't manage to do my DMA yesterday. Monday was a sudden bearish day after digesting the news from last week. NFP and Advance GDP showing slowing down in economy. However, Tuesday staged a sharp rebound. Internals are showing bullish strength with trading volumes slightly above average of 700 million shares on the NYSE. The 10y and 30y had some slight movement in that bullish market yesterday. With the most sectors performing more than 1%, it does show the bullish sentiment in the market. However, I do think that market will definitely retrace before it breaks into higher high.


Market Call: Flat to downside
Date: 5 Jan 2013

Sunday, 3 February 2013

1 Feb 2013 AMC


1 Feb 2013 AMC
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Commentaries 


Stock Market Update
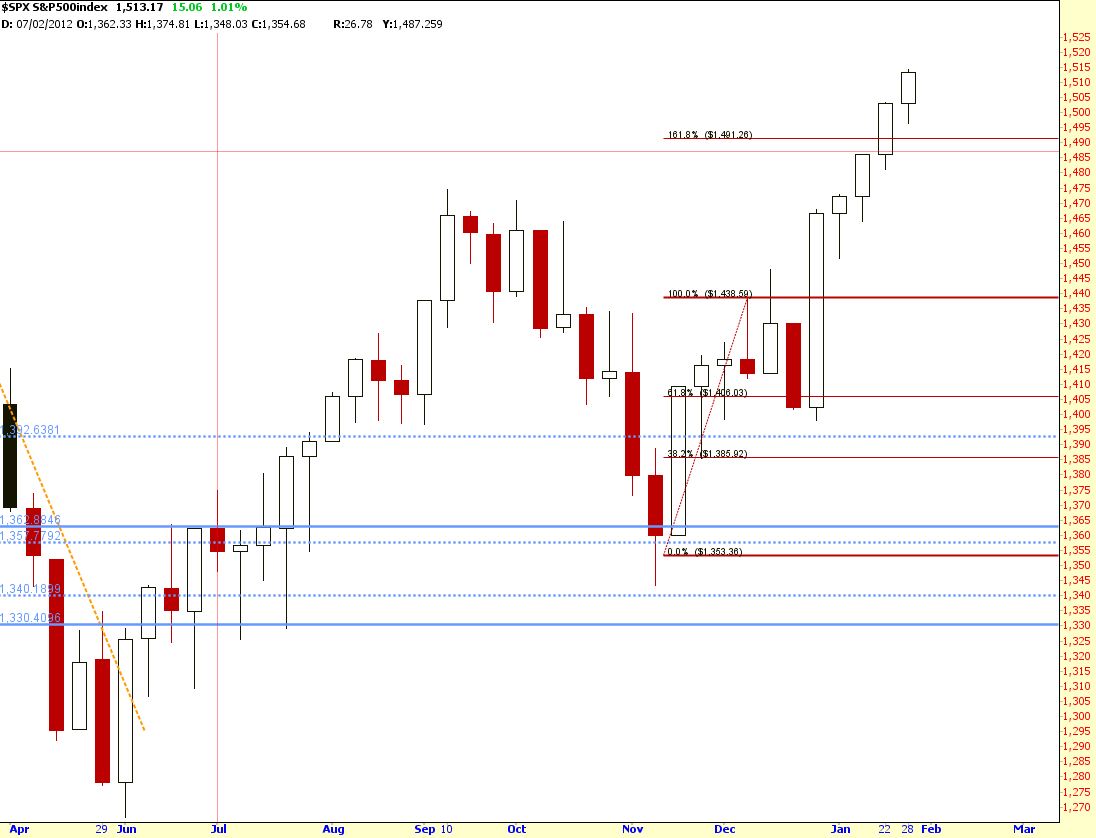
16:25 ET Dow +149.21 at 14009.79, Nasdaq +36.97 at 3179.1, S&P +15.06 at 1513.17 : [BRIEFING.COM] Stocks saw broad gains during today's session and the S&P 500 ended higher by 1.0%. Meanwhile, the Dow climbed 1.1% and settled above 14,000 for the first time since October 2007. The day was busy with economic data, most of which surprised to the upside. Overseas, China's HSBC manufacturing PMI signaled continued expansion while readings in Europe were better-than-feared. 

Domestically, investors received a full slate of data with the headline report coming in the form of January nonfarm payrolls. During the first month of 2013, the economy added 157,000 nonfarm jobs, which fell short of the 180,000 expected by the Briefing.com consensus. In addition, the unemployment rate ticked up to 7.9%. The immediate reaction sent equity futures higher as the rise in unemployment signals the Federal Reserve will not be removing its support from the markets in the near future. 

The morning sentiment was aided by a strong January ISM index, upbeat December construction spending, as well as the positive revision to the final January Michigan Consumer Sentiment Survey. 

All ten S&P 500 sectors ended in the black and five added at least 1.0%. 

Financials rallied broadly and the SPDR Financial Select Sector ETF (XLF 17.61, +0.23) notched a fresh 52-week high. Bank of America (BAC 11.71, +0.39) and Morgan Stanley (MS 23.51, +0.71) outperformed their peers and settled with respective gains of 3.5% and 3.1%. 

Elsewhere, the materials sector rallied on the strength of steel producers. The industry tends to show elevated sensitivity to Chinese economic data, and today's manufacturing PMI beat suggested Chinese steel demand will remain strong. The Market Vectors Steel ETF (SLX 49.61, +0.77) advanced 1.6%. 

The tech sector underperformed earlier in the week, but did its best to catch up to the broader market today. Interestingly, technology stocks rallied without the participation ofApple (AAPL 453.62, -1.87). However, microprocessor manufacturers picked up the slack and the PHLX Semiconductor Index gained 1.9%. 

The CBOE Volatility Index (VIX 12.92, -1.36) fell almost 10.0%, and ended near its 52-week low of 12.29. 

Today's volume was strong with more than 750 million shares changing hands on the floor of the New York Stock Exchange. 

Next week shapes up to be pretty light in terms of economic data. On Monday, December factory orders will be reported at 10:00 ET. 
Commodities


Treasuries


Weekly Analysis
Week 38


Technical Updates


Briefing's Commentaries

Weekly Wrap 

Week in Review: Equities Book Solid January Gains
On Monday, the major averages ended the session largely where they began. The S&P 500 and Dow registered modest losses, while the Nasdaq added 0.2%, seeing relative outperformance from Apple (AAPL 453.62). The largest tech stock ended higher by 2.3% after disappointing earnings caused it to lose nearly 13.0% last week. The materials sector was the weakest performer. The observed weakness resulted from a Goldman Sachs downgrade of the U.S. steel sector. Following the downgrade, steel stocks saw broad selling and the Market Vectors Steel ETF (SLX 49.62) shed 1.4%.
Equities finished Tuesday's session on a mixed note. The Dow and S&P 500 gained 0.5% each, while the Nasdaq underperformed and ended flat. However, looking below the surface revealed the sector rotation which took place today. Health care, telecoms, and utilities were among the day's top performers as investors rotated into defensive-oriented stocks. Seagate (STX 33.67, -0.31) fell 9.4% after issuing guidance which disappointed investors. The sell-off occurred after Seagate rallied nearly 50.0% in the eight weeks leading up to its quarterly report.

On Wednesday, equities started the day on a mixed note, but the slightly bearish bias which persisted throughout the session caused the major averages to end near their lows. The S&P 500 slipped 0.4%, and was the weakest performing index. Amazon.com (AMZN 265.00, -0.50) jumped 4.8% after the online merchant reported its operating income well ahead of analyst expectations.

Thursday did not bring much change to the market as the S&P 500 slipped 0.3% and Nasdaq ended flat. Mixed trade unfolded amid economic data which was largely in-line with expectations. The personal income report stood out as the December increase of 2.6% was well ahead of the 0.7% rise expected by the Briefing.com consensus. However, the notable rise in personal income was due to a surge in personal income on assets as investors chose to lock in a lower capital gains tax rate ahead of the New Year. In addition to economic data, investors received several notable earnings reports. Ryder System (R 57.90, +1.12), MasterCard (MA 518.71, +0.31), and Qualcomm (QCOM 66.73, +0.71) gained between 0.5% and 4.6% after beating on earnings.

Month in Review: Equities Soar as Full Force of 'Fiscal Cliff' Averted
Responding favorably to the Congressional compromise on tax rates, the S&P 500 jumped 2.8% in the first week of 2013 and rarely looked back. Despite some mixed economic and earnings news along the way, the S&P 500 closed with a gain in 13 out of 21 sessions and ended January at 1498.27 its best level since December 2007. The Dow Jones Industrial Average for its part surged 5.8% and recorded its best January since 1989. 
Economic Data Paints Bleak January Picture
The bulk of economic data reported during the month beat the Briefing.com consensus. However, data reported for the month of January often came up short. 
Of the seven January reports, five fell short of expectations. 
  • The Empire Manufacturing Index, NAHB Housing Index, Philadelphia Fed Survey, Michigan Sentiment, and Consumer Confidence reports all missed expectations.
  • Meanwhile, the ADP Employment Change and Chicago PMI surprised to the upside.
The advance fourth quarter GDP reading was a headline disappointment, as a 0.1% contraction was recorded for the final quarter of 2012. However, the report was not as weak as it appeared. 
  • The biggest drag on quarterly growth came in the form of a 6.6% decrease in government spending. This was largely due to a 22.2% decline in defense spending which followed a 12.9% increase during the third quarter. 
  • The change in private inventories also subtracted 1.27 percentage points from the change in real GDP. 
  • Personal consumption expenditures, which constitute more than 70% of GDP, rose 2.2%, which was the largest increase since the first quarter of 2012. 
  • Business investment rose 12.4%, which was the largest uptick since the third quarter of 2011.
Mixed Earnings Unable to Derail Rally
The second half of the month saw the start of the fourth quarter earnings season. 
  • Most companies have beaten on the bottom line per usual, hurdling estimates that had been lowered in many cases by analysts ahead of the reports. Revenue growth is still weak, but similar to earnings, most companies have exceeded depressed top line growth estimates. 
  • Cautious guidance has been a common theme as many companies see headwinds in the first half of the year, although the default opinion is that the second half of the year should look better.
Transports, Energy, Health Care, and Discretionary Stocks Paced the Gains
The Dow Jones Transportation Average gained 9.4% as truckers and railroads joined the rally enjoyed by airlines since mid-November. 
Energy stocks also displayed relative strength and the SPDR Energy Select Sector ETF (XLE) advanced 8.3%. This was largely supported by a 6.2% rise in the price of crude oil. The energy component ended the month just a shade under $98. 
The Health Care sector has been a standout, trailing behind only energy in the sector rankings on a year-to-date basis (+7.4%).
The discretionary sector has also been among the top performers in the S&P 500. 
  • Homebuilders continued their strength from 2012. The SPDR S&P Homebuilders ETF (XHB) ended January with a gain of 8.3%. Many builders reported strong fourth quarter earnings, replete with reports of strong backlogs and order trends.
Technology Lagged as Apple Weighed 

The tech-heavy Nasdaq underperformed the remaining major indices as Apple (AAPL), which is the single largest index component, continued displaying weakness. 
  • Shares of Apple sold off through the first half of the month before pausing near the $500 level. 
  • A disappointing January 23 earnings report caused the stock to lose more than 10%. The company fell short of revenue expectations and issued downside guidance. 
  • The largest tech stock ended the month down 14.4%, at levels last seen in February 2002. 
Excluding Apple, the technology sector fared relatively well. Semiconductors outperformed despite a rash of disappointing earnings reports and outlooks. The PHLX Semiconductor Index climbed 7.7%.
Defensive Stocks Bid into Second Half
During the second half of the month, defensive-oriented sectors started to attract increased buying interest. 
  • Telecoms (+1.8%) and utilities (+4.5%) registered the bulk of their gains during the second half of the month after the broader market had already seen the majority of its rise. 
  • Health care stocks enjoyed strength throughout the month as upbeat earnings supported the space.
Headwinds Remain as S&P 500 Nears Uncharted Territory
As the S&P 500 hovers just 4.3% below its all-time high, challenges remain visible. 
  • A notable drop in consumer confidence occurred as the initial impact of the payroll tax cut expiration was felt by income earners. 
  • Sequester cuts are scheduled to go into effect in March, with the brunt of the impact to be absorbed by the defense sector. 
  • The debt ceiling issue has only been deferred rather than fixed. 
  • Japan's bold bid to weaken its currency and to inflate its economy is raising the risk of currency wars as other countries aim to support their exporters. 
  • Geopolitical issues are simmering, with conflicts in the Middle East starting to make headline waves (eg. Egypt, Israel/Syria/Iran) and North Korea toying with nuclear tests. 
  • Rising interest rates threaten to slow the housing recovery. 
  • Bullish sentiment, which is a contrarian indicator, is picking up noticeably.


Next Week In View


Jason's Commentaries

This is the best January the market has ever had since 1989. Market rallied all the way and broke the 14 000 mark on the first day of Feb. As history as shown, whenever the market crashes and recover, it will tend to break the previous high and it has been very reliable.

On Friday, we saw some disappointing numbers at the Non-farm Payrolls but surprisingly, it did not managed to drag the market down, while the ISM report showed some positive results to assist in its gains. Out of the 9 Sectors, 4 out of the 9 sectors made more than 1% gain, and industrials were almost gaining 1%. However, on the side note, out of 7 economic report in Jan, 5 showed poor results. It seems that market doesn't really care about the reports for Jan, but I'm sure that those will definitely weight on Feb's gain. Friday is definitely a strong bull day, with more than 700m shares traded in the NYSE and all the internals pointing to a bullish bias. Right now, it's only the industrials and the Tech within the 9 sectors that are not leading right now, which is not a very good thing. I believe Feb will be very volatile as the strong stocks might not be gaining much. Right now, the market is betting on a housing recovery, but the FOMC statement signaled there might be a bond bubble going on... HELLO... we talked about it long time back...

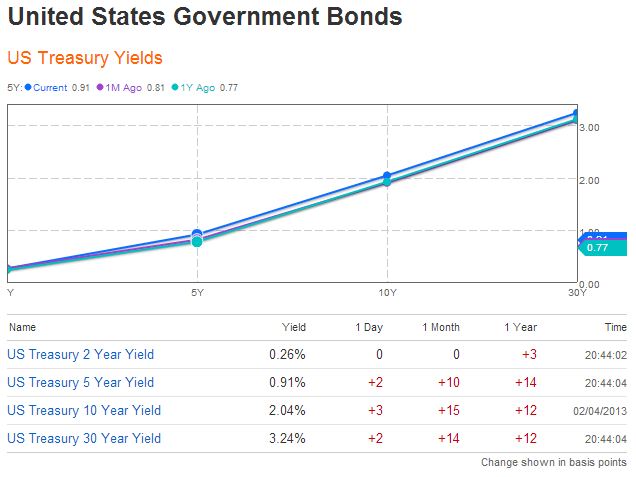
Treasuries rates have been pushed to a low since the subprime, and volumes in the equities market was nothing like before. Where has all the money gone to? Overseas and the Bond Market. Bond usually trap cash for a long period of time, and in anticipation of the Financial crisis, people are pushing money into low risk assets which locked the cash for a long time. This causes liquidity problem. And right now, bond has been selling down, looking at volumes returning to approx an average of 700m, it's good... but it looks like 2007 all over again.

In the first week of Feb, we don't have much reports coming out except for a major report coming out from the ECB. I believe the first week of Feb will likely to be flat and it's gonna be volatile, especially we're still in the earnings period and we're at the all time high at the market.


Market Call: Flat to downside
Market Call(Weekly): Flat to downside
Date: 4 Feb 2013