Wednesday, 13 February 2013

12 Feb 2013 AMC

12 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
16:25 ET Dow +47.46 at 14018.7, Nasdaq -5.51 at 3186.49, S&P +2.42 at 1519.43 :[BRIEFING.COM] Equities finished the day on a mixed note. The Dow climbed 0.3% and registered its highest close of the year while the S&P 500 added 0.2%, and Nasdaq shed 0.2%. The day got off to a slow start as the major averages spent the entire morning near their respective unchanged levels. However, key indices were able to climb to their highs in afternoon trade as financials paced the advance. 

The financial sector led throughout the session, and the S&P 500 Financials Index climbed above 240 for the first time since October 2008. Bank of America (BAC 12.24, +0.38) and Citigroup (C 44.35, +1.20) both gained near 3.0% to support the space. 

While financials led throughout the session, defensively-oriented telecommunication stocks spent the day in an upward climb and ended as the second best performing sector. 

With no market-moving economic data, traders turned to earnings as several consumer names reported their quarterly results. The discretionary sector outperformed after market participants responded favorably to earnings from Fossil (FOSL 110.65, +3.19) and Michael Kors (KORS 62.00, +5.00). Fossil advanced 3.0% after reporting in-line earnings on better-than-expected revenue. Meanwhile, the company's guidance reflected a recent pattern. Fossil warned against a slowdown in the first quarter, but left its full-year guidance intact. This indicates the company believes the latter part of the year will make up for expected first quarter softness. 

Elsewhere, Michael Kors spiked 8.8% after its earnings came in well ahead of expectations. 

The discretionary space was supported by upbeat earnings, but quarterly results had the opposite effect on consumer staples. Coca-Cola (KO 37.56, -1.05) settled lower by 2.7% after the beverage giant warned against continued global uncertainty. 

As consumer staples held slim losses throughout the day, afternoon trade saw relative weakness from technology stocks. The space was pressured by Apple (AAPL 467.90, -12.03), which lost 2.5%, after Chief Executive Officer Tim Cook did not hint at near-term changes to the company's dividend policy. Elsewhere, Qualcomm (QCOM 65.88, -1.30) dropped 1.9% after JPMorgan Chase downgraded the stock to ‘Neutral' from ‘Overweight.'

Today's floor volume represented a marked improvement over yesterday's session, but it remained well below average as just over 610 million shares changed hands. 

Looking at the S&P 500 sector breakdown, financials (+0.8%) and telecoms (+0.6%) were the clear leaders while technology (-0.5%), health care (-0.2%), and consumer staples (-0.1%) brought up the rear. 

Overseas, world leaders are preparing for the G20 summit scheduled to take place in St. Petersburg later this week. Reports from the meetings will be closely watched as recent months have seen a rise in currency commentary. With Japan taking active efforts to weaken the yen and daily remarks from European officials suggesting what the "right" level for the euro should be, the summit is likely to produce some noteworthy quotes. 

Investors received just one economic report today and it came in the form of the January Treasury budget. This report pointed to a surplus of $2.88 billion, which was better than the deficit of $2.0 billion expected by the Briefing.com consensus. 

Note that President Barack Obama will give the first State of the Union address of his second term at 21:00 ET tonight. 

Looking at tomorrow's economic data, weekly MBA Mortgage Index will be reported at 7:00 ET. At 8:30 ET January retail sales, retail sales ex-auto, export prices ex-agriculture, and import prices ex-oil will all be released. Lastly, December business inventories will be announced at 10:00 ET. In notable earnings, Comcast (CMCSA 38.97, +0.33) and Deere (DE 93.97, +0.74) will report their quarterly results prior to the opening bell. 

The U.S. Treasury will auction off $24 billion in 10-yr notes. ..NYSE Adv/Dec 1935/1054. ..NASDAQ Adv/Dec 1517/949.


After Hours
18:27 ET TRLA +13.5%, RPXC +12.3%, KOOL +8.2%, RATE -20.4%, RAX -9.6%, CLF -9.6% following earnings/guidance :
Equities finished the day on a mixed note. The Dow climbed 0.3% and registered its highest close of the year while the S&P 500 added 0.2%, and Nasdaq shed 0.2%. The day got off to a slow start as the major averages spent the entire morning near their respective unchanged levels. However, key indices were able to climb to their highs in afternoon trade as financials paced the advance.

Other notable after hours movers on earnings: TRLA +13.5%, RPXC +12.3%, KOOL +8.2%, CMCSA +6.2%, SAPE +3.4%, VMI +2.5%, QLTY +2.0%, HTS +0.7%, WSH +0.4%, FTI +0.3%, RUSHA +0.1%, RATE -20.4%, RAX -9.6%, CLF -9.6%, GWAY -7.3%, NTGR -6.9%, BWLD -5.0%, PRCP -3.3%, NILE -3.1%, WU -2.9%, SGEN -2.5%, RKUS -1.5%, LPSN -1.5%, PRO -0.7%, CLWR -0.6%, DEI -0.5%, SKT -0.2%

Today after the close the following companies reported earnings: EGP, VMI, ACC, RUSHA, BWLD, FTI, HTS, QDEL, WSH, CLF, SCI, CLWR, NTGR, HIW, SKT, THRX, WU, DDR, ELON, FRT, MIG, NILE, PRO, RATE, RLOC, GWR, MOVE, DEI, AXLL, GIVN, LPSN, RAX, ONE, SAPE, SGEN, TRLA, CSOD, GWAY, RKUS

Futures are higher after hours: S&P 500 futures are +1.72 from fair value of 1515.88 and Nasdaq100 futures are +5.60 from fair value of 2760.15.

Tomorrow morning before the open four economic reports are scheduled to be released: 1) MBA Mortgage Index, 2) Retail Sales (Consensus 0.1%) and Retail Sales ex-auto (Consensus 0.1%), 3) Export Prices ex-ag., and 4) Import Prices ex-oil.

Tomorrow before the open the following companies are scheduled to report earnings: SON, EEFT, DPS, FSRV, IMN, JNY, LO, MSA, PNK, ASPS, CBZ, PRLB, CMCSA, AVEO, TLM, ACCO, ACOR, H, NICE, VG, WCG, AAWW, BLKB, FBN, PES, TRI, CPN, HSIC, HSP, LIOX, WFR, CAE, DF, DUK, EZCH, DE

Commodities


Treasuries


Next Day In View 


Jason's Commentaries

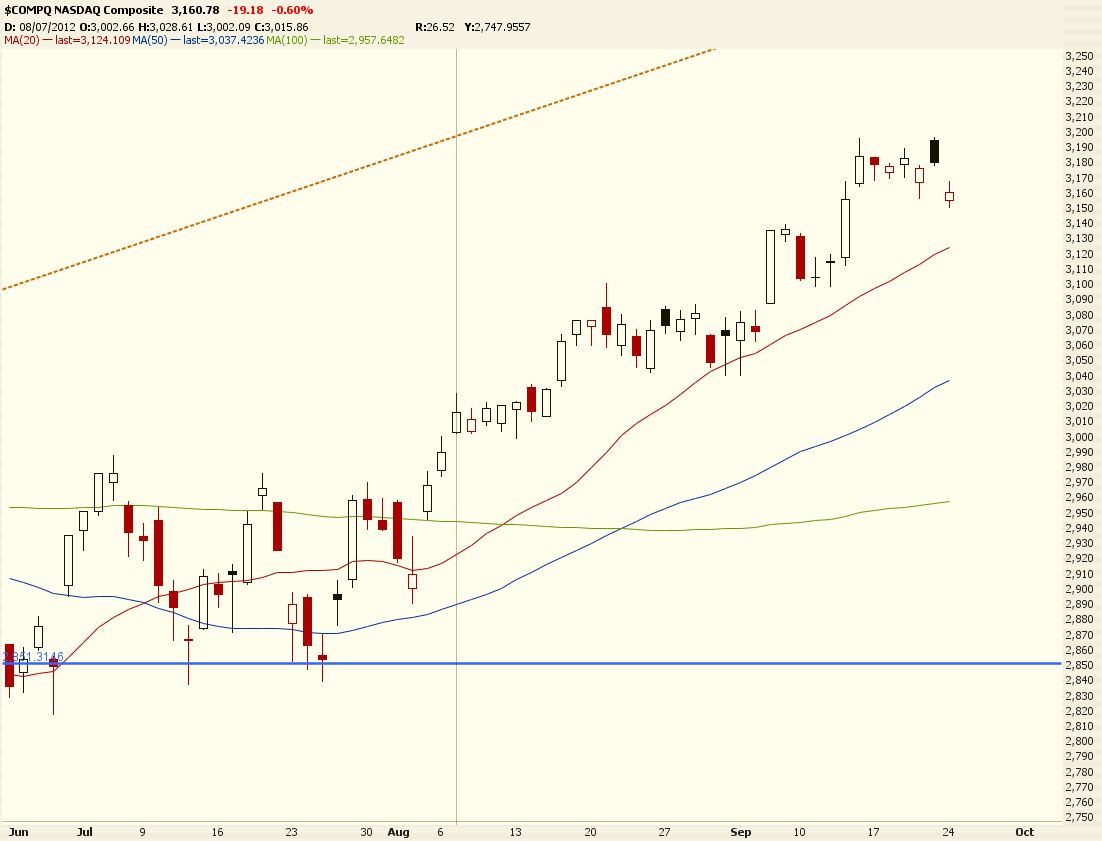
Was right on the spot that the market went flat today... It's the CNY period and it's also the flattest month in the first 4 months of the year... we're in a period of sideways and volatile period.. I was expecting something to kick the market into a retracement before I'll take any bullish action on the market. 2 of the main indices ended up higher while the Nasdaq closed lower. Volumes were slightly below average, and the bulls were outpacing the bears slightly. Divergence all around the place. VIX closed at 12.64 yesterday, visiting the low of VIX for the 5 years. The market is getting really complacent. I'll be waiting for the market to breakout from this consolidation before taking any actions. 

There are a number of speeches coming out today, coming from the Treasury Sec Nominee at 11am ET and Obama speaking at 2100 pm. We're likely to see some volatile session around today. 


Market Call:FLAT
Date: 13 Jan 2013

Tuesday, 12 February 2013

11 Feb 2013 AMC

11 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
16:10 ET Dow -21.73 at 13971.24, Nasdaq -1.87 at 3192.00, S&P -0.92 at 1517.01 :[BRIEFING.COM] The S&P 500 ended today's quiet session with a slim loss of 0.1%. Equities started the day amid mixed European trade where Italian and Spanish stocks trailed behind the remainder of the region. The relative weakness came amid continued political turmoil. 

In Italy, markets showed caution as Silvio Berlusconi speculated his party may be closing in on the lead ahead of the February 24/25 general elections. 

Meanwhile, Spanish equities underperformed as Prime Minister Mariano Rajoy continued facing increased scrutiny following allegations of having accepted secret payments from his party's slush fund. A weekend poll indicated almost 80% of all respondents have found Mr. Rajoy's explanations to be insufficient. 

As Italian and Spanish markets underperformed, their respective yields climbed higher. The Spanish 10-yr added six basis points to 5.43% while Italy's 10-yr yield rose seven basis points to 4.62%. 

While the two sovereign yields climbed higher, U.S. interest rates were little changed. The 10-yr yield eased fractionally to 1.946%. 

Like Treasury yields, U.S. equities saw little change during today's session. With no earnings or economic data of note, stocks drifted sideways throughout the day. Below average volume contributed to the uneventful trade as some traders were absent due to the aftermath of snowstorm Nemo. 

On the downside, the energy sector underperformed, and the SPDR Energy Select Sector ETF (XLE 78.19, -0.39) slipped 0.5%. Energy stocks spent the session near their lows despite an intraday spike in the price of crude oil. The energy component jumped to near $97.00 after comments from the president of Germany's Bundesbank resulted in dollar weakness, thus helping the dollar-denominated crude. The greenback lost ground to the euro after Mr. Weidmann said there is "no indication euro is seriously overvalued." 

While energy stocks were unable to lift off their lows, the defensively-oriented utilities spent the day in a steady climb. The SPDR Utilities Select Sector ETF (XLU 36.78, +0.09) added 0.3% amid relative strength from electricity producers. Exelon (EXC 31.42, +0.34) settled higher by 1.1%. 

Though utilities registered modest gains, the financial sector was the top performer. The space hovered near its highs thanks to relative strength of major components. Citigroup(C 43.15, +0.47), Wells Fargo (WFC 35.26, +0.38), and U.S. Bank (USB 34.09, +0.44) all gained in excess of 1.0%. Prior to the open, Wells Fargo and U.S. Bank were upgraded to ‘Buy' at Stifel Nicolaus. 

In sector news, Nasdaq (NDAQ 30.38, +0.91) rose 3.1% after reports indicated the exchange has held preliminary talks with Carlyle Group regarding a possible deal to go private. However, negotiations have stalled over a purchase price. 

Looking at the S&P 500 breakdown, financials (+0.4%), utilities (+0.2%), and technology (+0.1%) saw relative strength. Meanwhile, energy (-0.6%), consumer discretionary (-0.3%), and materials (-0.2%) lagged. 

Tomorrow's economic data will be limited to the January Treasury budget. This report will be released at 14:00 ET. Among notable earnings, Avon Products (AVP 17.28, +0.43) and Coca-Cola (KO 38.61, -0.16) will report their quarterly results ahead of the open. 

The U.S. Treasury will auction off $32 billion in 3-yr notes. ..NYSE Adv/Dec 1345/1641. ..NASDAQ Adv/Dec 1203/1254.


After Hours
17:57 ET CPST +13.7%, RXN +13.3%, UNIS -7.9%, DVOX -5.9% following earnings/guidance :
The S&P 500 ended today's quiet session with a slim loss of 0.1%. Equities started the day amid mixed European trade where Italian and Spanish stocks trailed behind the remainder of the region. The relative weakness came amid continued political turmoil.

Other notable after hours movers on earnings: CPST +13.7%, RXN +13.3%, CUTR +9.1%, MAS +6.8%, NCLH +3.9%, BKD +3.5%, LGF +1.3%, RICK +1.1%, ASEI +0.3%, UNIS -7.9%, DVOX -5.9%, DNB -5.6%, CSPI -4.9%, AMSC -4.8%, TWTC -2.7%, ACGL -1.0%, CNO -1.0%, FULL -0.6%, MNKD -0.4%, CHH -0.4%
Today after the close the following companies reported earnings: FWRD, NLSN, CHH, DNB, AFG, CGNX, CRK, MAS, OMI, BNNY, ACGL, BKD, MNKD, PKY, ASEI, CUTR, OTTR, QLYS, SKH, TWTC, AMSC, LGF, RICK, NCLH

Futures are lower after hours: S&P 500 futures are -0.30 from fair value of 1513.40 and Nasdaq100 futures are -0.61 from fair value of 2772.11.

Tomorrow morning before the open no economic reports are scheduled to be released.

Tomorrow before the open the following companies are scheduled to report earnings: KO, OMC, CPLA, CYNO, RAI, AB, LVLT, DBD, HERO, GT, OHI, HCP, SPAR, TRP, KVHI, AVP, SPR, HUN, MHP, RFP, FIS, ZBRA, AMRI, FOSL, MLM, MMC, RHP, TGH, VPG, ELOS, LNCE, VNDA, KORS, VAL

Commodities


Treasuries


Next Day In View 


Jason's Commentaries

Happy Chinese New Year to all!!! While on the third day of CNY and the second day of my 25 year old adult... 

Was expecting the market to go flat to the downside for monday and it came through. Chinese and Singapore market are closed in observance of the Chinese New year. We're looking at a very flat Tuesday to come as well... There are not much market moving factor today however, Obama and Draghi will be speaking respectively. It's going to be flat and volatile... Unless Draghi decides to stun everyone with some special news to tank the market. 

While looking at the internals, the volume were pathetic, lacking of participation in the market. The internals were all showing divergence all the way... while the sectors were all performing in a haphazard manner, treasuries were showing little movements... what a disappointing day to trade... 

On the side note, Crude oil rallied yesterday, with a $2 gain and it's still looking bull...  


Market Call: FLAT to downside
Date: 12 Jan 2013

Saturday, 9 February 2013

8 Feb 2013 AMC


8 Feb 2013 AMC
Market Summary 


Defense Contracts
 Raytheon Integrated Defense Systems, Andover, Mass., was awarded a $115,959,356 firm-fixed-price level-of-effort contract.  This is a modification of an existing contract to provide engineering services for the PATRIOT in support of Foreign Military Sales.  Work will be performed in Andover, Mass; Billerica, Mass.; Burlington, Mass.; El Segundo, Calif.; El Paso, Texas; Huntsville, Ala.; Norfolk, Va.; Pelham, N.H.; Tewksbury, Mass.; and White Sands Missile Range, N.M.; with an estimated completion date of Jan. 31, 2014.  One bid was solicited, with one bid received.  The Army Contracting Command, Redstone Arsenal, Ala., is the contracting activity (W31P4Q-09-C-0057).

Market Internals


Leaders and Laggards


Technical Updates


Commentaries 


16:25 ET Dow +48.92 at 13992.97, Nasdaq +28.74 at 3193.87, S&P +8.54 at 1517.93 :[BRIEFING.COM] The S&P 500 punctuated a somewhat volatile week by adding 0.6%. Though the benchmark index ended firmly in the black, the bulk of its advance took place during the initial minutes. After notching a session high in the 1518 area, the index spent the remainder of the day in a two point range. While the S&P held its levels, the Dow Jones followed its morning rally with a partial retreat which was halted near the middle of its range. 

Quiet trade unfolded as snowstorm Nemo envelops the East Coast. With forecasts calling for up to a foot of snow in New York, and more than 25 inches in Boston, today's volume paced well below average. The final tally indicated less than 600 million shares changed hands on the floor of the New York Stock Exchange. 

Storm preparation was also reflected in individual stocks as Briggs & Stratton (BGG 24.37, +0.57) and Generac (GNRC 40.54, +0.80) settled with respective gains of 2.4% and 2.0%. The two manufacturers of power generators saw some buying interest as the Northeast prepares for the possibility of interruptions to power delivery. 

Meanwhile, the broader market was powered by the technology sector. The SPDR Technology Select Sector ETF (XLK 29.93, +0.26) ended higher by 0.9% with outperformance largely due to relative strength of top components. Apple (AAPL 474.98, +6.76), Google (GOOG 785.37, +11.42), and International Business Machines (IBM 201.68, +1.94) all climbed between 1.0% and 1.5% with Google settling at a fresh all-time high. 

Remaining in the tech sector, LinkedIn (LNKD 150.48, +26.39) soared 21.3% after the company's earnings and revenue eclipsed the Capital IQ consensus estimates. Note that today's surge sent LinkedIn to a fresh all-time high of its own. 

Energy stocks outperformed as well, but the strength came despite no change in the price of oil. The energy component settled at $95.79. 

On the downside, utilities weighed, but lifted off their lows during the afternoon session. Sector component Entergy (ETR 64.47, -0.49) shed 0.8% after reporting its revenue below analyst estimates. 

This morning, the market received two economic data points. The January trade deficit narrowed to $38.5 billion thanks in part to a $3.8 billion increase in industrial supply and material exports. This occurred as imports suffered a $4.2 billion decline in industrial supplies and materials. It should be noted the brief worker strike at the Ports of Los Angeles and Long Beach likely contributed to the lower deficit. 


Elsewhere, December wholesale inventories decreased 0.1%, which was worse than the increase of 0.3% expected by the Briefing.com consensus. This report carries negative implications for the upcoming revision to fourth quarter GDP growth as the Bureau of Economic Analysis had estimated an inventory growth of 0.7% in the preliminary reading.

On Tuesday, the January Treasury Budget will be reported at 14:00 ET. While there is no economic data on Monday's docket, earnings reports will continue pouring in. CNAFinancial (CNA 31.80, +0.08) and Loews (L 43.85, +0.11) are scheduled to report their quarterly earnings ahead of the opening bell. 

 
Commodities


Treasuries


Weekly Analysis
Week 38


Technical Updates


Briefing's Commentaries


On Tuesday, the January Treasury Budget will be reported at 14:00 ET. While there is no economic data on Monday's docket, earnings reports will continue pouring in. CNAFinancial (CNA 31.80, +0.08) and Loews (L 43.85, +0.11) are scheduled to report their quarterly earnings ahead of the opening bell. 

Week in Review: S&P 500 Chops Around 1,500 
On Monday, the S&P 500 ended lower by 1.2% after European concerns returned to the forefront. Equities began the day with a broad sell-off as a downbeat European trade weighed. Italian and Spanish indices were the source of continent-wide weakness as controversy continued to plague the troubled sovereigns. In Italy the MIB lost 4.5% as authorities continue to investigate several financials, including the world's oldest bank, Banca Monte dei Paschi di Siena. Meanwhile, Spain's IBEX fell 3.8% as 34 of 35 listings ended in the red. The markets were rattled as Prime Minister Mariano Rajoy and other members of the People's Party find themselves in the middle of an alleged kickback scheme uncovered by Spain's largest daily newspaper, El Pais. Recent days have seen Mr. Rajoy face resignation calls from opposition leaders as well as Spanish citizens. European financials saw notable selling pressure with the weakness spilling over to their U.S. counterparts. The SPDR Financial Select Sector ETF (XLF 17.60, +0.04) slipped 1.1%. 

Tuesday's session brought resilience to the markets as the key averages recovered the majority of their losses from Monday. The S&P 500 settled higher by 1.0% after spending the duration of the day in a steady climb. The morning sentiment was aided by upbeat European trade where Italian and Spanish markets recovered from Monday's plunge. Domestically, seven of ten S&P 500 sectors registered gains in the neighborhood of 1.0%. Tech shares led the way after the sector felt the brunt of Monday's selling. The largest tech stock, Apple, outperformed the broader market and ended higher by 3.5%. 

Wednesday brought little change to the S&P 500 after spending the vast majority of the session in the red. The major averages began the day on a cautious note as European indices retreated in anticipation of an update from Monte dei Paschi regarding the size of its derivative-related losses. This caused selling of the Italian 10-yr as its yield climbed 13 basis points to 4.58%, its worst level since mid-December 2012. Reliance Steel (RS 71.44, +1.38) surged 5.9% following an agreement to acquire all outstanding shares ofMetals USA (MUSA 20.78, +0.09) for $20.65 per share. The purchase price represents a 12.8% premium to Metals USA's Tuesday closing price, and the total transaction value is estimated at $1.2 billion. 

On Thursday, equities ended the day with slim losses causing the S&P 500 to slip 0.2%. Though stocks saw little change at the outset of the session, sellers were able to take control within the first 30 minutes, and drive the major averages to their respective lows. The early broad-based weakness came about as the dollar index spiked to its highs in the 80.20 area. The sharp move took place after European Central Bank President Mario Draghi voiced concerns over the strength of the euro. The common currency weakened immediately following his remarks, falling to its session low near 1.3400 against the greenback. Phillip Morris (PM 90.45, +0.63), rose 2.4% after beating on earnings. ..NYSE Adv/Dec 2006/948. ..NASDAQ Adv/Dec 1547/886.


Next Week In View


Jason's Commentaries

What boring Friday. The market spiked up at the start of the day and stayed flat through the session. The tech were the stronger boys who where leading the market, with Google hitting a fresh time high. The volumes in the NYSE was under 600 million shares, with the effect of a storm coming. I would say it was definitely a weak bullish day with a TRIN showing some divergence. There are little changes in the Treasuries as well in such a weak Friday. On the Technical note, I'll reaffirm my stand on a very volatile week as the Feb is going to have some retracement before breaking into the higher high.

While on the weekly perspective, the market is still on a solid bull run, while the Dow forms a hanging man at the resistance. This likely to indicate an end of trend. With a little push, the market will likely go into a retracement despite the bullish sentiment.

We're looking at more volatile period to come. Tighten your sitbelts =D

Happy Chinese New Year in advance peeps~~ And btw... it's my birthday on the first day of CNY!


Market Call: DOWN
Market Call(weekly): DOWN
Date: 11 Feb 2013