Thursday, 21 February 2013

20 Feb 2013 AMC


19 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 

Stock Market Update
16:30 ET Dow -108.13 at 13927.54, Nasdaq -49.18 at 3164.41, S&P -18.99 at 1511.95 : [BRIEFING.COM] The S&P 500 settled lower by 1.2% after spending the entire session in negative territory.

Equities began the day on a lower note amid mixed housing data and hovered near their lows ahead of the Fed's minutes.

Stocks then fell to fresh lows after the minutes indicated Committee members saw little change to the economic outlook. Along those lines, members—with the exception of Esther George—maintained their support for the continuation of highly accommodative policy.

Homebuilders were under pressure after Toll Brothers (TOL 33.56, -3.34) reported its quarterly results this morning. The builder missed on earnings and revenue, but saw an increase to its backlog. In addition, the company raised its full-year 2013 gross margin guidance during its earnings call.

Homebuilders sold off in reaction to Toll's earnings and afternoon weakness pushed builder stocks further into the red. Peers PulteGroup (PHM 18.60, -1.35) and D.R. Horton (DHI 21.92, -1.37) were off 6.8% and 5.9% respectively.

Elsewhere among discretionary shares, Office Depot (ODP 4.18, -0.84) andOfficeMax (OMX 12.09, -0.91) announced the completion of their stock-for-stock merger. Competitor Staples (SPLS 13.60, -1.05) fell 7.2% on the news.

As a result of today's selling, six of 10 S&P 500 sectors lost over 1.0%. Energy and materials were the weakest performers in early trade, and continued lower during the afternoon. The energy sector saw some pressure from crude oil, which fell 2.4% and settled just under $95.00.

Elsewhere, materials underperformed as industrial and precious metals displayed notable weakness for the second consecutive session. In addition, chemical producer CF Industries (CF 207.07, -11.46) fell 5.2% after missing on the top line.

The tech space was another notable laggard. The largest sector component, Apple(AAPL 448.85, -11.14) lost 2.4% after reports indicated Foxconn, which assembles Apple products, has instituted a hiring freeze. However, the initial report was followed by stories suggesting the hiring freeze may not be related to changes in demand for Apple products. Instead, Foxconn could be making adjustments to better suit other companies it conducts business with.

The first half of the session saw out performance from defensively-oriented consumer staples, telecoms, and utilities. Though these sectors succumbed to broad pressure in afternoon trade, they settled with slimmer losses than the broader market.

Today's sell-off stirred up some demand for downside protection. This was reflected by the CBOE Volatility Index (VIX 14.62, +2.31), which surged over 15.0%. In the futures market, VIX contracts saw buying interest as well with the largest moves apparent in front-month contracts.

Volume was well above average today as 816 million shares changed hands on the floor of the New York Stock Exchange.

Taking a final look at the day's S&P 500 sector alignment, materials (-2.8%), energy (-1.8%), consumer discretionary (-1.6%), and technology (-1.5%) stocks were among the biggest laggards. Meanwhile, consumer staples (-0.1%), telecoms (-0.2%), and utilities (-0.2%) withstood the brunt of the selling.

Looking back at today's economic data, January housing starts were reported at an annualized rate of 890,000 units, which fell short of the 914,000 expected by the Briefing.com consensus. However, the prior month's reading saw a substantial upward revision.

Additionally, building permits beat expectations and rose to 925,000. This report is seen as a leading indicator suggesting demand for new homes remains intact.

Tomorrow's economic data will be plentiful. At 8:30 ET, weekly initial and continuing claims, January CPI, and core CPI will all be released. Meanwhile, January existing home sales, leading indicators, and February Philadelphia Fed Survey will all be reported at 10:00 ET. ..NYSE Adv/Dec 715/2327. ..NASDAQ Adv/Dec 546/1963.


After Hours
18:49 ET PEGA +18.6%, MKTG +9.0%, AWAY +8.8%, PAY -32.6%, RBCN -14.4%, ACHN -7.4% following earnings/guidance :
The S&P 500 settled lower by 1.2% after spending the entire session in negative territory.
Other notable after hours movers on earnings: PEGA +18.6%, MKTG +9.0%, AWAY +8.8%, SNPS +4.9%, JOBS +4.5%, HURN +2.7%, TRN +2.7%, UNTD +2.1%, OEH +1.7%, VRML +1.5%, FELE +1.4%, ACHC +1.4%, ETP +1.2%, AEL +1.1%, PAY -32.6%, RBCN -14.4%, ACHN -7.4%, TSLA -5.9%, SB -5.8%, WLT -5.8%, PPO -5.0%, SYNC -4.6%, SAM -2.3%, CROX -2.3%, CAKE -1.8%, FLR -1.3%, WPZ -1.1%, WIRE -0.5%

Today after the close the following companies reported earnings: LHO, HLX, WCN, ARII, CAKE, CLW, CROX, FR, IDCC, KBR, SYNC, TRN, WIRE, AUY, FST, XCO, DENN, HURN, MDAS, PPO, STR, BALT, DRCO, GNK, HT, NEWP, PVA, SM, WMB, WPZ, AWAY, EQY, FLR, MANT, SAM, TTS, UNTD, AEL, DEPO, FELE, MKTG, TSLA, WLT, CNK, CW, GDP, KAR, QLTY, RBCN, WAGE, CXO, ETE, ETP, HR, LOCK, MHLD, PAAS, RGP, RP, STAG, SXL, PEGA, IAG, SB, SZYM, JACK, SNPS, HEI

Futures are mixed after hours: S&P 500 futures are -2.16 from fair value of 1509.56 and Nasdaq100 futures are -2.55 from fair value of 2739.55.
Tomorrow morning before the open two economic reports are scheduled to be released: 1) Initial Claims (Consensus 358k) and Continuing Claims (Consensus 3150k), and 2) CPI (Consensus 0.1%) and Core CPI (Consensus 0.2%).

Tomorrow before the open the following companies are scheduled to report earnings: HST, SWY, DFRG, LTM, VAC, JAKK, IART, CMS, CWEI, FAF, IMAX, LBY, LINE, RS, SUI, VCI, VDSI, DAN, KDN, TASR, PCG, SPNC, ESV, HSNI, MDSO, PWR, TFX, CHK, DORM, HEP, IDA, IRC, PEG, PKD, PXP, SFY, SMA, WST, CCC, GEO, ICGE, AYR, CBR, CCOI, DNR, LXP, SCG, THS, FNP, CG, GTXI, THI, TK, TNK, ZEUS, BRC, WMT, HRL, PDCO, ZLC, TTC, SAFM


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

The FOMC minutes sunk the market more than what I expected, causing the DOW to sink a 108 points. The market was flat at the start of the day as expected, until 2pm ET, when the FOMC minutes came out. Initially the market was holding on for a while but subsequently sold off before the closing bell. While in the internals, it was clearly bearish. VIX spiked up a 19.25%, closing at 14.68. While looking at the sectors, Materials were the main laggard, losing more than 2% yesterday. The other sectors... sunk more than 1% except for the defensive sectors. CAT sunk yesterday before the FOMC minutes after releasing sales results that sunk that stock, which provided lags for the DOW. On top of that, United Healthcare, UNH, also provided lags on the DOW as well.

Taking a look at the Treasuries... It was a clear bullish day for the Treasuries.. Now it seems that the market is rushing into bonds again. Perhaps the correction is coming? While on the technical note, DOW hit a resistance, and is now retracing.While on the commodities.. Oil, Gold and Silver are making tremendous move... to the downside. Oil crashed below $94 yesterday, Gold crashed more than a 500 points yesterday, and silver, losing a full dollar.

Before the market open, Asian market sunk as a result of a 100 points drop on the DOW. Now, the European market is starting with weakness coming from the Asian Market.

We are having quite a number of reports coming out today. It's gonna be hell of a day. If the reports come out lousy, we're definitely gonna see a wash out today. But if the reports provide some cushion, we're likely to see some sideways to down day.


Market Call: DOWN
Date: 21 Jan 2013

Tuesday, 19 February 2013

19 Feb 2013 AMC

19 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
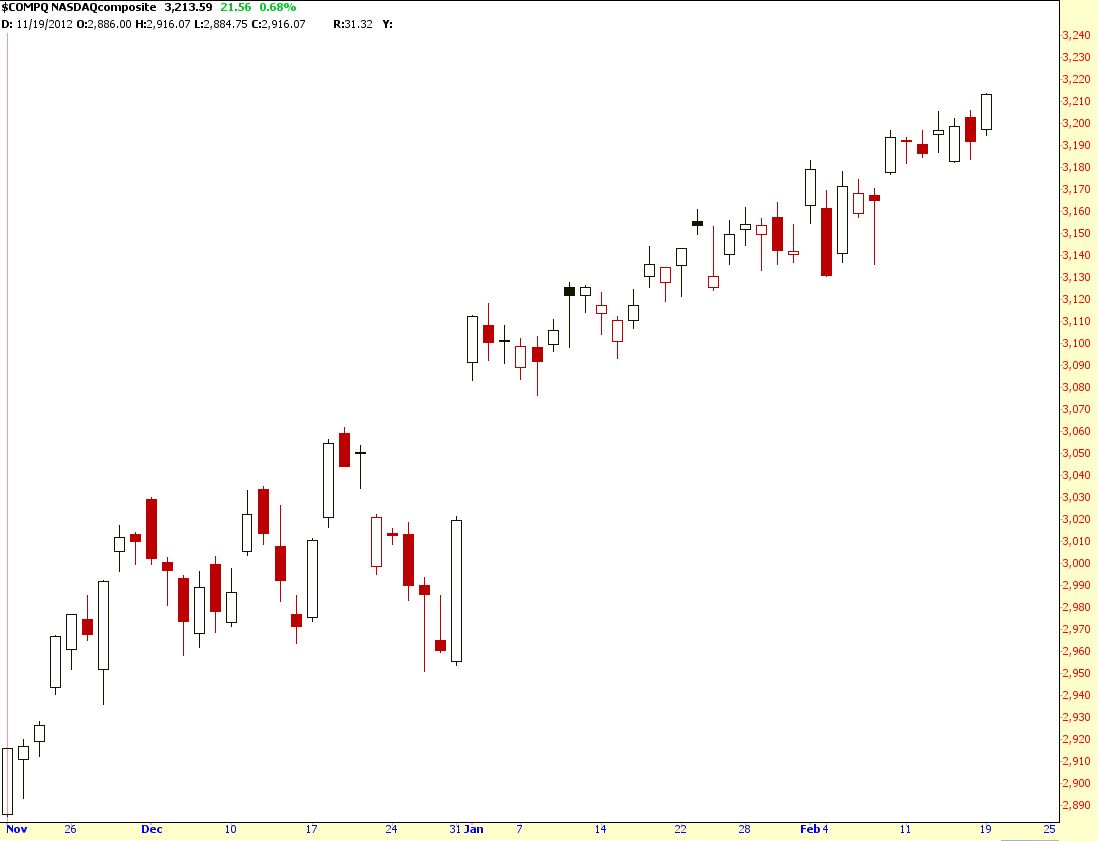
16:15 ET Dow +53.91 at 14035.67, Nasdaq +21.56 at 3213.59, S&P +11.15 at 1530.94 : [BRIEFING.COM] The S&P 500 settled higher by 0.7% after spending the duration of the day in a steady upward climb. Equities got off to an upbeat start supported in part by bullish European trade. In addition, merger speculation helped support the markets at the open. 

Reports out over the weekend indicated Office Depot (ODP 5.02, +0.43) and OfficeMax(OMX 13.00, +2.25) have discussed a stock-for-stock merger. As a result, shares of the two ended with respective gains of 9.4% and 20.9%. In addition, Staples (SPLS 14.65, +1.70) surged 13.1% as the company stands to benefit from more rationalized competition. The outperformance from the three names helped the SPDR S&P Retail ETF (XRT 68.69, +1.22) gain 1.8%. 

While some areas of the discretionary sector saw strength, homebuilders lagged notably. The iShares Dow Jones US Home Construction ETF (ITB 23.33, -0.17) shed 0.7% after seeing intraday losses in excess of 2.0%. The space underperformed after the February NAHB Housing Market Index slipped to 46 from its previous reading of 47. The index turned out to be a disappointment as the Briefing.com consensus had expected an uptick to 48. 

Health care stocks were in the news this morning when the Centers for Medicare & Medicaid Services proposed lower 2014 Medicare co-payments. The news carried a negative impact for health care providers as Humana (HUM 73.01, -4.98) andUnitedHealth Group (UNH 56.66, -0.66) lost 6.4% and 1.2% respectively. 

On the downside, the materials sector was the weakest performer. The space lagged as industrial metals traded broadly lower. Aluminum, nickel, and copper all lost between 1.5% and 1.7%. In addition, Chinese authorities are expected to unveil measures aimed at curbing the rapid rise in home prices. With such limits, lower construction demand should translate into lower material prices. 

Glancing at the S&P 500 sector performance, energy (+1.2%), consumer staples (+1.0%), and utilities (+0.9%) were among the top performers. On the downside, materials (-0.4%) and consumer discretionary (+0.4%) stocks lagged. 

Today's volume was right in-line with its average as 735 million shares changed hands on the floor of the New York Stock Exchange. 

The busy part of the fourth quarter earnings season is nearing its end as more than 400 S&P 500 components have already reported their results. Of the 402 companies, 67% have exceeded bottom line estimates. However, revenue beats were more common this quarter (67%) than in the past two (40% each) quarters. 

Looking forward, first quarter earnings are expected to be flat year-over-year. This is down from the initial expectations of 3.0% growth. In addition, first quarter revenue growth is not expected to exceed 1.0%. 

In tomorrow's economic data, weekly MBA Mortgage index will be reported at 7:00 ET. At 8:30 ET, January housing starts, building permits, PPI, and core PPI will all be announced. Lastly, the Federal Reserve will release the minutes from its latest meeting at 14:00 ET. In earnings, DISH Network (DISH 36.09, -0.84) and Toll Brothers (TOL 36.90, -0.18) are scheduled to report their results ahead of the open. ..NYSE Adv/Dec 2085/931. ..NASDAQ Adv/Dec 1677/815.


After Hours
18:25 ET DMD +14.8%, LZB +10.6%, RMBS +9.3%, MM -26.0%, TEX -6.4% following earnings/guidance :
The S&P 500 settled higher by 0.7% after spending the duration of the day in a steady upward climb. Equities got off to an upbeat start supported in part by bullish European trade. In addition, merger speculation helped support the markets at the open.

Other notable after hours movers on earnings: DMD +14.8%, LZB +10.6%, RMBS +9.3%, SINA +6.3%, MDRX +5.7%, UCTT +4.5%, LOPE +4.1%, CLDT +3.5%, FNF +3.4%, NVMI +3.2%, TXRH +3.1%, UAM +0.5%, DELL +0.2%, MM -26.0%, ZIXI -6.7%, TEX -6.4%, ARSD -3.7%, ANAD -2.9%, BJRI -2.6%, KONA -1.4%, NBR -1.4%, ICAD -1.4%, ADI -0.9%, MAR -0.8%, POST -0.5%, CF -0.3%, OIS -0.2%

Today after the close the following companies reported earnings: MAR, UCTT, NBR, NFX, ZIXI, KALU, TEX, BAS, BJRI, CLUB, ANAD, HLF, PSB, CNL, QEP, WTS, NVMI, OIS, DX, LLNW, LOPE, SHO, SLTM, TXRH, UAM, CCO, HY, CF, DMD, FNF, KONA, MM, ROG, AMRS, CLDT, FNGN, PRA, MDRX, DELL, SINA, BOBE, ADI, LZB

Futures are mixed after hours: S&P 500 futures are -0.28 from fair value of 1528.48 and Nasdaq100 futures are +0.82 from fair value of 2782.18.

Tomorrow morning before the open five economic reports are scheduled to be released: 1) MBA Mortgage Index, 2) Housing Starts (Consensus 914K), 3) Building Permits (Consensus 918k), 4) PPI (Consensus 0.3%) and 5) Core PPI (0.1%).

Tomorrow before the open the following companies are scheduled to report earnings: SAH, DTE, LAD, LL, MDCO, NOR, OC, PVR, SIX, VTNC, XRAY, EXAS, GOV, GRMN, GTN, MGM, DW, ICON, VNTV, ZINC, AVA, CNK, CRIS, DISH, SATS, TX, AER, CLH, DVN, LEAP, SODA, AEE, DXYN, EV, TOL
Commodities


Treasuries


Next Day In View 


Jason's Commentaries

Definitely a strong day to start the week after President's Day in the US last night. S&P500 broke into higher highs yesterday while the DOW visited its high again last night. While looking at the internals, it was moderately bullish last night, except the UVOL did not outpace the DVOL as much. Volumes were healthy and will be expecting the trend to continue in the near term. VIX started the day higher however closed at 12.31. Which further reaffirmed the bullishness in the market. 

A bulk of the of the housing stocks faced heavy intraday losses last night, of up to 2% within the housing sector. Most of the housing stocks closed in the red last night. As for the Healthcare sectors, the HMOs were heavy hit by a not so good proposal against the Medicare industry. Humana, United HealthCare where down as much as 9% at the start of the day which subsequently fought back up to close the day with lesser losses. 

While looking at the data coming out on Wednesday, I'm expected the market to gyrate quite a bit when the FOMC minutes is out, before that,the market is likely to open higher but flatter in observance of the FOMC minutes.  


Market Call: FLAT to downside
Date: 20 Feb 2013

Sunday, 17 February 2013

15 Feb 2013 AMC


15 Feb 2013 AMC
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Commentaries 


Stock Market Update
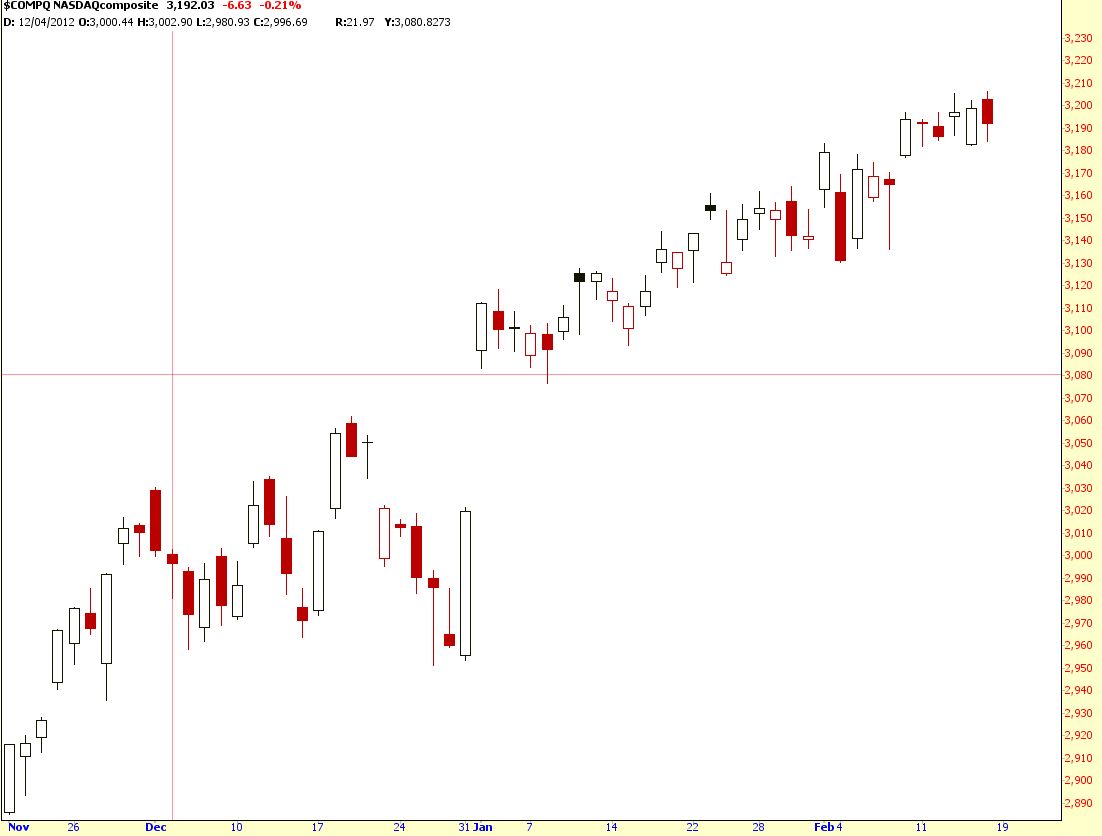
16:25 ET Dow +8.37 at 13981.76, Nasdaq -6.63 at 3192.03, S&P -1.59 at 1519.79 :[BRIEFING.COM] The major averages ended today's session on a mixed note. The Dow added 0.1% while S&P 500 shed 0.1% after late-afternoon weakness pressured the index to its lows. 

Equities saw little change into the final two hours of trade when reports indicated Wal-Mart (WMT 69.30, -1.52) saw a slow start to its February sales. Bloomberg obtained emails from the company's vice president of finance and logistics who said "February [month-to-date] sales are a total disaster." The vice president also said this was the worst start to a month he has seen in his seven years with the company. 

Shares of Wal-Mart fell to session lows on heavy volume, but managed to recover a portion of their losses. In addition, the news weighed on other retailers. Target (TGT 61.71, -1.02) and Family Dollar (FDO 55.94, -0.67) saw respective losses of 1.6% and 1.2%. Meanwhile, the broader SPDR Retail ETF (XRT 67.47, -0.26) lost 0.4% after being up as much as 1.4% in earlier trade. 

The consumer staples sector saw activity throughout the day. This morning, Campbell Soup (CPB 39.40, +0.68) J.M. Smucker (SJM 92.40, +0.24), and Kraft Foods (KRFT 47.17, +0.01) reported earnings. All three names beat on the bottom line and Kraft was the only one of the three which missed on revenue. 

Consumer stocks fared relatively well into the afternoon and the discretionary sector was the top performer until the Wal-Mart news spilled over to several other retail names. 

Contributing to the early strength was an upbeat January consumer sentiment survey from the University of Michigan. According to the preliminary reading, the survey rose to 76.3 from its prior reading of 73.8. Today's report surprised to the upside as the Briefing.com consensus had expected the survey would climb to 73.5. 

While consumer stocks were in focus for the bulk of the day, the energy sector was the day's biggest laggard. The SPDR Energy Select Sector ETF (XLE 78.45, -0.91) lost 1.2% amid weakness in crude oil. The energy component fell 1.4% to $95.99. 

The CBOE Volatility Index (VIX 12.51, -0.15) settled in the red despite a brief jump into positive territory. However, the term structure of VIX futures reveals some buying interest at the distant end of the curve as June, July, September, and October contracts settled with slight gains. 

When the dust from today's active afternoon—and not so active remainder of the day—settled, defensively-oriented sectors ended in the lead. Telecoms (+0.3%), utilities (+0.3%), health care (+0.2%), and consumer staples (+0.2%) outperformed while energy (-1.1%), financials (-0.3%), and technology (-0.1%) lagged. 

Today's volume represented the highest total of the week as 940 million shares changed hands on the floor of the New York Stock Exchange. However, February options expiration did its part to push the total above its 50-day average, which sits in the neighborhood of 700 million. 

Comments from this weekend's G20 summit taking place in Russia have begun making the rounds. Earlier, Jens Weidmann of Germany's Bundesbank said the euro is not overvalued and the European Central Bank President Mario Draghi is not talking down the common currency. Meanwhile, Mr. Draghi said euro exchange rate is not a policy target for the central bank. 

Looking at the day's remaining economic data, January industrial production decreased 0.1%, which was worse than the 0.2% uptick that had been expected by the Briefing.com consensus. Meanwhile, capacity utilization hit 79.1%, which was better than the 78.9% expected by the Briefing.com consensus. 

February Empire Manufacturing Survey climbed to 10.0 from its prior reading of -7.8. The report was a positive surprise as the Briefing.com consensus expected the survey to rise to 0.0. 

Lastly, net long-term TIC flows showed an inflow of $52.3 billion in foreign funds into USD-denominated assets during November. 

Note that equity and bond markets will be closed on Monday in observance of Presidents Day. 

On Tuesday, the NAHB Housing Market Index will be reported at 10:00 ET. Among earnings of note, Barnes & Noble (BKS 13.03, -0.11) and RadioShack (RSH 3.27, -0.06) will report their quarterly results prior to the open. 


Commodities


Treasuries


Weekly Analysis
Week 38


Technical Updates


Briefing's Commentaries

Week in Review: S&P 500 Inches Higher
On Monday, the S&P 500 ended a quiet session with a slim loss of 0.1%. Equities started the day amid mixed European trade where Italian and Spanish stocks trailed behind the remainder of the region. The relative weakness came amid continued political turmoil as Silvio Berlusconi speculated his party may be closing in on the lead ahead of the February 24/25 general elections. Meanwhile, Spanish equities underperformed as Prime Minister Mariano Rajoy continued facing increased scrutiny following allegations of having accepted secret payments from his party's slush fund. A weekend poll indicated almost 80% of respondents have found Mr. Rajoy's explanations to be insufficient.Nasdaq (NDAQ 31.07, +0.47) rose 3.1% after reports indicated the exchange has held preliminary talks with Carlyle Group regarding a possible deal to go private. However, negotiations have stalled over a purchase price.
Tuesday saw equities settle on a mixed note. The Dow climbed 0.3% and registered its highest close of the year while the S&P 500 added 0.2%, and Nasdaq shed 0.2%. The day got off to a slow start as the major averages spent the entire morning near their respective unchanged levels. However, key indices were able to climb to their highs in afternoon trade as financials paced the advance. The financial sector led throughout the session, and the S&P 500 Financials Index climbed above 240 for the first time since October 2008. Bank of America (BAC 12.03, -0.10) and Citigroup (C 43.84, -0.48) both gained near 3.0% as the two supported the space.
Wednesday's session also ended on a mixed note despite initial strength. The Dow slipped 0.3%, while the S&P 500 and Nasdaq eked out gains of 0.1% and 0.3% respectively. The S&P 500 began the day on an upbeat note amid strength in industrials and discretionary shares. The two sectors outperformed after Comcast (CMCSA 41.24, +0.90) reported strong earnings and announced the acquisition of General Electric's (GE 23.29, -0.12) 49% stake in NBCUniversal. General Electric gained 3.6%, and settled near its highs while Comcast added 3.0% after being up as much as 7.6% in early trade.
On Thursday, the major averages ended little changed with the S&P 500 tacking on 0.1%. The benchmark index settled slightly higher after spending the majority of the day within a two point range of Wednesday's close. Equities slipped out of the gate with the downbeat European trade contributing to early weakness. This resulted from disappointing fourth quarter GDP reports from France, Germany, Greece, Italy, and Portugal. All five countries saw their economies contract during the final three months of 2012. As a result, the fourth quarter Eurozone GDP shrank 0.6% quarter-over-quarter. H.J. Heinz (HNZ 72.29, -0.22) surged 20% after agreeing to be acquired by a group including Warren Buffet's Berkshire Hathaway (BRK.B 99.77, +0.56) for $28 billion, or $72.50 per share. The agreed price represents a 20% premium to Heinz's Wednesday close.

Next Week In View


Jason's Commentaries

What a flat week to begin with... Ended flat on the week as well... Most sectors were flat last week. However, Friday, the consumer discretionary sector were dragged down by Walmart, S&P500 and NASDAQ COMPOSITE  were down, while DJIA were held up by IBM.. So if we look at the internals, we have more than 800 million shares traded on the NYSE, on the Feb expiration Friday. Friday ended with a slight bound to make back its losses the market suffered at the start of the trading session. I'm seeing that as a bullish momentum towards the end of the trading day and I'm definitely expected Tuesday(Monday is a non-trading session) to be bullish. However, we saw the VIX slipping slightly, TRIN in the bearish region, the bears outpacing the bulls slightly throughout the session, I'm still expecting the market to continue to move sideways for at least one more week. While next week we're having the FOMC minutes coming out again on Wednesday, the Tuesday might just go flat in expectation of Wednesday's minutes.


Market Call: FLAT to upside
Market Call(Weekly): FLAT 
Date: 19 Feb 2013

Friday, 15 February 2013

14 Feb 2013 AMC


12 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

Ok... this is getting boring... the market has been sideways for a long time already.. I was right having the market getting flat.. I'm like repeating my DMA again and again saying the same things.. But however, treasures rallied yesterday... so that's something to take note of. Apart from that, everything else remains unchanged. Take note of the Consumer sentiment report coming up today at 955am ET. That will unlikely to move the market much. Belated happy valentines peeps =D 

Market Call: FLAT to downside
Date: 14 Jan 2013


Thursday, 14 February 2013

13 Feb 2013 AMC


13 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 

Stock Market Update
16:25 ET Dow -35.79 at 13982.91, Nasdaq +10.39 at 3196.88, S&P +0.90 at 1520.33 : [BRIEFING.COM] The major averages finished today's session on a mixed note despite this morning's strength. The Dow slipped 0.3%, while the S&P 500 and Nasdaq eked out gains of 0.1% and 0.3% respectively.

The S&P 500 began the day on an upbeat note amid strength in industrials and discretionary shares. The two sectors outperformed after Comcast (CMCSA 40.13, +1.16) reported strong earnings and announced the acquisition of General Electric's(GE 23.39, +0.81) 49% stake in NBCUniversal. General Electric gained 3.6%, and settled near its highs while Comcast added 3.0% after being up as much as 7.6% in early trade.

General Electric contributed to the relative strength of the industrial sector, which ended as the top performer. Elsewhere in the space, 3D Systems (DDD 65.61, +2.54) advanced 4.0% after President Obama spoke positively about the three-dimensional printing industry during last night's State of the Union address.

President Obama also called for an increase of the federal minimum wage to $9/hour. This proposal weighed on restaurant operators where many workers earn minimum wage. McDonald's (MCD 94.00, -1.10) lost 1.2% and other quick service restaurants lagged as well. Buffalo Wild Wings (BWLD 76.55, -4.52) fell 5.6% after missing on the bottom line. In addition, the company is expected to face a difficult year with high wing costs responsible for the cautious outlook.

The weakness among restaurant stocks weighed on the discretionary sector and negated some of the strength provided by the shares of Comcast.

Afternoon trade saw underperformance from financials after several sector components notched fresh multi-year highs yesterday. Bank of America (BAC 12.17, -0.07) and Citigroup (C 44.00, -0.35) led the space during yesterday's action, but ended today's session with respective losses of 0.6% and 0.8%.

The CBOE Volatility Index (VIX 12.98, +0.34) climbed throughout the session, but slipped off its highs into the close. Meanwhile, the VIX term structure saw the biggest rise in May and June futures contracts.

Volume remained below average, but today's total of 657 million shares represented the most active session so far this week.

Treasury yields crept higher following today's 10-yr auction which priced at 2.046%, its highest since March 2012. The bid-to-cover ratio came in at 2.68, which was below the 12-auction average of 2.99. Although demand from indirect bidders lagged, primary dealers ended up with nearly 48% of today's supply. The 10-yr settled at 2.023%, its highest level in 10 months.

Overseas, the Bank of England raised its inflation forecast. However, Governor Mervyn King said the central bank will not hike interest rates in response as doing so would risk derailing a "slow but sustained" recovery.

Mr. King's comments were followed by reports which indicated some European Central Bank officials are worried the recent strength of the euro will hamper the recovery in crisis states. These reports were met with a quick rebuttal from Germany's Finance Minister Wolfgang Schaeuble who said another major crisis could develop if countries continue to flood the world with money.

Currency-related comments are likely to continue through the weekend with the G20 summit set to begin on Friday.

Today's economic news had little trading impact. December business inventories rose 0.1%, which was slightly lower than the 0.3% rise expected by the Briefing.com consensus. Elsewhere, January retail sales climbed 0.1%, in-line with expectations. Though retail sales met expectations, this report is likely to be watched in the coming months in order to assess the impact of the expiration of the payroll tax cut as well as higher tax rates for top earners.

In other news, export prices, excluding agriculture, increased by 0.5% in January after they had decreased by 0.2% during the prior month. Excluding oil, import prices increased by 0.2%, which followed the 0.1% decrease experienced in the prior month.

Tomorrow's economic data will be limited to weekly initial and continuing claims. This report will be released at 8:30 ET. General Motors (GM 28.67, +0.12) and PepsiCo(PEP 71.50, -0.67) are among the notable names scheduled to report their quarterly results prior to the open. The U.S. Treasury will auction off $16 billion in 30-yr bonds. ..NYSE Adv/Dec 1765/1251. ..NASDAQ Adv/Dec 1347/1095.


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

The market was flat again yesterday... all 3 indices broke down after market open but closed back with some gains by the market close.  While looking at the internals, we're having an equal fight between the bulls and the bears with the volumes at 636m shares traded on the NYSE. All of the 9 sectors are ranging below 1%, with not much leadership within the sector. While on the technical note, we're ranged bounded, awaiting for some catalyst to get the market to breakout. Looking at the incoming news,  we have only the unemployment claims coming out at 830am ET, which is unlikely to move the market much unless there is some big difference between the expected and actual. Else, we'll be expecting a very flat session for valentine's day. Don't forget there's a Valentine's Day rally... 

Market Call: FLAT to upside
Date: 14 Jan 2013