Thursday, 11 April 2013

10 Apr 2013 AMC


10 Apr 2013 AMC
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
16:25 ET Dow 128.78 at 14802.24, Nasdaq 59.39 at 3297.25, S&P 19.12 at 1587.73 :
[BRIEFING.COM] After alternating between gains and losses for 14 straight sessions, the S&P 500 has pulled a hat trick this week.  It has now scored gains in every session this week and, boy, the third time was a charm.
The market rallied sharply, bolstered by its confidence in the support of the Federal Reserve and healthy gains in influential leadership groups that helped both the Dow and S&P 500 register all-time intraday highs and closing highs today.
The minutes from the March FOMC meeting were the focal point throughout the session.  To begin, they caused a stir after being released early (9:00 a.m. ET) since the Fed discovered they were inadvertently released to 100 Congressional staffers and employees of trade organizations around 2:00 p.m. ET on Tuesday.  The matter of their premature release is under investigation, yet the minutes themselves underpinned today's gains.
Several views were expressed in the minutes, but the compilation of those views pointed to a majority view that the Fed should at least start tapering its purchases by the end of the year on the assumption labor market conditions are improved by then.  It is important not to forget that what the FOMC decides to do will ultimately be dictated by incoming data. The Fed has been clear on that reminder for a long time. To that end, the minutes also pointed out that a couple of members noted the pace of purchases might appropriately be increased (emphasis our own) if progress toward the committee's economic goals was not maintained.

Our view is that the minutes were supportive for the equity market for the following reasons:
  • Not many participants want the Fed to stop or to taper purchases without proof that improving economic conditions are sustainable. Therefore, when the time comes it will be against a backdrop of sustained economic improvement that bodes well for consumer and business spending, and earning prospects.
  • The minutes are working toward reducing the element of surprise for market participants as it relates to future policy decisions.
  • The March nonfarm payrolls report, out after the FOMC meeting, does not fit with the tapering parameters maintained by Fed Chairman Bernanke, Vice Chairman Dudley, and Fed Governor Yellen who will continue to steer the policy directive.
The debate about the inferences of the FOMC Minutes will persist, yet the equity market certainly did not act as if it feared an earlier-than-expected tapering.  The major averages moved steadily higher from the sound of the opening bell before leveling off around 1:00 p.m. ET.  From that point on, they held in tight trading ranges that left them in close proximity to their best levels of the day by the time the closing bell rang.
Every sector participated in the advance, although the strongst gains were registered by the technology (+1.8%), health care (+1.7%), and industrial (+1.3%) sectors.  Separately, the Dow Jones Transportation Average soared 1.8%.  The worst-performing group was the energy sector, which was up "only" 0.5%.
There were some pockets of weakness, like the homebuilders, which failed to ride the coattails of the Taylor Morrison Home IPO (TMHC 23.05, +1.05).  Gold ($1558.80, -$27.90) was another laggard after Goldman Sachs cuts its price targets for the yellow metal through 2014.  Treasuries, meanwhile, were weak with the 10-year Note dropping 15 ticks, bringing its yield up to 1.81%.
By and large, stock monitors were filled with green figures.  Advancers outpaced decliners by a 3-to-1 margin at the NYSE and by a nearly 4-to-1 ratio on the Nasdaq.  Per usual, there was a volume spike in the final hour that made lackluster volume totals throughout the day look more respectable at the closing bell.  In total, 701 mln shares traded hands at the NYSE.  That was slightly ahead of yesterday's total, yet it wasn't heavy at all in the context of the breakout move that was made today.
The moderate volume could be interpreted as a sign of reservations ahead of the first quarter earnings reports, which will start flooding in next week.  JPMorgan Chase (JPM) and Wells Fargo (WFC), however, report before the open this Friday.
Results from Bed Bath & Beyond (BBBY) will be in focus on Thursday along with the initial claims report for the week ending April 6, which will be released at 8:30 a.m. ET.  The Briefing.com consensus estimate for initial claims is pegged at 365,000.


After Hours
17:45 ET ZUMZ +9.6%, BBBY +1.8%, NG +1.6%, FTNT -14.6%, IART -8.8%, APOG -6.8% following earnings/guidance :
After alternating between gains and losses for 14 straight sessions, the S&P 500 has pulled a hat trick this week. It has now scored gains in every session this week and, boy, the third time was a charm.
Today after the close the following companies reported earnings: APOG, BBY, RELL, RT
Futures are mixed after hours: S&P 500 futures are +1.21 from fair value of 1582.59 and Nasdaq100 futures are -1.51 from fair value of 2853.51.
Tomorrow morning before the open four economic reports are scheduled to be released: 1) Initial Claims (Consensus 365k), 2) Continuing Claims (Consensus 3058k), 3) Export Prices ex-ag., and 4) Import Prices ex-oil.
Tomorrow before the open the following companies are scheduled to report earnings: KMX, STZ, FDO, FAST, JKS, MSM, PGR, TITN


Commodities


Treasuries


Next Day In View 


Jason's Commentaries


That certainly came out from nowhere. A 128 point gain for Dow last night, after the release of FOMC minutes. The FOMC were released first hand to some financial firms before the official release, causing a stir. However, that did not stop the market from breaking the new high again. It seems that my prediction of 15,000 is coming through soon, in 200 points time. Last night, Tech, healthcare, financials and industrials were the major leaders, having gained more than 1.33%. While we got no laggard and the internals were at 700m shares traded on the NYSE. The bears were totally outrun. Market tops has been the most difficult to read and it's definitely not a good idea to be on short now until towards the end of Apr. VIX went down to a low of 12.47. It seems it's history all over again. On Thursday, we're having only the unemployment claims coming out at 830am ET and we're likely to see another up day as Futures were up 30 points at 5am ET. 


Market Call: FLAT to upside
Date: 11 Mar 2013


Tuesday, 9 April 2013

9 Apr 2013 AMC


9 Apr 2013 AMC
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
16:20 ET Dow +59.98 at 14673.46, Nasdaq +15.61 at 3237.86, S&P +5.54 at 1568.61 :[BRIEFING.COM] Stocks settled just off their best levels of the session with the S&P 500 gaining 0.4%. 

After opening on a higher note, equities alternated between gains and losses until afternoon action sent the major indices to their highs. As a result, the Dow Jones Industrial Average notched a new record high while the S&P ended eight points away from its own all-time best. 

The materials sector ended as the top performer amid broad strength. Dow componentAlcoa (AA 8.39, 0.00) kicked off the first quarter reporting period with a bottom-line beat, but the company's revenue of $5.83 billion represented a 2.9% year-over-year decline, and fell short of the Capital IQ consensus estimate. 

Steelmakers rallied across the board as the Market Vectors Steel ETF (SLX 43.23, +1.41) surged 3.4% to record its second largest one-day advance of the year. Note that today's gains occurred after the steel ETF had surrendered more than 17.0% this year. 

Copper futures also saw strong gains after enduring recent weakness. The red metal rose 2.1% to $3.443 per pound. 

While materials, energy, and technology ended in the lead, three economically-sensitive groups finished among the laggards. 

The consumer discretionary sector lost ground as homebuilders and retailers weighed. The SPDR S&P Homebuilders ETF (XHB 29.27, -0.22) slipped 0.8%. 

Meanwhile, retailers saw weakness across the board as the SPDR S&P Retail ETF (XRT 70.30, -0.43) lost 0.6%. J.C. Penney (JCP 13.93, -1.94) sank 12.2% after the company's Board of Directors announced Chief Executive Officer Ron Johnson will be replaced by Mike Ullman, who has previously served as CEO. 

The Dow Jones Transportation Average also saw notable underperformance. The bellwether complex shed 0.3% as airlines were unable to take off with the broader market. United Continental (UAL 29.29, -0.76) lost 2.5%. Including today's decline, the Transportation Average is down almost 3.0% so far in April. 

Trading volume was a bit below average as 670 million shares changed hands on the floor of the New York Stock Exchange. 

Reviewing the day's sector performance, materials (+1.1%), technology (+0.8%), and energy (+0.8%) outperformed while utilities (-0.3%), consumer discretionary (-0.2%), and consumer staples (-0.1%) weighed. 

Today's economic data was limited to wholesale inventories. Inventories declined 0.3% in February after increasing a downwardly revised 0.8% (from 1.2%) in January. The Briefing.com consensus expected wholesale inventories to increase 0.5%. 

The drop in inventories was likely the result of better-than-expected sales growth. Wholesale sales jumped 1.7% in February after falling 0.8% in January. Wholesalers may not have been in position to maintain normal inventories levels given the size of the sales gain. 

Tomorrow, the weekly MBA Mortgage Index will be reported at 7:00 ET. In addition, March Treasury budget and the minutes from the March 20th meeting of the Federal Open Market Committee will be released at 14:00 ET. On the earnings front, Family Dollar (FDO 59.80, +0.41) is set to report its quarterly results ahead of the opening bell. 

The U.S. Treasury will hold a $21 billion reopening of 10-yr notes. ..NYSE Adv/Dec 1738/1250. ..NASDAQ Adv/Dec 1115/1353.


After Hours
17:47 ET PSMT +4.4%, HCSG +0.8%, HMA -11.5%, SEAC -10.0%, RLGY -6.9% following earnings/guidance :
Stocks settled just off their best levels of the session with the S&P 500 gaining 0.4%.
Today after the close the following companies reported earnings: ADTN, HCSG, PSMT, SEAC
Futures are higher after hours: S&P 500 futures are +0.46 from fair value of 1563.34 and Nasdaq100 futures are +1.95 from fair value of 2798.80.
Tomorrow morning before the open four economic reports are scheduled to be released: 1) Initial Claims (Consensus 365k), 2) Continuing Claims (Consensus 3058k), 3) Export Prices ex-ag., and 4) Import Prices ex-oil.
Tomorrow before the open the following companies are scheduled to report earnings: KMX, STZ, FDO, FAST, JKS, MSM, PGR, TITN


Commodities


Treasuries


Next Day In View 


Jason's Commentaries


Was right for the day for having a flat day last night. It's definitely very bullish at start of the day which went into another new high again for the Dow, however, the bullishness of the market faded off at the end of the trading session after 2pm ET. A very possible reason is that people are profit taking ahead of the FOMC minutes coming out at 2am ET on Wednesday. Last night we have the Materials and the Energy leading the market while the Utilities lagged the market by 0.3% last night. Possibly some profit taking after Utilities made such a huge gain recently. While we have the bulls and bears on par for Tuesday, We're likely to see some volatility in the market today. It's gonna be a tough call again..


Market Call:FLAT to downside
Date: 10 Mar 2013

8 Apr 2013 AMC


8 Apr 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 

Stock Market Update
16:10 ET Dow +48.23 at 14613.48, Nasdaq +18.39 at 3222.25, S&P +9.79 at 1563.07 : [BRIEFING.COM] Equities spent the bulk of today's session in negative territory before afternoon buying lifted the major averages out of the red. As a result, the S&P 500 settled higher by 0.6%.

Although stocks finished with gains, leadership was mixed, suggesting a certain level of indecision was present among market participants. Both consumer sectors ended ahead of the broader market with the defensively-oriented staples in the lead.

Staple stocks outperformed amid broad strength in beverage and tobacco producers.Coca-Cola (KO 40.86, +0.78) rose 2.0% and Philip Morris (PM 94.44, +1.72) advanced 1.9%.

Meanwhile, the growth-sensitive discretionary space outperformed on the back of homebuilders as the group rallied broadly. PulteGroup (PHM 19.73, +0.60) gained 3.1% while the broader SPDR S&P Homebuilders ETF (XHB 29.49, +0.58) added 2.0%.

Elsewhere in discretionary shares, quick-service restaurants ended on a mixed note.Yum! Brands (YUM 67.33, +0.36), who owns the KFC brand, was under early pressure amid concerns the Chinese bird flu outbreak will impact KFC sales. However, the stock was able to shake off the early weakness, and end higher by 0.5%.

In addition to consumer stocks, the Dow Jones Transportation Average outperformed, and settled with a gain of 0.9%. While most index components settled in the black, airlines displayed notable strength. Delta Air Lines (DAL 14.93, +0.54) and United Continental (UAL 30.05, +0.78) climbed 3.8% and 2.7%, respectively.

On the downside, the health care sector lagged after outperforming last week. BioCryst Pharmaceuticals (BCRX 1.92, +0.22) was an exception as the stock surged 12.9% after Chinese authorities approved the company's peramivir flu treatment in light of the recent bird flu outbreak.

In M&A news, Lufkin Industries (LUFK 87.96, +24.03) surged 37.6% after the company agreed to be acquired by General Electric (GE 23.12, +0.19) for $3.3 billion or $88.50 per share. The transaction price represents a 38% premium to Lufkin's Friday closing price.

Today's volume was well below average as less than 600 million shares changed hands on the floor of the New York Stock Exchange.

Reviewing the day's final sector performance, consumer staples (+1.1%), consumer discretionary (+1.1%), financials (+1.0%), and utilities (+0.8%) traded ahead of the broader market. Meanwhile, telecom (-0.5%), health care (+0.2%), and technology (+0.4%) lagged.

There was no notable economic data released today.

Tomorrow, February wholesale inventories will be reported at 10:00 ET.

The U.S. Treasury will auction off $32 billion in 3-yr notes. ..NYSE Adv/Dec 2069/933. ..NASDAQ Adv/Dec 1463/987.


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

Was totally wrong for Monday's call. Seems to me that market has totally forgot about Friday's disappointing NFP again. Market went up with 3 sectors gaining more than 1% last night, which are namely, Consumer Staples, Consumer Discretionary and Financials. Volumes were lower last night, slightly below 600million shares traded on the NYSE. There were definitely more bulls than bears last night. However, with Aloca announcing a better earnings result, the market is likely not to dip tonight. Not much movements in the Treasuries and Commodities last night.

Seems that we're gonna have a flat day tonight without any intervention from the economic news.  


Market Call: FLAT to upside
Date: 9 Mar 2013

Sunday, 7 April 2013

5 Apr 2013 AMC


5 Apr 2013 AMC
Market Summary


Market Internals


Leaders and Laggards


Technical Updates


Commentaries 


Stock Market Update
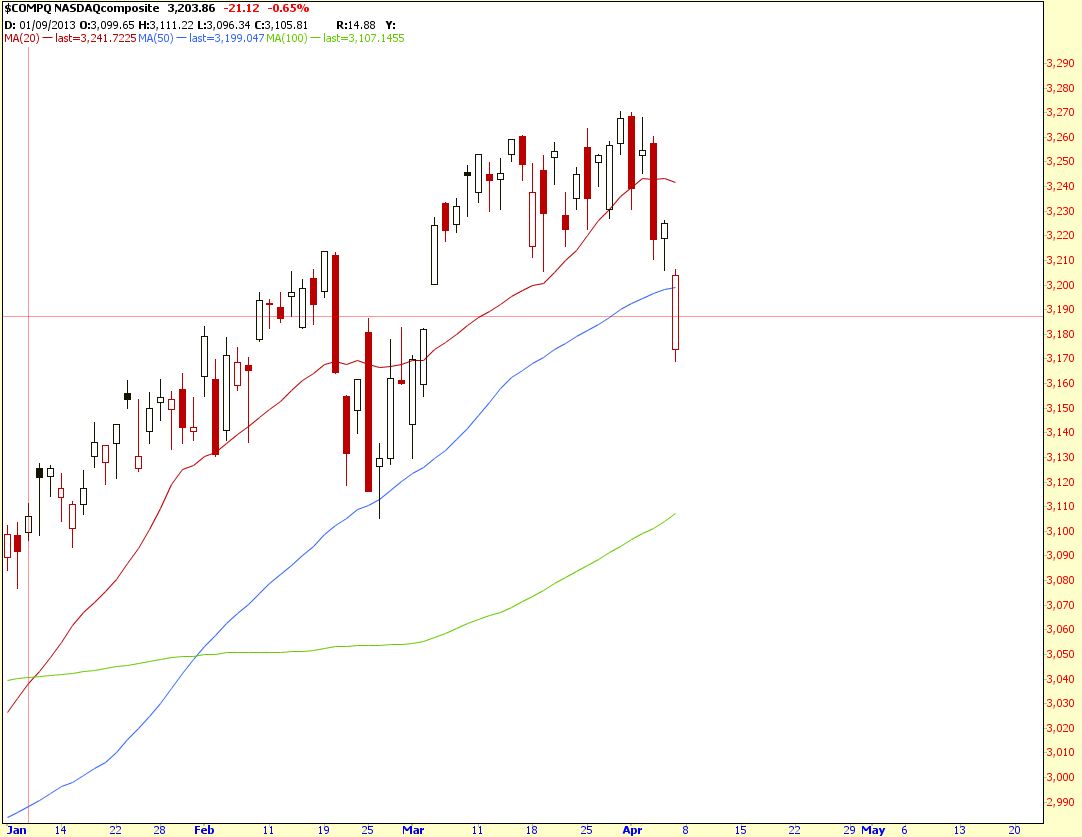
16:25 ET Dow -40.86 at 14565.25, Nasdaq -21.12 at 3203.86, S&P -6.70 at 1553.28 :[BRIEFING.COM] The major averages ended today's session with modest losses. The S&P 500 shed 0.4% while the tech-heavy Nasdaq lost 0.7%. 

The bulk of today's selling occurred at the open as three points of concern sent investors in search of safety. Headlines from Asia indicated North Korea has not toned down its war rhetoric and South Korean officials confirmed that the North has moved a pair of mid-range missiles to its east coast. 

In addition to the Korean concerns pressuring the broader market, disappointing second quarter guidance from F5 Networks (FFIV 73.21, -17.21) contributed to the relative weakness of the tech sector, which ended as the day's biggest laggard. 

While the two items pressured index futures in pre-market trade, a disappointing March nonfarm payrolls report ensured a sharply lower start to the cash session. 

Nonfarm payrolls added just 88,000 new jobs in March. That was down from an upwardly revised 268,000 (from 236,000) additions in February and was the smallest increase in jobs since June 2012. The Briefing.com consensus expected payrolls to add 192,000 jobs. 

Although the three headwinds caused the S&P 500 to start lower by 1.3%, the benchmark average notched its lows during the opening minute before spending the remainder of the day in a steady climb. 

The morning developments sparked a safety bid across the Treasury complex. As a result, the 10-yr yield fell to its lows before recovering three basis points into the close. However, Treasuries ended near their best levels of the week with the 10-yr yield down 17 basis points at 1.70%. 

The technology sector felt the brunt of today's selling pressure as F5 Networks' cautious guidance weighed on other networking companies. In addition, large cap tech names saw outsized losses as well. The largest tech component, Apple (AAPL 423.20, -4.52), lost 1.1%, and settled near its 52-week low. Notably, chipmakers underperformed in early trade, but finished the day ahead of the tech sector. The PHLX Semiconductor Index shed 0.5%. 

Although growth-oriented sectors were among the biggest decliners in early trade, those groups were able to climb off their lows. Financials, industrials, and materials outperformed the defensively-minded consumer staples and health care sectors. 

It should be noted that health care and consumer staples are the top performing sectors year-to-date, therefore some profit taking may have played a part in their underperformance today. 

On the upside, telecoms and utilities settled in the black. The SPDR Utilities Select Sector ETF (XLU 39.57, +0.17) added 0.4%, and was the top performing sector ETF as investors sought higher-yielding equities. 

While the broader market finished well off its lows, the Dow Jones Transportation Average was able to stage a stunning reversal. The bellwether complex was down as much as 2.2% at the start of the session before ending with a gain of 0.5%. Truckers were among the top index performers as Con-way (CNW 34.01, +0.96) advanced 2.9%. 

Looking back at the day's final sector performance, technology (-1.0%), consumer staples (-0.7%), and health care (-0.6%) were among the biggest laggards. Meanwhile, utilities (+0.4%), telecom (+0.4%), energy (UNCH), and industrials (-0.2%) outperformed. 

Reviewing today's remaining economic data, private nonfarm payrolls rose 95,000, but that was still well below consensus forecasts (210,000), and what was added in February (254,000). 

The unemployment rate dipped to 7.6% in March from 7.7% in February. The decline in the unemployment rate, however, was not due to job growth. The labor force participation rate dropped to levels not seen since the late 1970s and caused the unemployment rate to decline. If the labor force participation rate had remained at February levels, the unemployment rate would have increased to 7.9%. 

The U.S. trade deficit narrowed in February, dropping from $44.5 billion in January to $43.0 billion. The Briefing.com consensus expected the deficit to increase slightly to $44.7 billion. 

Consumer credit increased by $18.1 billion in February after increasing a downwardly revised $12.7 billion (from $16.2 billion) in January. The Briefing.com consensus expected consumer credit to increase by $14.0 billion. 

There is no economic news of note scheduled for a Monday release. 

On Tuesday, February wholesale inventories will be reported at 10:00 ET. 

Commodities


Treasuries


Weekly Analysis
Week 38


Technical Updates


Briefing's Commentaries


Week in Review: S&P 500 Alternates Between Gains and Losses 
On Monday, stocks saw little change at the start of the session with European markets shuttered for Easter Monday. However, that changed quickly once the March ISM Index was reported below expectations. The Index was reported at 51.3, which was its lowest reading since December, and it sent the major averages to their lows with cyclical sectors pacing the decline. The SPDR Industrial Select Sector ETF (XLI 40.97, -0.08) fell 1.2%. Transportation-related stocks did their part in pressuring the space as the Dow Jones Transportation Average ended lower by 1.5%. All 20 stocks comprising the Transportation Average settled in the red, and truckers were among the weakest performers. Ryder System (R 57.83, +0.33) and Landstar (LSTR 55.55, +1.24) saw respective losses of 1.8% and 2.4%. 

Equities spent the bulk of Tuesday's session near their highs before a late afternoon stumble dropped the S&P 500 back near the middle of its range. As a result, the benchmark average finished higher by 0.5%. Notably, the Russell 2000, which tracks small cap stocks, ended lower by 0.5% after losing more than 1.0% on Monday. The health care sector showed strength out of the gate with managed care stocks jumping after the Centers for Medicare and Medicaid Services said 2014 Medicaid Advantage and prescription drug benefit rates will increase by 3.3%. Dow component UnitedHealth Group (UNH 62.10, +0.07) gained 4.7%. 

Wednesday saw a steady decline and the S&P 500 settled lower by 1.1%. Notably, small cap stocks extended their recent weakness as indicated by a 1.7% decline in the Russell 2000. The Dow Jones Transportation Average finished lower by 1.3% with airlines leading the decline. Delta Air Lines (DAL 14.39, -0.36) and United Continental (UAL 29.27, -0.03) both lost 2.5%. Notably, Wednesday marked the third consecutive session which saw the bellwether complex end with a loss of at least 1.0%. 

On Thursday, equities began the day on a mixed note. The S&P 500 climbed higher out of the gate while Nasdaq slipped into the red, where it spent the majority of the session. After the prior day's selloff caused the benchmark average to slide 1.1%, a handful of Wednesday's underperformers began among the leaders. However, the early leadership did not hold into the afternoon as some defensive sectors began appearing atop the leaderboard. Counter-cyclical telecoms and utilities climbed throughout the day, and saw the largest gains. ..NYSE Adv/Dec 1437/1568. ..NASDAQ Adv/Dec 992/1447.

Next Week In View


Jason's Commentaries

Here's the extract of the NFP's numbers.
March nonfarm payrolls: 88K actual, 192K Briefing.com consensus, prior revised up to 268K
March nonfarm private payrolls: 95K actual, 210K Briefing.com consensus
Unemployment rate: 7.6% actual, 7.7% Briefing.com consensus, 7.7% prior
 
Coupled with the NFP, we also have news coming out from North Korea, having no intention to tone down on it's war-hunger. Like the saying goes, a hungry man is an angry man. So is Kim Jung Un. No country will support a military conflict. In this case, who on earth are willing to take in millions of refugees? Look at Russia, China and South Korea. None of the countries are able to provide for these North Koreans if there is a war. Unless the US are willing to shoulder the responsibility, else this 'war' will end pretty miserably. 

 Jacobs Technology, Inc., Tullahoma, Tenn., is being awarded a $128,450,000 indefinite- delivery/indefinite-quantity contract modification (FA9200-12-D-0085).  The total estimated cumulative face value of the contract is $263,950,000.  This modification provides for the exercise of an option for additional diverse engineering, technical and acquisition support services being provided under the basic contract.  Work will be performed at Eglin Air Force Base, Fla., with an expected completion date of April 19, 2014.  This is an IDIQ contract with multiple funding appropriations at the task order level; the contract is not multiyear.  Type of appropriation is fiscal 2012 and 2013.  The contracting activity is AFTC/PZZ, Eglin Air Force Base, Fla.  This contract involves foreign military sales. 


 Friday was really one hell of a ride. Non-farm payrolls came in way under expectation and caused the market to start with a -1% loss. Futures sunk tremendously before market open. However, that was way oversold. If the market would have chill for a moment, and open the market low, but not so low, we wouldn't have seen such a huge rebound. Most stocks opened near a 1% loss as well, with Techology and Consumer being the biggest laggards. While energy and utilities managed to close with a gain. I would say it was more of a bullish day than bearish day. If we were to discount the first candle, we're actually up. Nasdaq composite managed to fought back a huge portion of its losses and Dow managed to end flat for Friday.

While looking back at the internals, we're actually having a flat Friday, and I did mention it's gonna be a roller coaster ride and I'm right on that. Dow found a support at the 14450 level and bouncing of that level all the way till market close. I believe those who went long on Friday will likely start taking profit off ahead of the earnings season. While there are many notable movement in the commodities market. Gold made a 1.89% and Silver made a 1.92% gain ending Friday's trading session. Also take note on the movement on the 30y, having to gained a 1% on Friday is not a very bullish thing to happen.

As we're looking in the longer term, I'm expecting the market to be sideways to the downside ahead of the earnings seasons and the market is starting to be defensive. The momentum and volatility will likely to kick in on the second week of earnings seasons. If the first 2 week suck... We're gonna start May early. Happy shorting guys =D


Market Call: Down
Date:  8 Apr 2013