Tuesday, 18 September 2012

18 Sep 2012 AMC


18 September 2012
Market Summary


I was almost right on the market call yesterday. It was almost totally flat. the first half of the trading day was spent in the negative region. The TRIN was at in the bearish region for the entire trading sessions. However, the VIX fell by 2.81% yesterday. As mentioned in the last DMA, the bulls and bears are going to have a fierce fight yesterday and it seems that the bulls won the day. 

There will be quite a bit of housing data coming out today. I believe the market is pricing into the data today. 

Yesterday conrad and the few trainers had an very interesting discussion. It's about whether market will crash in september... September is famous for market crashes. Con said it might happen. But... I highly doubt so... If it's going to happen... it's gonna happen after the presidential election after Nov 6. 


Market Internals


Volumes were relatively weak yesterday. Most people are staying on the sidelines again, awaiting some positive catalyst to break into the higher highs. Possibly, the market is waiting for Draghi's speech again on Thursday. It was really a flat day. The UVOL and DVOL were almost the same! Same goes for the ADVN and DECN. 

Leaders and laggards


It's flat...

Technical Updates


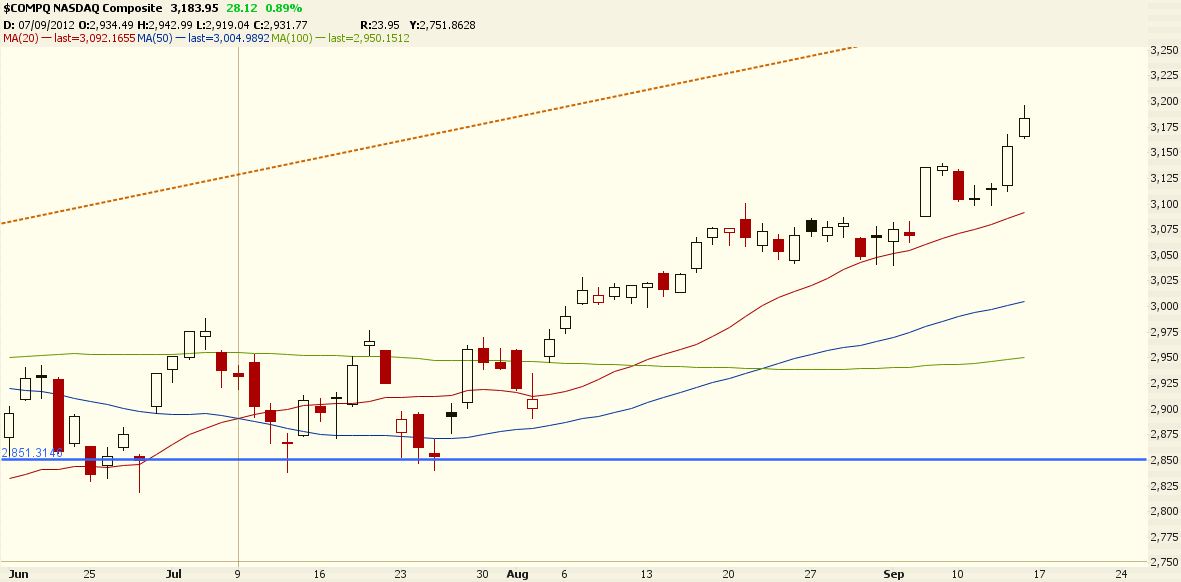
All 3 indices is falling into a stalled pattern already. Perhaps the market is not convinced that QE3 will be beneficial for the economy?? 


Commentaries

Stock Market Update
16:10 ET Dow +11.54 at 13569.82, Nasdaq -0.87 at 3177.8, S&P -1.87 at 1459.32 :[BRIEFING.COM] Today's session was mostly uneventful as equities remained near their opening levels throughout the day. The major averages showed some divergence as the S&P 500 shed 0.2% while the Dow added 0.1%.

Stocks within the consumer staples sector were the top performer of the day. Within the group, Energizer (ENR 75.22, +7.30) surged 10.7% after announcing preliminary results of a comprehensive review of the company's cost structure. As a result of the review, Energizer expects annualized cost savings of $175-200 million. Beverage and cigarette stocks were also on the rise within the defensive sector. Coca-Cola (KO 38.62, +0.27) and British American Tobacco (BTI 104.81, +2.70) ended higher by 0.9% and 2.6%, respectively.

The Dow Jones Transportation Average slipped 1.1% as it trailed the broader market. Disappointing guidance from FedEx (FDX 86.55, -2.73) spilled over to other group components as all twenty names within the transportation average traded lower. Airlines showed the biggest weakness as Delta (DAL 8.96, -0.27) and United Continental (UAL 19.27, -0.46) both fell near 2.5%. Shipping stocks were also pressured with Matson (MATX 21.84, -0.43) and Overseas Shipholding Group (OSG 6.76, -0.09) ending lower by 1.9% and 1.5%, respectively.

Technology stocks have traded mostly in-line with the broader market. AMD (AMD 3.62, -0.39) slumped 9.7% after Senior Vice President and Chief Financial Officer, Thomas Seifert announced his resignation. The company announced that Devinder Kumar will serve as interim Chief Financial Officer while a search for a replacement takes place.

Meanwhile, OCZ (OCZ 4.13, -0.33) slid 7.4% after Chief Executive Officer, Ryan Peterson resigned. The board of directors has appointed Amex Mei as interim Chief Executive Officer. The change at the top resulted in several analysts moving their ratings. Craig Hallum upgraded the stock from ‘hold' to ‘buy' while Stifel Nicolaus downgraded OCZ from ‘buy' to ‘hold.'

Elsewhere, F5 Networks (FFIV 108.62, +4.16) jumped 4.0% after Piper Jaffray commented on the company's attractive valuation, and said that the network provider is likely to beat earnings estimates. Other networking names finished lower withCisco Systems (CSCO 19.04, -0.11) and Juniper Networks (JNPR 18.94, -0.43) slipping 0.6% and 2.2%, respectively.

For-profit education stocks were broadly higher today. Career Education (CECO 4.09, +0.27) and Corinthian Colleges (COCO 2.84, +0.14) added 7.1% and 5.2%, respectively. The advances did not appear to be news-driven as other education listings also made notable advances. Strayer Education (STRA 70.82, +2.85) andBridgeport Education (BPI 11.64, +0.42) both gained near 4.0%.

The current account deficit for the second quarter totaled $117.4 billion, which was lower than the $126.8 billion deficit that had been broadly anticipated.

The July net long-term TIC flows print indicated a $67 billion inflow of foreign capital into U.S. denominated assets.

Lastly, the NAHB Housing Market Index for September registered a reading of 40, which was ahead of prior month's 37, and better than the reading of 38 that had been expected among economists polled by Briefing.com.

In tomorrow's economic data, the weekly MBA Mortgage Index will be reported at 7:00 ET, while housing starts and building permits will be released at 8:30 ET. Lastly, existing home sales will be announced at 10:00 ET. ..NYSE Adv/Dec 1335/1681. ..NASDAQ Adv/Dec 1203/1260.
After Hours
16:50 ET No notable movers this afternoon on earnings/guidance :
Today's session was mostly uneventful as equities remained near their opening levels throughout the day. The major averages showed some divergence as the S&P 500 shed 0.2% while the Dow added 0.1%. 
Today after the close no notable companies reported earnings. 
Futures are mixed after hours: S&P 500 futures are +0.69 from fair value of 1452.51 and Nasdaq100 futures are -0.55 from fair value of 2850.55. 
Tomorrow morning before the open two economic reports are scheduled to be released: 1) MBA Mortgage Index, and 2) Housing Starts (Consensus 770k) and Building Permits (Consensus 800k). 
Tomorrow before the open the following companies are scheduled to report earnings: ASNA, AZO, CBRL, GIS

Commodities


Coffee made some gain back from yesterday's fall of 3%. 


Treasuries 


It seems that there are some sell off in the bonds again. I believe the money is moving into the risk market again. I believe there's still some upside for the market to go. I'm still bull in a bearish economy.

Market Call:UP
Date: 19 SEP 2012

Monday, 17 September 2012

17 Sep 2012 AMC

17 September 2012
Market Summary


Bingo... Days like this are easier to speculate... market corrected a little bit on a monday.. However, I believe the bullishness will likely to continue either from Tuesday or Wednesday onwards.. other news to note is that the Empire Manufacturing Survey registered its worst reading since Apr 2009... somthing to be concerned about..

Market Internals


Looking at the internals, the volume went back to 665millions shares traded in the NYSE, while UVOL outpaced DVOL by more than double, DECN outpaced ADVN by around 2 times... a typical profit taking day... I'm definitely staying bull for the week... Provided Mario Draghi keep his mouth clean... 


Leaders and laggards


Financials and the materials were hammered down yesterday, dragging down all other indices.. the financials got sold off yesterday without much clear reason... but the materials are being dragged down by a series of downgrades in the steel industry....

Technical Updates


Looking at all 3 indices... they are starting to retrace a little after the breakout... I reckon the correction should continue for 1 more day or so till the 3 indices found a support to bounce on before making new highs..


Commentaries


Stock Market Update
16:10 ET Dow -40.27 at 13558.28, Nasdaq -5.28 at 3178.67, S&P -4.58 at 1461.19 :[BRIEFING.COM] Stocks began today's session on a negative note after the September Empire Manufacturing Survey registered its worst reading since April 2009. The bearish sentiment was then extended as unfounded rumors of tapping into the strategic petroleum reserve sent the major averages to fresh session lows. As a result, the S&P 500 ended lower by 0.3%. 

Healthcare stocks outperformed the broader market on strength in biotech companies. The iShares Nasdaq Biotechnology ETF (IBB 143.15, +1.39) advanced 1.0% asGilead Sciences (GILD 65.80, +3.78) added 6.1% after positive comments were made by analysts before the open. Meanwhile, Spectrum Pharmaceuticals (SPPI 12.91, +0.90) and Onyx Pharmaceuticals (ONXX 81.26, +4.59) gained between 6.0% and 7.5%. 

In M&A news, medical equipment supplier, IRIS (IRIS 19.54, +6.12) surged 45.6% after announcing that the company will be acquired by Danaher (DHR 54.84, +0.08) for $19.50 per share. The purchase price represents a 45.3% premium to IRIS' Friday closing price of $13.42. Following the acquisition, Feltl & Co downgraded shares of IRIS from ‘buy' to ‘hold.' Elsewhere, Complete Genomics (GNOM 3.02, +0.35) jumped 13.1% after the company entered into a definitive merger agreement with China-based BGI-Shenzhen. Per the agreement, a wholly-owned U.S. subsidiary of BGI-Shenzhen will launch a tender offer to purchase all outstanding shares of GNOM for $3.15 per share, representing an 18.0% premium to GNOM's Friday closing price of $2.67. 

The Dow Jones Transportation Average slipped 1.5% as it underperformed the broader market. Within the bellwether group, only UPS (UPS 74.23, +0.55) and CSX Corp (CSX 23.26, +0.10) managed to stay marginally positive. Airline stocks were generally lower after Southwest Airlines (LUV 9.05, -0.02) and Delta (DAL 9.23, -0.04) raised roughly 10% of their round trip fares by $10. The two carriers both shed near 0.3%. Trucking and railroad stocks also showed considerable weakness as Con-way (CNW 29.22, -1.33) and Kansas City Southern (KSU 81.24, -2.39) ended lower by 4.4% and 2.9%, respectively. 

Shares of major financials showed weakness after last week's broad rally. The SPDR Financial Select Sector ETF (XLF 16.13, -0.15) slipped 0.9% as most major names posted losses in the neighborhood of 1.0%. Bank of America (BAC 9.30, -0.25) andMorgan Stanley (MS 17.80, -0.44) both fell near 2.5%, while JPMorgan Chase (JPM 41.19, -0.38) and Goldman Sachs (GS 119.90, -1.46) lost near 1.0% each. 

The materials sector was the weakest performer. The SPDR Materials Select Sector ETF (XLB 37.76, -0.59) slumped 1.5% as steel producers lagged after a series of downgrades. AK Steel (AKS 5.53, -0.34), Cliffs Natural Resources (CLF 42.36, -3.19),Reliance Steel & Aluminum (RS 54.99, -2.67), and United States Steel (X 21.31, -1.04) all posted losses between 4.5% and 7.0% after JP Morgan downgraded shares of the steelmakers from ‘overweight' to ‘neutral.' 

Looking at tomorrow's earnings, FedEx (FDX 89.28, -0.87) will report its first quarter results before the bell. The company will be in focus after it recently lowered its earnings guidance to $1.37-1.43 from the original forecast of $1.45-1.60 per share. 

The Empire Manufacturing Survey for September registered a reading of -10.4, which was down from the prior month's reading of -5.9. Economists polled by Briefing.com had expected that the Survey would rise to -3.0.

A handful of economic data points will be reported tomorrow. The current account balance will be released at 8:30 ET, while net long-term TIC flows and the NAHB Housing Market Index will be reported at 9:00 ET and 10:00 ET, respectively. ..NYSE Adv/Dec 936/2089. ..NASDAQ Adv/Dec 945/1500.


After Hours
16:40 ET No notable movers on earnings/guidance :
Stocks began today's session on a negative note after the September Empire Manufacturing Survey registered its worst reading since April 2009. The bearish sentiment was then extended as unfounded rumors of tapping into the strategic petroleum reserve sent the major averages to fresh session lows. As a result, the S&P 500 ended lower by 0.3%.
Today after the close no companies reported earnings.
Futures are lower after hours: S&P 500 futures are -0.33 from fair value of 1454.23 and Nasdaq100 futures are -2.07 from fair value of 2849.32.
Tomorrow morning before the open two economic reports are scheduled to be released: 1) Current Account Balance (Consensus -126.8B), and 2) Net Long-Term TIC Flows.
Tomorrow before the open the following companies are scheduled to report earnings: FDX, MANU, SHF

Commodities


By 12.44pm SG time, cotton and lean hogs were making some significant movement... However, the biggest movement of all is made by coffee, which fell 3%. Coffee is now making a retracement. If the fall continues... I'm gonna long SBUX...

Treasuries 


For the treasuries, there's some significant profit taking yesterday... but i believe the bond yield is going to come down lower due to the QE3.

There's not much data coming out today so it should be a rather good trading day.. The only catalyst for a movement will only be a profit taking sentiment after such sharp rises.... However, i believe the some profit taking sentiment is still present in the market now, however, since the financials are being hammered down yesterday without much reasons, i believe that the market will be scooping them up today, and also with finding a intraday support on the indices will be provide some upside. The bulls and the bears are likely to have a tough fight today... So i'm gonna call the market Flat to the downside =D


Market Call: FLAT(to the downside)
Date: 17 SEP 2012

Sunday, 16 September 2012

14 Sep 2012 AMC + Weekly outlook


14 September 2012
Market Summary


As expected..the market is bullish as after QE3 announced. But... I didn't enter any trade!!! %$^#$^$^%# I shall wait for the next retracement before taking my position.

Kinda surprising that VIX went up together with the indices...

Market Internals


A very rare sight to see the volumes kissing 900 million shares traded on the NYSE nowadays...I presume people are finally getting off sidelines and decide to take their positions in the market... With the internals slightly bullish only... I doubt it was a total bullish day on Friday..

Leaders and laggards


With Energy and Materials leading the number, but... the Telco went down by 2%! I'm getting bull on financials already... =D 


Technical Updates


I'm going to wait for the retracement to make an entry! these are obvious breakouts!!!


Commentaries

Stock Market Update
16:15 ET Dow +53.51 at 13598.55, Nasdaq +28.12 at 3183.95, S&P +5.78 at 1465.77 : [BRIEFING.COM] Today's session started on a positive note as stocks appeared poised for a second day of broad post-FOMC gains. However, the major averages marked their respective session highs during the first hour of trade and headed lower since. The Nasdaq was able to outperform as it held the bulk of its gains throughout the day. Afternoon selling pressure increased slightly after Egan Jones lowered the credit rating of the U.S. from ‘AA' to ‘AA-.‘ Looking at the major indices, the Nasdaq led the way with a 0.9% gain while the Dow and S&P 500 added 0.4% each.

Financial stocks continued to rally after yesterday's news. The SPDR Financial Select Sector ETF (XLF 16.28, +0.13) closed higher by 0.8% as most major names advanced. The ETF has seen a 4.0% rally since the Fed's announcement. Bank of America (BAC 9.55, +0.15), Morgan Stanley (MS 18.24, +0.34), and Wells Fargo(WFC 36.13, +0.58) all posted gains near 1.5%. European financials were also in focus as monetary easing in the U.S. carries global implications. Barclays (BCS 14.81, +0.46), Deutsche Bank (DB 44.28, +1.41), and UBS (UBS 13.48, +0.46) all gained near 3.5%.

Stocks within the defensive telecom space were lower as the sector underperformed the broader market. Verizon (VZ 44.53, -1.05) and AT&T (T 37.26, -0.89) both slid near 2.3%. The two telecom giants saw relative weakness after Stifel Nicolaus downgraded both stocks from ‘buy' to ‘hold.' With the majority of the sector sliding,Sprint (S 5.26, +0.06) and MetroPCS (PCS 10.63, +0.15) were able to buck the trend and post respective gains of 1.2% and 1.4%.

AK Steel (AKS 5.87, -0.57) slumped 8.9% after lowering its third quarter guidance on expectations of a 7% quarterly decrease in the price of steel. Following the announcement, AK Steel was downgraded by Credit Agricole. Other steelmakers continued to rally along with producers of basic materials. Steel Dynamics (STLD 13.01, +0.61) added 4.9%, while Cliffs Natural Resources (CLF 45.55, +2.37) advanced 5.5%.

Office supply retailer OfficeMax (OMX 8.15, +1.04) surged 14.6%. Earlier, the company confirmed it would extinguish a non-recourse liability which is related to Lehman-backed timber notes. Because of this, OMX will recognize a non-cash, pre-tax gain of $671.1 million in the third quarter. Today's buying lifted the stock to a 21.2% gain on the week. Meanwhile, peer Staples (SPLS 12.21, +0.25) advanced 2.1% following recent rumors of a possible private equity buyout.

Western Digital (WDC 41.06, -1.51) fell 3.6% after lowering its revenue guidance for the first quarter. Shares of the hard drive producer have been in a downtrend since the stock reached a 2-year high at $45.48 on August 17.

Social media stocks were on the rise. Facebook (FB 22.00, +1.28) jumped 6.2% following reports which suggested the company is set to introduce a real-time ad program. FB's peer Zynga (ZNGA 3.18, +0.22) surged 7.4% after the company hired an online-gambling executive, Maytal Olsha as its new Chief Operating Officer. Elsewhere, Groupon (GRPN 5.27, +0.51) soared 10.7% as the stock of the online deals site continues rebounding after reaching an all-time low of $4.00 on September 4.

A slew of economic data points hit the wires today.

Consumer prices increased by 0.6% during August, which was in-line with the 0.6% gain that had been generally expected. Core prices increased by 0.1%, which was slightly short of the 0.2% increase expected by economists polled by Briefing.com.

Separately, retail sales rose during August by 0.9%, which was better than the 0.7% increase that had been broadly expected. The prior month's reading was revised down to show an increase of 0.6%. Excluding autos, retail sales rose by 0.8%, which was in-line with the Briefing.com consensus call.

Industrial production decreased during August by 1.2%, which was worse than the 0.2% decrease that had been widely expected. The reading followed the revised 0.5% increase experienced in the prior month. Capacity utilization hit 78.2%, which was worse than the 79.2% that had been expected and down from the revised prior month reading of 79.2%.

The preliminary University of Michigan Survey for September came in at 79.2, which was ahead of the prior month's 74.3, and better than the reading of 73.5 that had been widely expected.

Lastly, monthly business inventory data for July showed an inventory build of 0.8% for the month which was slightly above the 0.4% that had been expected.

On Monday, the Empire Manufacturing Index will be released at 8:30 ET.

Week in Review: Focus Turns to Federal Reserve as QE3 is Launched 
Monday's session was mostly uneventful, as the range-bound trading day concluded with a late-afternoon push to session lows. The major averages saw a notable divergence as the Dow slipped 0.4% while the S&P 500 and Nasdaq slid 0.6% and 1.0%, respectively. Airlines were stronger as United Continental (UAL 20.06, -0.03) advanced 1.8%.

On Tuesday, equities were broadly higher throughout the day before late afternoon selling sent the Nasdaq into negative territory. The dip also pushed the other indices lower, but they were able to hold most of their gains. The Dow finished higher by 0.5% while the Nasdaq ended flat. Groupon (GRPN 5.27, +0.51) finished higher by 8.0% after a reported increase in site traffic during the month of August.

On Wednesday, stocks started the day higher but were only able to hold a portion of their gains in a session which saw two pullbacks to the unchanged line. After spending most of the day in the black, the S&P 500 ended higher by 0.2%. The Dow Jones Transportation Average, which has been on a steady rise over the past week, added 0.8%.

Thursday's session was highlighted by a risk rally sparked by the Federal Reserve's decision to increase policy accommodations by purchasing additional agency mortgage-backed securities at a pace of $40 billion per month. The program is open-ended by design, which allows the Federal Reserve to terminate it once the employment picture shows substantial improvement. The S&P 500 was the best performing index and it settled higher by 1.6%. Financials rallied on the news andBank of America (BAC 9.55, +0.15) led all majors with an advance of 4.8%. ..NYSE Adv/Dec 2104/948. ..NASDAQ Adv/Dec 1616/848.


Commodities


Treasuries 


And guess what happens in the T bonds... the 5 year,10 year and 30 year rallied... BIG TIME. I believe the bond traders and investors are positioning themselves in the market in speculation that the Fed is going to push the bond prices up..

Week 32


Technical Updates


Commentaries

Weekly Wrap 
Dow +53.51 at 13598.55, Nasdaq +28.12 at 3183.95, S&P +5.78 at 1465.77
Today's session started on a positive note as stocks appeared poised for a second day of broad post-FOMC gains. However, the major averages marked their respective session highs during the first hour of trade and headed lower since. The Nasdaq was able to outperform as it held the bulk of its gains throughout the day. Afternoon selling pressure increased slightly after Egan Jones lowered the credit rating of the U.S. from ‘AA' to ‘AA-.‘ Looking at the major indices, the Nasdaq led the way with a 0.9% gain while the Dow and S&P 500 added 0.4% each. 
Financial stocks continued to rally after yesterday's news. The SPDR Financial Select Sector ETF (XLF 16.28, +0.13) closed higher by 0.8% as most major names advanced. The ETF has seen a 4.0% rally since the Fed's announcement. Bank of America (BAC 9.55, +0.15), Morgan Stanley (MS 18.24, +0.34), and Wells Fargo (WFC 36.13, +0.58) all posted gains near 1.5%. European financials were also in focus as monetary easing in the U.S. carries global implications. Barclays (BCS 14.81, +0.46), Deutsche Bank (DB 44.28, +1.41), and UBS (UBS 13.48, +0.46) all gained near 3.5%.

Stocks within the defensive telecom space were lower as the sector underperformed the broader market. Verizon (VZ 44.53, -1.05) and AT&T (T 37.26, -0.89) both slid near 2.3%. The two telecom giants saw relative weakness after Stifel Nicolaus downgraded both stocks from ‘buy' to ‘hold.' With the majority of the sector sliding, Sprint (S 5.26, +0.06) and MetroPCS (PCS 10.63, +0.15) were able to buck the trend and post respective gains of 1.2% and 1.4%.

AK Steel (AKS 5.87, -0.57) slumped 8.9% after lowering its third quarter guidance on expectations of a 7% quarterly decrease in the price of steel. Following the announcement, AK Steel was downgraded by Credit Agricole. Other steelmakers continued to rally along with producers of basic materials. Steel Dynamics (STLD 13.01, +0.61) added 4.9%, while Cliffs Natural Resources (CLF 45.55, +2.37) advanced 5.5%.

Office supply retailer OfficeMax (OMX 8.15, +1.04) surged 14.6%. Earlier, the company confirmed it would extinguish a non-recourse liability which is related to Lehman-backed timber notes. Because of this, OMX will recognize a non-cash, pre-tax gain of $671.1 million in the third quarter. Today's buying lifted the stock to a 21.2% gain on the week. Meanwhile, peer Staples (SPLS 12.21, +0.25) advanced 2.1% following recent rumors of a possible private equity buyout.

Western Digital (WDC 41.06, -1.51) fell 3.6% after lowering its revenue guidance for the first quarter. Shares of the hard drive producer have been in a downtrend since the stock reached a 2-year high at $45.48 on August 17.

Social media stocks were on the rise. Facebook (FB 22.00, +1.28) jumped 6.2% following reports which suggested the company is set to introduce a real-time ad program. FB's peer Zynga (ZNGA 3.18, +0.22) surged 7.4% after the company hired an online-gambling executive, Maytal Olsha as its new Chief Operating Officer. Elsewhere, Groupon (GRPN 5.27, +0.51) soared 10.7% as the stock of the online deals site continues rebounding after reaching an all-time low of $4.00 on September 4.

A slew of economic data points hit the wires today.

Consumer prices increased by 0.6% during August, which was in-line with the 0.6% gain that had been generally expected. Core prices increased by 0.1%, which was slightly short of the 0.2% increase expected by economists polled by Briefing.com.

Separately, retail sales rose during August by 0.9%, which was better than the 0.7% increase that had been broadly expected. The prior month's reading was revised down to show an increase of 0.6%. Excluding autos, retail sales rose by 0.8%, which was in-line with the Briefing.com consensus call.

Industrial production decreased during August by 1.2%, which was worse than the 0.2% decrease that had been widely expected. The reading followed the revised 0.5% increase experienced in the prior month. Capacity utilization hit 78.2%, which was worse than the 79.2% that had been expected and down from the revised prior month reading of 79.2%.

The preliminary University of Michigan Survey for September came in at 79.2, which was ahead of the prior month's 74.3, and better than the reading of 73.5 that had been widely expected.

Lastly, monthly business inventory data for July showed an inventory build of 0.8% for the month which was slightly above the 0.4% that had been expected.

On Monday, the Empire Manufacturing Index will be released at 8:30 ET.

Week in Review: Focus Turns to Federal Reserve as QE3 is Launched 

Monday's session was mostly uneventful, as the range-bound trading day concluded with a late-afternoon push to session lows. The major averages saw a notable divergence as the Dow slipped 0.4% while the S&P 500 and Nasdaq slid 0.6% and 1.0%, respectively. Airlines were stronger as United Continental (UAL 20.06, -0.03) advanced 1.8%.

On Tuesday, equities were broadly higher throughout the day before late afternoon selling sent the Nasdaq into negative territory. The dip also pushed the other indices lower, but they were able to hold most of their gains. The Dow finished higher by 0.5% while the Nasdaq ended flat. Groupon (GRPN 5.27, +0.51) finished higher by 8.0% after a reported increase in site traffic during the month of August.

On Wednesday, stocks started the day higher but were only able to hold a portion of their gains in a session which saw two pullbacks to the unchanged line. After spending most of the day in the black, the S&P 500 ended higher by 0.2%. The Dow Jones Transportation Average, which has been on a steady rise over the past week, added 0.8%.

Thursday's session was highlighted by a risk rally sparked by the Federal Reserve's decision to increase policy accommodations by purchasing additional agency mortgage-backed securities at a pace of $40 billion per month. The program is open-ended by design, which allows the Federal Reserve to terminate it once the employment picture shows substantial improvement. The S&P 500 was the best performing index and it settled higher by 1.6%. Financials rallied on the news and Bank of America (BAC 9.55, +0.15) led all majors with an advance of 4.8%.


Next Week in View


Not much heavy data coming out for the US next week... on Wednesday, the housing data is coming out, on Thursday, Mario Draghi is speaking, Philly Fed is coming out..

I believe the coming week will be flat but to the upside week... the bullish sentiment will tend to continue...


Market Call: 17 Sept
Date: DOWN

Market Call(Weekly): UP

Date: Week 38