Thursday, 25 April 2013

24 Apr 2013 AMC


24 Apr 2013 AMC
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
16:15 ET Dow -43.16 at 14676.3, Nasdaq +0.32 at 3269.65, S&P +0.01 at 1578.79 :[BRIEFING.COM] The major averages ended today's session on a mixed note. The Dow shed 0.3% while Nasdaq and S&P 500 ended flat. 

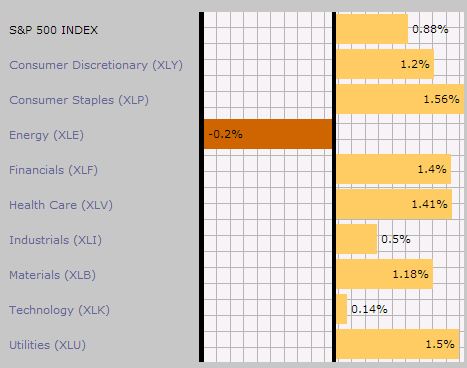
Defensively-oriented groups were among the leaders of the first-quarter market rally. Today, however, three defensive sectors finished firmly lower after top-line results from major components failed to justify the considerable first-quarter gains. 

Consumer staples, telecom, and health care sectors all registered losses of at least 1.7%. 

Consumer staples lagged after Procter & Gamble (PG 77.12, -4.82) reported revenue below the Capital IQ consensus estimate. In addition, the company issued cautious fourth quarter earnings and revenue guidance. 

Elsewhere, telecoms were pressured by AT&T (T 37.04, -1.96) after the carrier missed on revenue. In addition, Citigroup and Morgan Stanley both downgraded the stock. 

The top performing sector of the year, health care, declined steadily throughout the day after Amgen (AMGN 104.93, -7.83), Edwards Lifesciences (EW 64.60, -18.21), and Eli Lilly (LLY 56.05, -2.28) all reported below-consensus revenues. 

In addition, Amgen's 6.9% decline weighed on biotech companies as iShares NasdaqBiotech ETF (IBB 169.67, -5.11) settled lower by 2.9%. 

The underperformance of biotechnology names kept the Nasdaq near its flat line even as technology stocks displayed relative strength. Apple (AAPL 405.46, -0.67) ended little changed after beating on earnings and revenue. Although the company's results surprised to the upside, its gross margin was reported on the low end of estimates. In addition, Apple lowered its third quarter revenue and gross margin guidance below consensus. Also of note, the company raised its quarterly dividend by 15%. However, the increased capital return program will be funded by taking on debt rather than repatriating its cash, which would be subject to U.S. corporate taxes. 

Chipmakers were some of the top performing tech components after Broadcom (BRCM 35.08, +2.11) topped its earnings and revenue estimates. Meanwhile, the broader PHLX Semiconductor Index rose 1.3%. 

While the best performing sectors of the first quarter ended firmly lower, three notable Q1 laggards ended in the lead. Energy, industrials, and materials all settled with gains of at least 1.0%. 

The economically-sensitive groups were aided by a rebound in commodities. Crude oil ended higher by 2.8% at $91.63 per barrel while copper rose 2.4% to $3.166 per pound, and gold climbed 1.5% to $1429.70 per troy ounce. 

Industrials received added support from defense stocks after General Dynamics (GD 71.73, +4.63) beat on earnings. Meanwhile, the broader PHLX Defense Index advanced 1.6%. 

Today's volume was right in-line with its 200-day moving average as 706 million shares traded hands on the floor of the New York Stock Exchange. 

Durable goods orders continued their streak of sizable up-and-down movements in March. Orders fell 5.7% after increasing a downwardly revised 4.3% (from 5.6%) in February. The Briefing.com consensus expected orders to fall 3.1%. 

The wild swings in orders over the last few months have been the result of big moves in aircraft orders. In March, total aircraft orders -- defense and nondefense -- fell 43.5% after increasing 65.0% in February. 

Excluding transportation, orders fell 1.4% after dropping a downwardly revised 1.7% (from -0.7%) in February. The consensus expected these orders to remain flat. 

The weekly MBA Mortgage Index rose 0.2% to follow last week's increase of 4.8%. 

Tomorrow, weekly initial and continuing claims will be reported at 8:30 ET. Among earnings of note, 3M (MMM 107.87, +0.48), Exxon Mobil (XOM 89.43, +0.13), and UPS(UPS 83.50, -0.24) will report their results before the opening bell. 

The U.S. Treasury will auction $29 billion in 7-yr notes. ..NYSE Adv/Dec 1971/1017. ..NASDAQ Adv/Dec 1377/1056.

After Hours
17:59 ET AKAM +16.1%, FIO +12.2%, INFN +11.9%, CTXS -12.4%, INTU -9.8% following earnings/guidanc :

The major averages ended today's session on a mixed note. The Dow shed 0.3% while Nasdaq and S&P 500 ended flat. 
Other notable movers on earnings/guidance: AKAM +16.1%, FIO +12.2%, INFN +11.9%, ASGN +10.3%, JAH +9.3%, AVG +7.8%, ANGI +6.9%, BYI +6.5%, CAKE +4.9%, CLF +4.5%, NOW +4.2%, ISSC +4.2%, WDC +4.0%, XLNX +1.3%, CTXS -12.4%, INTU -9.8%, MLNX -9.3%, ZNGA -8.9%, EQIX -7.6%, QCOM -6.9%, RIMG -5.4%, VAR -4.9%, TSCO -4.3%, BVSN -1.9%, TEX -1.8%, AFL -1.3%, FLS -0.5%, 

Today after the close the following companies reported earnings: XLNX, CMRE, FFIV, HRC, LOGI, LRCX, LSI, MLNX, PMTC, RJF, SUSQ, SYK, SYMM, TCBI, TER, VAR, WDC, COHR, OTEX, CCI, GGG, NEU, FFBC, RYL, ALGT, BRKL, CDNS, CMO, CTXS, CVTI, DRE, FICO, FIO, ISIL, KEX, KNX, MKSI, NOW, QCOM, TSCO, BYI, SIGI, SYA, AFL, HMN, INFN, ZNGA, AIZ, AKAM, ARRS, BDN, EFX, ORLY, PDH, SRCL, TBI, TQNT, TYL, AHL, LPS, MRH, PACR, CLF, SCI, ANGI, AWH, CAP, DAVE, EQIX, STMP, TAL, ASGN, GRT, JAH, TILE, BAS, OIS, TEX, ARII, CAKE, CLW, CROX, WCN, WIRE, AVG, CLGX, COG, FLS, IPCM, ITMN, AEGN, TWI, CHDN, CSGP, MTSN, STNR, WLL, XNPT

Futures are mixed after hours: S&P 500 futures are +0.36 from fair value of 1573.74 and Nasdaq100 futures are -3.46 from fair value of 2827.46.
Tomorrow morning before the open two economic report is scheduled to be released: 1) Initial Claims (Consensus 355k) and 2) Continuing Claims (Consensus 3060k).
Tomorrow before the open the following companies are scheduled to report earnings: NTCT, PH, ABC, ALK, AME, AVT, BC, BMY, CCMP, CELG, CLP, CSH, DLX, EQT, ESI, GMT, KMT, LUV, MDP, MMM, NMM, ORI, RTN, RYN, STEL, SWK, UAL, UCBI, BIIB, BSX, HOG, HZO, JBLU, RDWR, UBSI, COP, LLL, WRLD, AZN, BLL, BMS, CAM, CL, CNX, CRR, CRS, D, DEST, DNKN, DOW, DST, HHS, HP, HSY, LANC, LSTR, MJN, MO, OXY, PHM, POT, TWC, UPS, ZMH, BCO, LEA, UFS, XOM, BHE, RCL, DO, SXC, CFX, LPLA, BG, CCE, CLI, GPK, KKR, MNI, NBL, NYT, ODFL, PTEN, RTIX, SIAL, TSRA, BLC, ETR, IVC, NLSN, HERO, LVLT, ASPS, PRLB, ALXN, BWA, CAB, CNMD, ECOL, NCI, NWE, O, PDS, STC, TMS, WBC, ICLR, YNDX, IDCC, PVR, VTNC, CMS, DAN, FAF, IMAX, JAKK, LBY, LINE, LTM, RS, SCG, SUI, SWY, TASR, VAC, VCI, VDSI, GGS, EME, GTI, PCS, RRD, TRS, UTHR, CRI, AIXG, GTLS, LKQ, MTRN, NAFC, SFE, SNMX


Commodities


Treasuries


Next Day In View 


Jason's Commentaries


Spent half of my day buying a new computer as my computer decided to die on me last night. RIP my AMD com. It served me great for the past 3 years. 

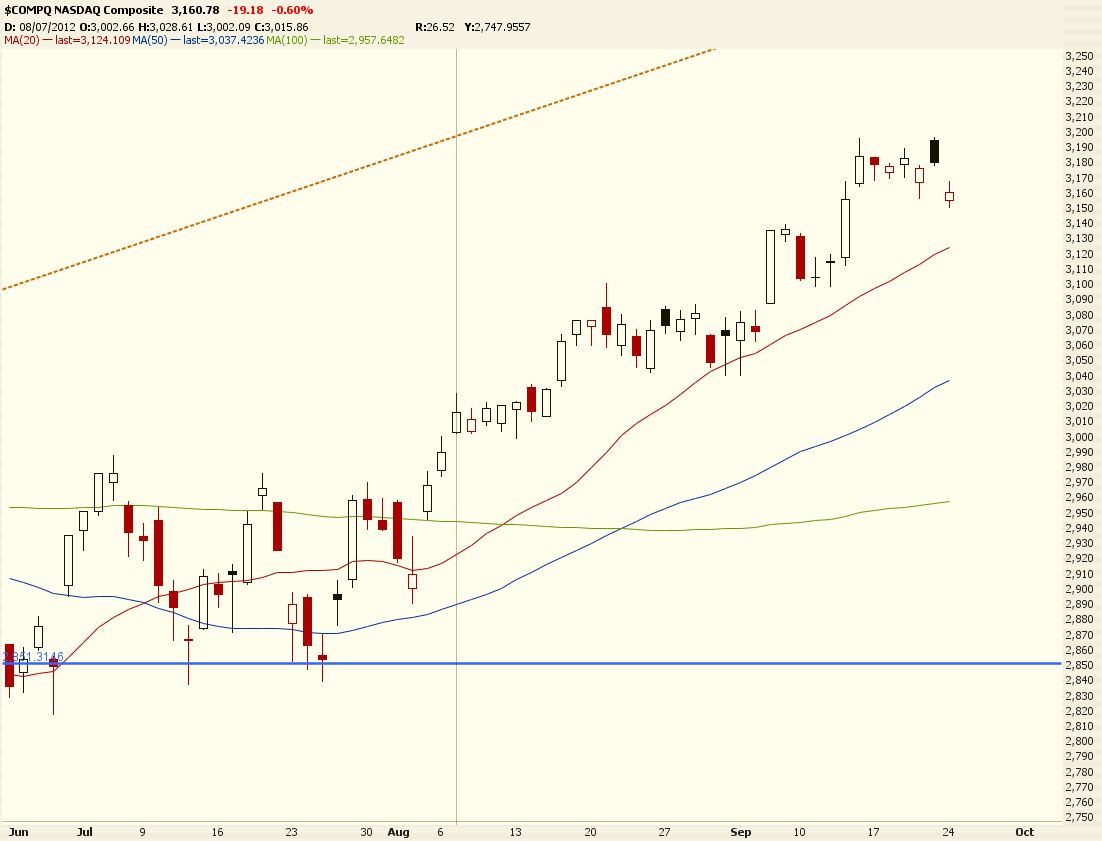
 Was right for last night's call. It was mixed for Wednesday after all the earnings. However, We've more earnings coming on Thursday. Looking at the internals, we have approx 700 shares traded last night in NYSE and the UVOL outpaced the DVOL. Staples and healthcare were the only laggard last night which can be deemed as bullish as well. However, we gotta monitor the defensive sectors a little more deciding on the course of action. On the technical updates, we're likely to be sideway bounded after the hanging man. We're gonna have a volatile Thursday again.


Market Call: Flat to upside
Date: 24 Apr 2013

Wednesday, 24 April 2013

23 Apr 2013 AMC


23 Apr 2013 AMC
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 

Stock Market Update
16:10 ET Dow +152.29 at 14719.46, Nasdaq +35.78 at 3269.33, S&P +16.28 at 1578.78 : [BRIEFING.COM] Equities settled with strong gains as the S&P 500 climbed 1.0%.

Although stocks ended near their highs, an afternoon headline from a hacked Twitter account of the Associated Press suggested two explosions occurred at the White House, sending the S&P lower by 15 points and back to its flat line before returning to session highs. The entire episode unfolded within the matter of five minutes.

Overseas developments primed U.S. equities for an upbeat start to the session. Although economic data from the old continent was largely disappointing, commentary from the region overshadowed the data.

Manufacturing and Services PMI reports from France and Germany came in below 50, a level which indicates contraction. This fueled speculation about a possible European Central Bank rate cut at its upcoming policy meeting. In addition, European Commission President Jose Manuel Barroso was quoted as saying the policy of austerity "has reached its limits."

The talk of further monetary easing combined with Mr. Barroso's comments buoyed European indices, and contributed to an upbeat start to the U.S. session.

Financials and technology led today's advance with bank stocks outperforming notably. The SPDR Financial Select Sector ETF (XLF 18.42, +0.32) settled higher by 1.8% after Discover Financial Services (DFS 44.34, +0.73) and Dow componentTravelers (TRV 86.35, +1.77) reported better-than-expected earnings.

Elsewhere, the tech space saw broad gains and Netflix (NFLX 216.99, +42.62) surged 24.4% following its bottom-line beat. Chipmakers also rallied on the back of above-consensus quarterly results from ARM Holdings (ARMH 46.32, +6.08) andTexas Instruments (TXN 35.70, +0.89). Meanwhile, the broader PHLX Semiconductor Index advanced 2.1%. Also of note, the largest tech stock, Apple (AAPL 406.13, +7.46), gained 1.9% ahead of its quarterly report, which will be released this evening.

The discretionary space was another group which displayed considerable strength thanks to retailers and homebuilders. Coach (COH 55.55, +4.96) jumped 9.8% after beating on earnings while the SPDR S&P Retail ETF (XRT 71.56, +0.84) climbed 1.2%.

Also of note, the SPDR S&P Homebuilders ETF (XHB 29.65, +0.74) rose 2.6% after five builders were upgraded at Barclays. In addition, today's economic data contributed to the sector outperformance.

New home sales increased 1.7% in March to 417,000. There was no revision to the February report, which indicated 411,000 new homes were sold. That March number is still down from the recent January peak when 445,000 homes were sold. The Briefing.com consensus expected sales to increase to 415,000.

Inventory levels inched higher, rising from 150,000 in February to 153,000 in March. That represents a 4.4-month supply and is still well below levels considered normal. Like existing homes, new home inventories should trend around a 6.0-month supply when the industry is in good shape.

Tomorrow, the weekly MBA Mortgage Index will be reported at 7:00 ET while March durable orders and durable orders ex-transportation will be announced at 8:30 ET. On the earnings front, Boeing (BA 88.18, +1.24) and Ford Motor (F 13.36, +0.30) will shed light on their first quarter results before the opening bell.

The U.S. Treasury will auction off $35 billion in 5-yr notes. ..NYSE Adv/Dec 2424/607. ..NASDAQ Adv/Dec 1898/563.


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

Seems that i was totally wrong last night. Good earnings coming out from major market players like Du Pont, Coach, Bank of America got upgraded by Morgan Stanley, ARM instrument, Texas Instruments, Apple, Netflix. However, something bizzare happened last night, Associated Press's twitter account got hacked, sending out tweets that President Obama got injured. Market sunk immediate and bounced back 5 mins later. That is clearly the work of high-frequency traders. Last night was clearly bullish but with normal volumes. TRIN started bearish and reversed during the day. And the main indices have crossed the 20MA again. 


Market Call: Flat to upside
Date: 24 Apr 2013

Tuesday, 23 April 2013

22 Apr 2013 AMC


22 Apr 2013 AMC
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
16:10 ET Dow +19.66 at 14567.17, Nasdaq +27.50 at 3233.55, S&P +7.25 at 1562.5 :[BRIEFING.COM] The S&P 500 ended higher by 0.5% despite enduring some intraday weakness while the Dow added 0.1%, and the tech-heavy Nasdaq gained 0.9%. 

Technology stocks led from the start with Microsoft (MSFT 30.83, +1.06) providing considerable support after ValueAct announced a $2 billion stake in the software company. Other tech shares also displayed strength as Apple (AAPL 398.67, +8.14) climbed 2.1%. 

Although most large tech names ended with gains, IBM (IBM 187.83, -2.17) shed 1.1% to follow Friday's earnings-driven 8.3% drop. Interestingly, General Electric (GE 21.35, -0.40) and McDonald's (MCD 99.32, -0.60) remained under pressure after the two also provided disappointing earnings on Friday. 

The underperformance of those names weighed on the Dow, which spent the bulk of today's session in negative territory. 

Two of the weakest sectors of the month, energy and materials, ended atop today's leaderboard. The energy space gained 1.0% as better-than-expected earnings from Halliburton (HAL 39.29, +2.08) and a 1.1% rise in crude oil provided support the sector. 

Elsewhere, the materials space settled higher as gold miners shook off their recent weakness. The Market Vectors Gold Miners ETF (GDX 28.97, +0.38) gained 1.3% as gold futures rose 2.1% to $1425.20. 

While precious metals were able to rebound from last week's selloff, copper remained under pressure. The red metal shed 0.6% as global growth concerns stayed on the minds of investors. 

The ongoing growth concerns were echoed by Caterpillar's (CAT 82.71, +2.28) quarterly report, which missed on the earnings and revenue. In addition, the machinery producer lowered its full-year earnings and revenue guidance below consensus. Although Caterpillar ended higher, the industrial sector settled with a loss of 0.1%. 

The utilities sector was the only other group which settled with a loss as the SPDR Utilities Select Sector ETF (XLU 40.68, -0.05) ended lower by 0.1%. 

Today's volume was below average as just over 620 million shares changed hands on the floor of the New York Stock Exchange. 

Reviewing the day's economic data, existing home sales fell 0.6% from a downwardly revised 4.95 million (from 4.98 million) in February to 4.92 million in March. The Briefing.com consensus expected existing home sales to increase to 5.01 million. 

Inventories managed to eke out a small gain, rising 1.6% to 1.93 million. That represents a 4.7-month supply at the current sales rate, which is down from a 6.2-month supply a year ago. According to the National Association of Realtors, an ideal inventory level is around a 6-month supply. 

Tomorrow, February FHFA Housing Price Index and March new home sales will be reported at 9:00 ET and 10:00 ET, respectively. Among earnings of note, Delta Air Lines (DAL 15.14, -0.12) and Johnson Controls (JCI 33.15, +0.51) will report their quarterly results ahead of the opening bell. 

The U.S. Treasury will auction off $35 billion in 2-yr notes. ..NYSE Adv/Dec 1739/1260. ..NASDAQ Adv/Dec 1275/1175.


After Hours
17:54 ET NFLX +24.3%, VECO +8.6%, ILMN +5.2%, BEAT -11.2%, RCII -6.7%, VLTR -4.6% following earnings/guidance :
The S&P 500 ended higher by 0.5% despite enduring some intraday weakness while the Dow added 0.1%, and the tech-heavy Nasdaq gained 0.9%. 
Other notable movers on earnings/guidance: NFLX +24.3%, VECO +8.6%, ILMN +5.2%, SWFT +4.6%, XOOM +4.1%, TXN +0.8%, PKG +0.2%, BEAT -11.2%, RCII -6.7%, VLTR -4.6%, ICUI -0.6%, AMP -0.3%, ACE -0.3%, RCI -0.1%, ZION -0.1%
Today after the close the following companies reported earnings: VECO, PKG, TXN, VLTR, BXS, HXL, NFLX, SWFT, WIBC, BBCN, CR, ELS, ILMN, PLXT, RCII, SANM, ZION, ACE, MBFI, AMP, NXPI, STM, ICUI, IEX, RCI, USTR, CTGX, UCTT, PEI, HSTM, XOOM
Futures are mixed after hours: S&P 500 futures are +0.49 from fair value of 1557.41 and Nasdaq100 futures are -1.55 from fair value of 2803.80.
Tomorrow morning before the open one economic report is scheduled to be released: 1) FHFA Housing Price Index.
Tomorrow before the open the following companies are scheduled to report earnings: DFS, FRX, IRWD, JCI, CLS, DAL, DD, EAT, FMER, IIVI, RF, SBNY, SNV, TRV, TWIN, WAT, APD, COH, LCC, MOLX, UTX, AOS, JNS, LMT, XRX, AKS, AXE, CIT, GNTX, IDXX, ITW, LXK, PCH, PII, PNR, STBA, WDR, DHX, FCF, ST, ENTG, PCAR, R, IR, GCI, ACI, ARMH, CNC, LRY, PMT, CPLA, RAI, ECA, ORB, LECO, SAH, ASTE, RSH


Commodities


Treasuries


Next Day In View 


Jason's Commentaries


Kinda expected of this movement last night. The day start bearish and subsequently reversed to close higher by 1030am ET. Internals were all showing mixed signals with a moderate volume traded in the NYSE. Energy and the Materials were the main leaders last night with Haliburton beating its earnings and rose a $2.50. While Caterpillar, despite missing it's earnings and revenues, rose $3 last night, which provided strength in the market. And today, we'll have a number of notable earnings coming and it's going to be really really volatile. With Apple affecting the Techs, Reynolds affecting the discretionary, Lockheed Martin and United Technologies affecting the industries, we're gonna see a very messy day. On top of that, we have new home sales coming out at 10am. To make things worse, China missed it's HSBC PMI. On the Technical update, we're likely to see a down day today as all 3 indices found resistance at the 20MA and we're on the 3rd candle reversal. Let's go bear =D

Here's the link to China's PMI news. 
http://www.cnbc.com/id/100662646 


Market Call: DOWN
Date: 23 Apr 2013

Monday, 22 April 2013

19 Apr 2013 AMC


19 Apr 2013 AMC
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Commentaries 
Stock Market Update
16:25 ET Dow +10.37 at 14547.51, Nasdaq +39.69 at 3206.05, S&P +13.64 at 1555.25 : [BRIEFING.COM] The major averages entered the weekend on a mixed note. The S&P 500 settled higher by 0.9% while the Dow Jones Industrial Average ended with a slim gain of 0.1%.

The 30-stock Dow trailed behind the broader market as General Electric (GE 21.75, -0.92), McDonald's (MCD 99.92, -1.99), and International Business Machines (IBM 190.00, -17.15) pressured the price-weighted index after reporting earnings.

Of the three names, General Electric and McDonald's reported in-line results, but the two echoed the ongoing global growth concerns with their commentary. IBM, meanwhile, missed on earnings and reported revenue more than $1 billion below the Capital IQ consensus estimate. Shares of IBM tumbled 8.3% to surrender all of their year-to-date gains.

While the Dow spent the entire day in negative territory, the S&P 500 climbed steadily as some of the biggest laggards of the week appeared among today's leaders. Interestingly, the rally staged by the S&P stalled right near Monday's closing levels.

With the market rebounding broadly, seven of 10 sectors ended with gains of at least 1.0%. Leadership was mixed as cyclical and defensive groups displayed strength.

Energy, technology, and industrials were the only three sectors which lagged. The energy space ended flat as crude oil added 0.2% to $88.20.

Elsewhere, tech shares were pressured by IBM's disappointing earnings. In other news of note, Dell (DELL 13.40, -0.55) lost 3.9% after Blackstone ended its attempt to acquire the company.

Meanwhile, Google (GOOG 799.87, +33.96) and Microsoft (MSFT 29.76, +0.98) kept the sector from registering further losses after the two beat on earnings.

The industrial space was the third notable laggard as General Electric weighed. Excluding the industrial heavyweight, other sector components held up relatively well. The Dow Jones Transportation Average climbed 1.5% after sliding 3.3% during the first four sessions of the week.

Today's advance eased some fears of a looming correction as the CBOE Volatility Index (VIX 14.88, -2.68) slipped back to Tuesday's closing level. However, the near-term volatility index remains above 12.07, where it ended last week.

Today's volume total was aided by options expiration. As a result more than 900 million shares changed hands on the floor of the New York Stock Exchange.

There was no economic data of note released today.

On Monday, March existing home sales will be reported at 10:00 ET. 


Commodities


Treasuries


Weekly Analysis
Week 38


Technical Updates


Briefing's Commentaries

On Monday, equities sold off steadily throughout the day, and the S&P 500 lost 2.3%, registering its biggest one-day drop of the year. The major averages were pressured from the opening bell as global growth concerns returned to the forefront. In China, first quarter GDP rose 7.7%, which was below the expected growth of 8.0%. The disappointing report added to the weakness of the commodity complex, which saw an extension of last week's selling. Gold miners endured a rough session as theMarket Vectors Gold Miners ETF (GDX 28.59, +0.37) fell 9.9% on the heels of a 9.5% plunge in gold to $1356.80. Meanwhile, silver tumbled 13.0% to $22.90. 

Tuesday brought some relief as the S&P 500 climbed 1.4%. While the economically-sensitive materials space was able to rebound and end atop the leaderboard, the defensively-geared consumer staples were not far behind. Staple stocks received some support from Coca-Cola (KO 42.66, +0.56) after the beverage giant narrowly beat the Capital IQ earnings estimate. A defensive bid also buoyed the health care sector where Johnson & Johnson (JNJ 84.49, +1.31) gained 2.1% after beating on earnings. 

Sellers reemerged during Wednesday's session as the S&P 500 tumbled 1.4%. Technology stocks felt the brunt of the drop as the SPDR Technology Select Sector ETF (XLK 29.35, +0.04) lost 2.1%. Apple (AAPL 390.53, -1.52) dipped below $400 for the first time since December 2011, and settled lower by 5.5%. 

Thursday saw a continuation of Wednesday's selling. The S&P 500 shed 0.7% to close below its 50-day moving average for the first time since December 28, 2012. Cyclical sectors were under pressure with technology stocks once again finishing among the laggards. Elsewhere, the cyclical discretionary sector also finished in the red as homebuilders slumped. ..NYSE Adv/Dec 2189/817. ..NASDAQ Adv/Dec 1684/780.

Next Week In View


Jason's Commentaries

Oh well... Market was up again... it seems that the market still has some strength to sustain not its not going down streak.. Although the Dow lagged behind due to IBM's weak earnings, the wider market is performing well. S&P500 was up near a 1% and the energy sector was the only laggard. Tech outperformed as Google and Microsoft was able to do well in their earnings. However, I do not see much upside in the market as a significant number of the Dow components and the big caps stocks are missing their earnings. Such as IBM, Bank of America etc. On the technical update, on the weekly side we have a chopstick top, while we're likely have a 3rd candle reversal. On Friday, we're also have the treasuries dropping as well. On Monday, we do not have much economic data coming out except the housing data. However, we have much more earnings coming tomorrow, which means it will hell of a gyration on Tuesday


Market Call: Flat to upside
Date: 22 Apr 2013