Tuesday, 26 February 2013

26 Feb 2013 AMC


26 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
16:15 ET Dow +115.96 at 13900.13, Nasdaq +13.40 at 3129.65, S&P +9.09 at 1496.94 : [BRIEFING.COM] The S&P 500 ended today's session with a gain of 0.6% despite enduring some early weakness. The benchmark average started the day on a positive note with upbeat economic data proving insufficient in staving off the early selling pressure. However, markets staged a rebound in afternoon trade with the key indices climbing to fresh highs. 

Consumer discretionary stocks were among today's top performers, largely due to upbeat February consumer confidence, which was reported at 69.0. In addition, January new home sales of 437,000 were reported well ahead of the Briefing.com consensus. 

The strong housing data coupled with a healthy rise in December home prices provided support for homebuilders. DR Horton (DHI 22.25, +0.88) and Lennar (LEN 38.01, +1.35) both gained near 4.0%, and the broader SPDR S&P Homebuilders ETF (XHB 27.77, +0.80) advanced 3.0%. 

Discretionary shares also received support after Home Depot (HD 67.56, +3.64) reported better-than-expected earnings and revenue. In addition, the company hiked its quarterly dividend by 34% to $0.39/share and authorized a $17 billion share repurchase program. The Dow component jumped 5.7%, contributing to the relative strength of the blue chip average. 

While discretionary shares outperformed, consumer staples finished as one of the weakest sectors. Tyson Foods (TSN 22.40, -0.86) slipped 3.7% after saying margin compression has taken a bite out of its beef and pork segments. Meanwhile, United Natural Foods (UNFI 50.45, -2.55) slid 4.8% after guiding on the low end of analyst estimates, citing rising costs. 

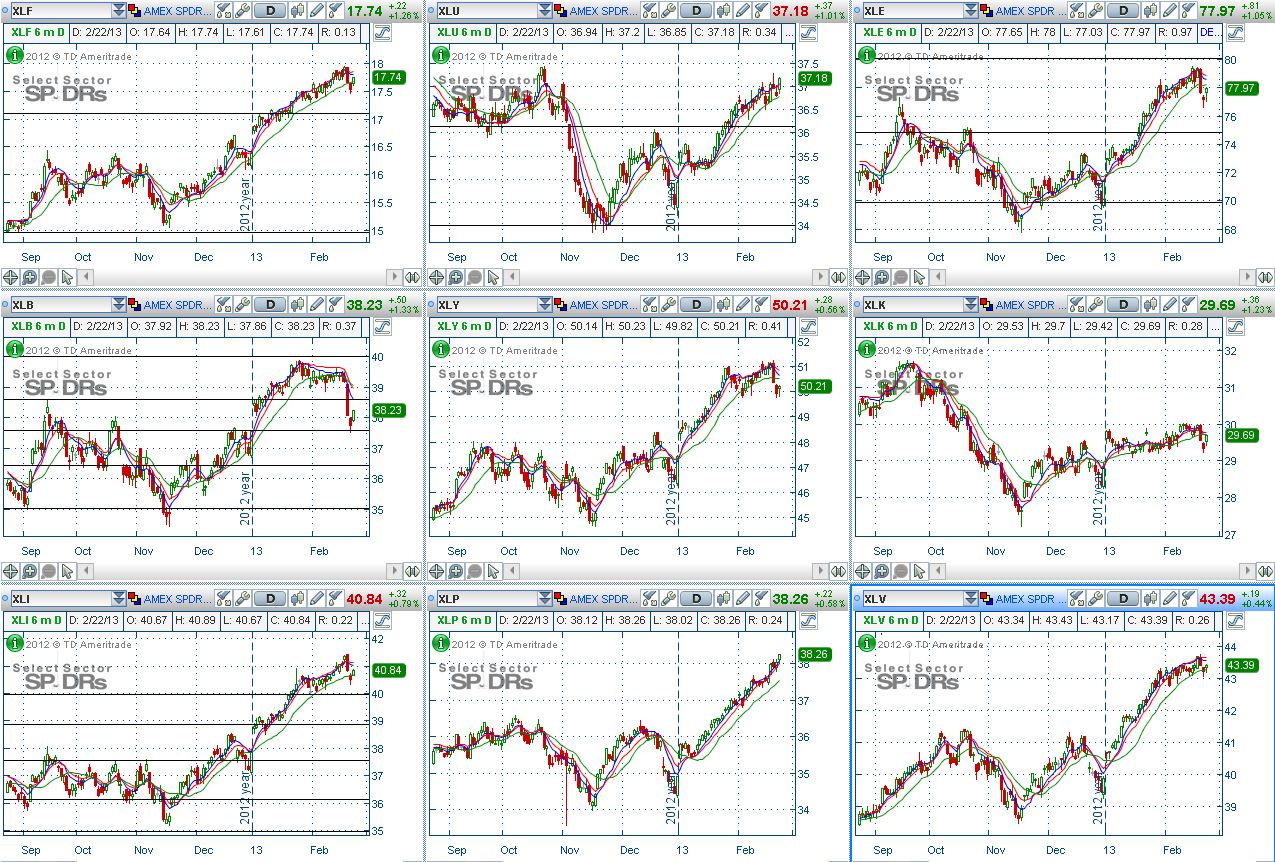
The materials sector has been one of the weakest performers dating back to last week, but the space led today's rebound. The SPDR Materials Select Sector ETF (XLB 37.75, +0.40) gained 1.1% amid outperformance from chemical and paper producers. Monsanto(MON 99.20, +1.11) advanced 1.1% and International Paper (IP 42.75, +0.96) climbed 2.3%. 

Similar to materials, the financial sector has shown notable sensitivity to the market swings of recent days. With exposure to Italian and other sovereign debt, a rise in political uncertainty runs the risk of turning into financial instability. Today, bank stocks trailed behind the broader market and the SPDR Financial Select Sector ETF (XLF 17.35, +0.09) added 0.5%. 

Floor volume at the New York Stock Exchange was slightly above average as 772 million shares changed hands. Notably, today's session saw thinner volume than yesterday's sell off with the Tuesday total also running behind high volume sessions of last week. 

With the focus remaining on Italy, concerns over the country's near-term future were also brought up during today's Humphrey-Hawkins Testimony. Speaking before the Senate, Fed Chairman Ben Bernanke said that a need to write-down Italian debt would not inflict serious damage on U.S. financial institutions. 

The rest of Mr. Bernanke's remarks at today's testimony have struck a now-familiar tone. The Chairman highlighted the perceived benefits of current monetary policy but also acknowledged very low interest rates could push portfolio managers into a "reach for yield," thus causing them to assume outsized risk. 

Regarding the March 1 implementation of automatic spending cuts known as the "sequester," the Chairman does not expect to see an immediate impact, but foresees a build-up of effects over time. 

In tomorrow's economic data, the weekly MBA Mortgage Index will be reported at 7:00 ET. At 8:30 January durable goods and durable goods ex-transportation will be released. The day's economic data will be topped off with the 10:00 ET release of January pending home sales. 

Also at 10:00 ET, Fed Chairman Ben Bernanke will testify before the House Financial Services Committee, concluding the two-day event. On the earnings front, Joy Global(JOY 59.96, +0.26) and Target (TGT 64.05, +1.16) are scheduled to report their quarterly results before the opening bell. 

The U.S. Treasury will auction off $29 billion in 7-yr notes. ..NYSE Adv/Dec 1989/1007. ..NASDAQ Adv/Dec 1488/971.


After Hours
18:16 ET GWRE +14.8%, BGFV +7.9%, AH -18.7%, FSLR -10.1% following earnings/guidance :
The S&P 500 ended today's session with a gain of 0.6% despite enduring some early weakness. The benchmark average started the day on a positive note with upbeat economic data proving insufficient in staving off the early selling pressure. However, markets staged a rebound in afternoon trade with the key indices climbing to fresh highs.

Other notable after hours movers on earnings: GWRE +14.8%, BGFV +7.9%, UNXL +6.4%, ZAGG +4.6%, EIX +4.1%, KAI +3.7%, MAKO +3.3%, PCLN +3.0%, DY +2.3%, NUVA +2.1%, JAZZ +1.7%, AVGO +1.7%, RRC +1.2%, GPOR +0.8%, AH -18.7%, FSLR -10.1%, QCOR -6.2%, SPN -0.8%, LYV -0.7%, WFT -0.7%, DWA -0.6%, TTEC -0.2%, GA -0.2%, BIO -0.1%

Today after the close the following companies reported earnings: HSTM, QCOR, NUVA, RRC, SPN, KAI, DGI, EXAC, VRSK, NATL, PZZA, WTI, BGFV, DWA, EIX, FSLR, PCLN, VNO, ZAGG, LYV, BIO, GPOR, MIDD, ORA, REXX, STEC, AWK, ENPH, MAKO, TTEC, JAZZ, GA, DY, GWRE, TIVO, AVGO

Futures are lower after hours: S&P 500 futures are -2.09 from fair value of 1495.19 and Nasdaq100 futures are -1.81 from fair value of 2712.31.

Tomorrow morning before the open three economic reports are scheduled to be released: 1) MBA Mortgage Index, 2) Durable Orders (Consensus -3.5%), and Durable Goods (Consensus 0.2%).

Tomorrow before the open the following companies are scheduled to report earnings: FDML, CRI, VPHM, CBB, DIN, SWC, PDCE, FIG, ITT, NRG, ARCC, AFAM, AES, AH, CNP, LAMR, OGE, SRT, STWD, SUSS, HII, INXN, TJX, AMAP, DLTR, PACT, TGT, GLOG, LTXC, JOY


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

The market went higher than I expected, Dow registered 100 points gain,. With the VIX retracing a 11.16%, and the internals are slightly bullish biased, I would say yesterday was a bullish day, especially after a 200 points drop from previous day. However, it's important to note that there are only 3 sectors that are performing at the range of near 1% yesterday, not exactly that strong for a 100 points gain on the Dow. While looking at the technicals, I would say this rebound is somewhat expected. Ben Bernanke testified yesterday at 11am and started to rebound after that. It's also important to note that the Treasuries rallied yesterday as well. Nonetheless, I'll be looking for more confirmation to stay bear. 


Market Call: FLAT to downside
Date: 27 Feb 2013

25 Feb 2013 AMC


25 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

Right on my call on the market on Monday. The market gapped up at the initial which stopped me out at my short position, then wasn't able to break above the opening high and started going down. After lunch, weakness is seen the in market and subsequently sold off during the last hour of trading. While we're having the highest trading volume for the year in the NYSE, over 820 million shares traded, we also have the biggest drop for 2013. The bears ruled the day and we're having a bearish engulfing pattern on all 3 indices. The financials were the biggest laggard, along side with the Energy, Industrials and Material Sectors. If we're having another down day today, we're likely to correct very soon. To make the volatile market more volatile, Ben Bernake is speaking at 11am ET later. Stay tune..

Market Call: FLAT to downside
Date:  26 Feb 2013

Sunday, 24 February 2013

22 Feb 2013 AMC


22 Feb 2013 AMC
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Commentaries 


Stock Market Update
16:30 ET Dow +119.95 at 14000.57, Nasdaq +30.33 at 3161.82, S&P +13.18 at 1515.6 : [BRIEFING.COM] The S&P 500 gained 0.9% to rebound from its two-day slide which saw the index drop just under 2.0%. However, despite today's rally, the benchmark average was unable to register a higher close for the week, thus snapping its streak of seven consecutive weekly gains. 

Stocks began the session on a positive note amid upbeat European trade. The bullish bias across the old continent was attributed in part to a better-than-expected Ifo Business Climate Survey out of Germany. 

With no domestic economic data of note, attention was centered mostly on earnings as several notable companies reported their results. 

Hewlett-Packard (HPQ 19.20, +2.10) jumped 12.3% after beating on earnings and revenue. The company also issued upbeat second quarter earnings guidance, but it should be noted the stock was trading near its all-time lows as recently as late November. That multi-year weakness has caused analysts to lower their expectations for the computer company. 

Elsewhere in tech, semiconductor manufacturers outperformed after begin one of the weakest groups yesterday. Contributing to the strength was Texas Instruments (TXN 34.18, +1.70), which climbed 5.2% after hiking its quarterly dividend by 33% to $0.28 and announcing the authorization of an additional $5 billion in funds aimed at repurchasing company stock. Meanwhile, the broader PHLX Semiconductor Index gained 2.1%. 

Financials also finished among the leaders. American International Group (AIG 38.45, +1.17) advanced 3.1% after beating bottom line estimates on revenue below consensus. 

Also of note, the materials sector underperformed throughout the week but was today's top advancer. On Tuesday, basic materials settled in the red despite a broad market advance. As stocks sold off on Wednesday and Thursday, the sector led to the downside amid weakness in industrial and precious metals. As a result, the space is now registering the slimmest gains of the year among the 10 sectors. 

Although cyclical stocks outperformed, this was not the case with consumer discretionary shares. Retailers saw relative weakness and the SPDR S&P Retail ETF(XRT 67.31, 0.00) ended flat. Abercrombie & Fitch (ANF 46.86, -2.19) settled as the weakest S&P 500 component after beating on earnings ex-charges and announcing plans to shutter up to 50 stores. 

With consumers adjusting to lower spending power resulting from the expiration of the payroll tax cut, profit warnings from consumer companies have become more frequent. This morning, Darden Restaurants (DRI 46.23, +1.49) issued downside third quarter earnings guidance with higher payroll tax as well as rising gasoline prices cited as the reason. 

Reviewing today's S&P 500 sector performance, materials (+1.3%), technology (+1.2%), financials (+1.2%), and utilities (+1.1%) led the way. On the downside, health care (+0.4%), consumer staples (+0.5%), and consumer discretionary (+0.6%) registered slimmer gains than the broader market. 

Today's volume was below average as less than 690 million shares changed hands on the floor of the New York Stock Exchange. This suggests the rally may not have been built on the same conviction as the recent sell off, which saw the two highest volume sessions of 2013. 

There is no economic data scheduled to be released on Monday. However, it should be noted that the closely-contested Italian general election is scheduled to take place on Sunday and Monday of next week. 
Commodities


Treasuries


Weekly Analysis
Week 38


Technical Updates


Briefing's Commentaries


Week in Review: S&P 500 Snaps Seven Week Winning Streak 
On Monday, equity and bond markets were closed in observance of Presidents Day. 

Tuesday's session saw the S&P 500 settle higher by 0.7% after spending the duration of the day in a steady upward climb. Equities got off to an upbeat start supported in part by bullish European trade. In addition, merger speculation helped support the markets at the open. Health care stocks were in the news when the Centers for Medicare & Medicaid Services proposed lower 2014 Medicare co-payments. The news carried a negative impact for health care providers as Humana (HUM 70.61, -2.04) and UnitedHealth Group (UNH 54.47, -0.77) lost 6.4% and 1.2% respectively. 

On Wednesday, the S&P 500 settled lower by 1.2% after spending the entire session in negative territory. Equities began the day on a lower note amid mixed housing data and hovered near their lows ahead of the Fed's minutes. Stocks then fell to fresh lows after the minutes indicated Committee members saw little change to the economic outlook. Homebuilders sold off in reaction to an earnings and revenue miss reported by Toll Brothers (TOL 34.59, +0.12). Peers PulteGroup (PHM 18.90, +0.15) and D.R. Horton(DHI 22.31, +0.14) were off 6.8% and 5.9% respectively. 

Thursday proved to be an extension of Wednesday's weakness as the S&P 500 settled lower by 0.6%. Stocks began the day in the red and continued sliding into the afternoon when bargain hunters stepped in and lifted the major averages off their lows. The S&P 500 managed to hold the psychologically important 1500 level, avoiding its first close below that mark since February 4. Wal-Mart (WMT 70.40, +0.14) gained 1.5% after beating on earnings. However, the company issued first quarter guidance on the low end of analyst expectations. In addition, Wal-Mart said it expects its comparable store sales to be flat during the first quarter. This suggests the worries regarding consumer spending, expressed in an internal email last week, have some credence to them. ..NYSE Adv/Dec 2246/733. ..NASDAQ Adv/Dec 1770/688.


Next Week In View


Jason's Commentaries

Was right on the call for Friday, DJI went up almost a 120 points, and all 3 main indices posted some decent gains. The VIX lost a total of 6.9% on Friday when HP came in fantastic results and spiked a 12% gain. On the Dow, We have KO, GD, AXP,DD and IBM performing exceptionally well on Friday, each with a gain of more than 1.5% which allow DJI to lock in such huge gain. Although there was not much economic news coming out on Friday, earnings drove the day up. Looking at the internals, volumes was not very impressive, having a mere 680 Million shares traded on the NYSE, which is slightly lower than the average traded volume. Although, the bulls were outpacing the bears, it seems that the bears was able to stand their ground a little.The treasuries looked a little divergence on Friday. While the market is rallying on Friday, Treasuries did the same thing with the 5,10 and 30 year.

While on our 9 main sectors, the leaders were the financials, Tech, Utilities and Materials. Financials were being led by Morgan Stanley, AIG, Prudential, Goldman Sachs, Charles Schwab, Legg Mason and BlackRock. Each having a gain of more than 2% on the Friday. While on the Materials, It was companies like Du Pont, Dow Chemicals and Eastman Chemical which led the sector. Not to mention Mosaic, Aloca, CF Industries were down in materials. While on the Tech, HP, Texas instrument, Symantec led the sector up tremendously, having a gain of more than 2.5% each.  And if we were to look at the weekly performance of the 9 sectors, the Industrials, Materials, Consumer Discretionary, Tech and Healthcare seems to be losing a little of their steam and might be correcting soon. The industrials were being bogged down by the Defense Industry, Healthcare being dragged by the HMOs, the Materials were lagged by the Agriculture Industry. And tech namely were weighed down by the giant Apple.

As we're entering the end of Feb, which is likely to mark the end of this flat and volatile month, we're also expecting the Congress to decide and act on the Fiscal Cliff and debt ceiling issues which has been postponed since Jan. This coming week also mark the first week of Mar, which the first trading day of Mar has been down 4 times out of 6, up 9 of 11 times. While we're looking at the chart, we're definitely still in a consolidation phase.My dear friend, Jason Tan, http://strongerhead.com, has noted something very interesting on the consolidation period of the market at its highs, which is worth spending a few minutes of your time reading it.

While we're coming to an end of the earnings season, here's the report card on the S&P 500 stocks.

Out of the 500 stocks,
86.5%, announced their earnings.
63.3% beat their earnings
11.4% just met their earnings
25.2% missed their estimate.

Having a 25% missing their Q4 results is not exactly a good thing for the market.


Market Call: DOWN
Date: 25 Feb 2013

Friday, 22 February 2013

21 Feb 2013 AMC


21 Feb 2013
Market Summary 


Market Internals


Leaders and Laggards


Technical Updates


Briefing's Commentaries 


Stock Market Update
16:25 ET Dow -46.92 at 13880.62, Nasdaq -32.92 at 3131.49, S&P -9.53 at 1502.42 :[BRIEFING.COM] The S&P 500 settled lower by 0.6% after today's session saw an extension of yesterday's selling. Equities began the day in the red and continued sliding into the afternoon when bargain hunters stepped in and lifted the major averages off their lows. The S&P 500 managed to hold the psychologically important 1500 level, avoiding its first close below that mark since February 4. 

Meanwhile, the Dow shed 0.3%, and registered slimmer losses than the other two averages. The outperformance was largely due to the strength of Wal-Mart (WMT 70.26, +1.05), which gained 1.5% after beating on earnings. However, the company issued first quarter guidance which was on the low end of analyst expectations. In addition, Wal-Mart expects its comparable store sales to be flat during the first quarter. This suggests the worries regarding consumer spending, expressed in an internal email last week, have some credence to them. 

Wal-Mart also contributed to the strength of consumer staples which finished with a gain of 0.3%. The defensively-oriented sector also received support from Hormel Foods (HRL 36.51, +0.39) and Safeway (SWY 22.97, +2.84), both of which climbed on earnings. Hormel reported quarterly results in-line with the Capital IQ consensus while Safeway eclipsed its earnings expectations by $0.19. 

As staple stocks held strong for the bulk of the session, telecoms joined in during afternoon trade and settled higher as well. Verizon Communications (VZ 45.12, +0.20) advanced 0.5% after displaying relative strength in the face of broad selling pressure. 

With defensive sectors ending in the black, cyclical stocks were among the biggest laggards. Materials led to the downside for a large portion of the day, and finished as the day's weakest sector. Chemical producers underperformed after Dow Chemical (DOW 30.84, -0.80) was ordered to pay $400 million in a case involving price fixing. 

The materials sector was yesterday's biggest laggard as well. Today's intraday weakness caused it to surrender all of its year-to-date gains, but late-afternoon buying helped the space climb back into the black for 2013. However, its 2013 advance has been trimmed to just 0.1%. 

Elsewhere, the tech space followed closely behind materials. This occurred despite the slight outperformance from its largest component, Apple (AAPL 446.06, -2.79). 

Tech shares saw some notable pressure from chipmakers as Rubicon Technology(RBCN 4.92, -0.85) plunged 14.7% on disappointing earnings and cautious guidance. Meanwhile, the broader PHLX Semiconductor Index fell 1.8%. 

As a result of today's selling, the CBOE Volatility Index (VIX 15.42, +0.74) jumped for the second day in a row. The near-term volatility measure has now risen to its highest close of the year. 

Reviewing S&P 500 sector performance, materials (-0.9%), technology (-0.9%), financials (-0.9%), and industrials (-0.9%) led to the downside while consumer staples (+0.3%) and telecoms (+0.2%) outperformed. 

Volume was above average once again as 814 million shares changed hands on the floor of the New York Stock Exchange. 

Today's economic data was plentiful with most reports falling largely in-line with expectations. Weekly initial claims rose to 362,000 which placed the figure right back in the 350,000-400,000 range seen for much of last year. Meanwhile, consumer prices saw no change in January while core CPI ticked higher by 0.3%, slightly ahead of expectations. 

January existing home sales were reported at an annualized rate of 4.92 million which was just a shade below the 4.94 million expected by the Briefing.com consensus. 

Leading indicators for January increased by 0.2%, slightly worse than the Briefing.com consensus which had expected an uptick of 0.3%. Today's figure followed the prior month's rise of 0.5%. 

Lastly, the February Philadelphia Fed Survey fell to -12.5 to follow January's reading of -5.8. Economists polled by Briefing.com had expected that the Survey would improve to 1.5. 

There is no economic data scheduled to be released tomorrow. ..NYSE Adv/Dec 892/2116. ..NASDAQ Adv/Dec 765/1721.


After Hours
18:49 ET PEGA +18.6%, MKTG +9.0%, AWAY +8.8%, PAY -32.6%, RBCN -14.4%, ACHN -7.4% following earnings/guidance :
The S&P 500 settled lower by 1.2% after spending the entire session in negative territory.
Other notable after hours movers on earnings: PEGA +18.6%, MKTG +9.0%, AWAY +8.8%, SNPS +4.9%, JOBS +4.5%, HURN +2.7%, TRN +2.7%, UNTD +2.1%, OEH +1.7%, VRML +1.5%, FELE +1.4%, ACHC +1.4%, ETP +1.2%, AEL +1.1%, PAY -32.6%, RBCN -14.4%, ACHN -7.4%, TSLA -5.9%, SB -5.8%, WLT -5.8%, PPO -5.0%, SYNC -4.6%, SAM -2.3%, CROX -2.3%, CAKE -1.8%, FLR -1.3%, WPZ -1.1%, WIRE -0.5%

Today after the close the following companies reported earnings: LHO, HLX, WCN, ARII, CAKE, CLW, CROX, FR, IDCC, KBR, SYNC, TRN, WIRE, AUY, FST, XCO, DENN, HURN, MDAS, PPO, STR, BALT, DRCO, GNK, HT, NEWP, PVA, SM, WMB, WPZ, AWAY, EQY, FLR, MANT, SAM, TTS, UNTD, AEL, DEPO, FELE, MKTG, TSLA, WLT, CNK, CW, GDP, KAR, QLTY, RBCN, WAGE, CXO, ETE, ETP, HR, LOCK, MHLD, PAAS, RGP, RP, STAG, SXL, PEGA, IAG, SB, SZYM, JACK, SNPS, HEI

Futures are mixed after hours: S&P 500 futures are -2.16 from fair value of 1509.56 and Nasdaq100 futures are -2.55 from fair value of 2739.55.

Tomorrow morning before the open two economic reports are scheduled to be released: 1) Initial Claims (Consensus 358k) and Continuing Claims (Consensus 3150k), and 2) CPI (Consensus 0.1%) and Core CPI (Consensus 0.2%).

Tomorrow before the open the following companies are scheduled to report earnings: HST, SWY, DFRG, LTM, VAC, JAKK, IART, CMS, CWEI, FAF, IMAX, LBY, LINE, RS, SUI, VCI, VDSI, DAN, KDN, TASR, PCG, SPNC, ESV, HSNI, MDSO, PWR, TFX, CHK, DORM, HEP, IDA, IRC, PEG, PKD, PXP, SFY, SMA, WST, CCC, GEO, ICGE, AYR, CBR, CCOI, DNR, LXP, SCG, THS, FNP, CG, GTXI, THI, TK, TNK, ZEUS, BRC, WMT, HRL, PDCO, ZLC, TTC, SAFM


Commodities


Treasuries


Next Day In View 


Jason's Commentaries

Was right on the bearish day yesterday. While the economic reports came out mixed, the market decided to come down within the first hour, and stayed sideways till 2.15pm, and broke up afterwards. There was a minor retracement to the downside during the last half hour. It seems that the bears' momentum has died down quite a bit. Looking at the internals, it's definitely a bear day, but not that bear. The VIX rushed up until afternoon and definitely to give back its gain, ending slightly up. While looking at the sectors, Consumer staples were the only gainer in the market yesterday, with Walmart, Philip Morris, Altria and Constellation Brands holding the sector up, . Consumer Discretionary and Materials were the biggest losers yesterday, but losing less than 1%. 

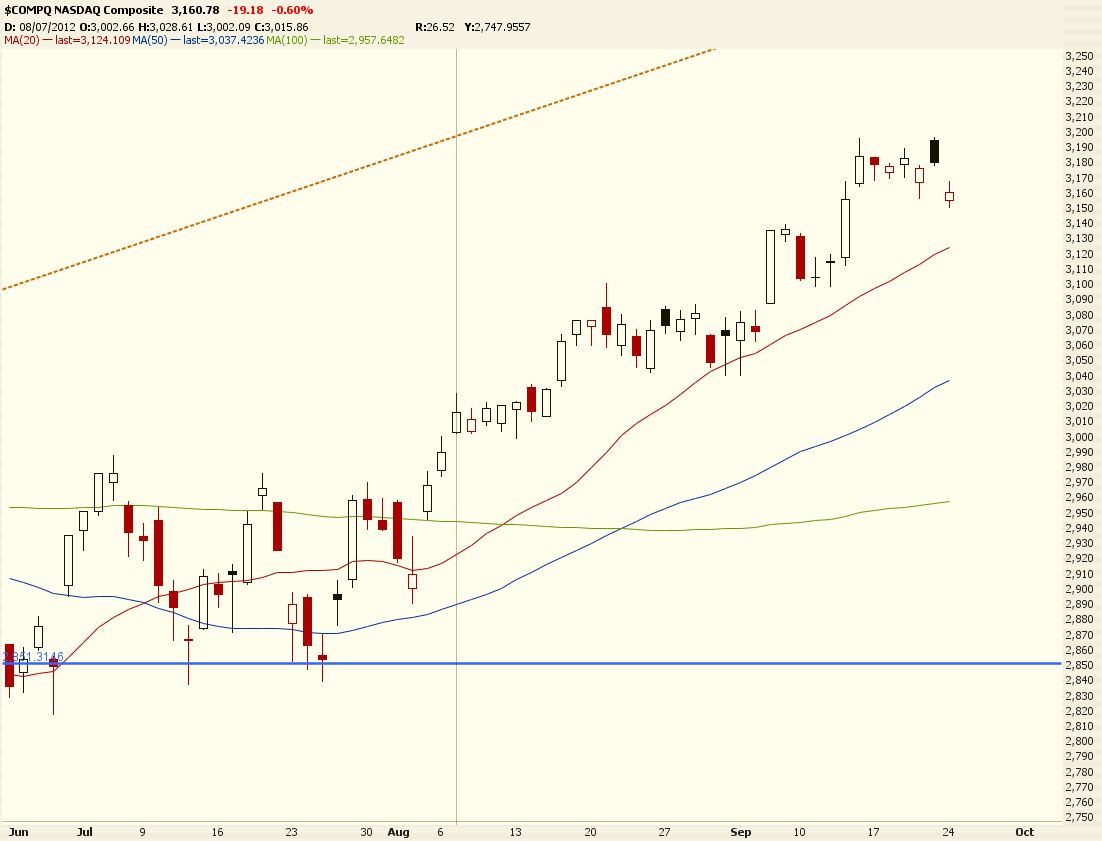
While on the technical side, we're likely to have the 3rd candle reversal on Friday, which it might be pointing to a down week next week. DJI hit a support on a intra-day and Nasdaq was the biggest loser amongst the indices.  The main drag on the indices were Apple and IBM yesterday. Which provided the biggest drag in the indices. The commodities and Treasuries are not showing much action. And furthermore on Friday, we're not likely to have much important reports coming out. It will be a good day to cover the shorts for more traders. 


Market Call: UP
Date: 22 Feb 2013